




Market Brief Stocks Pound Rally
A summary of news and snapshot of moves ahead of the US session.
Share this:


- GBP has been the standout winner in what has been a day of above-normal range in nearly all pound crosses. Could we see some retracement on profit-taking during the NY session? USD has extended its falls for the second day following that poor manufacturing PMI report from yesterday.
- UK services sector PMI was expected to ease to 51.0 from 51.4 but came in at 50.6 – not that it mattered much for the pound, which continued to squeeze the shorts after the dip to sub $1.20 proved to be short-lived yesterday as UK parament seized control of the Commons in a bid to stop no-deal Brexit. MPs will vote later today on a bill that would force Boris Johnson to ask EU for Brexit delay. If the bill passes, the PM has said will call a general election. Today’s services PMI miss means we now have a hat-trick of bad news after both manufacturing and construction PMIs fell deeper into contraction territory earlier this week. Earlier, Eurozone final services PMI was revised a tick higher to 53.5 from 53.4 thanks to upgrades for Germany and Spain. Eurozone retail sales came in -0.6% m/m as expected.
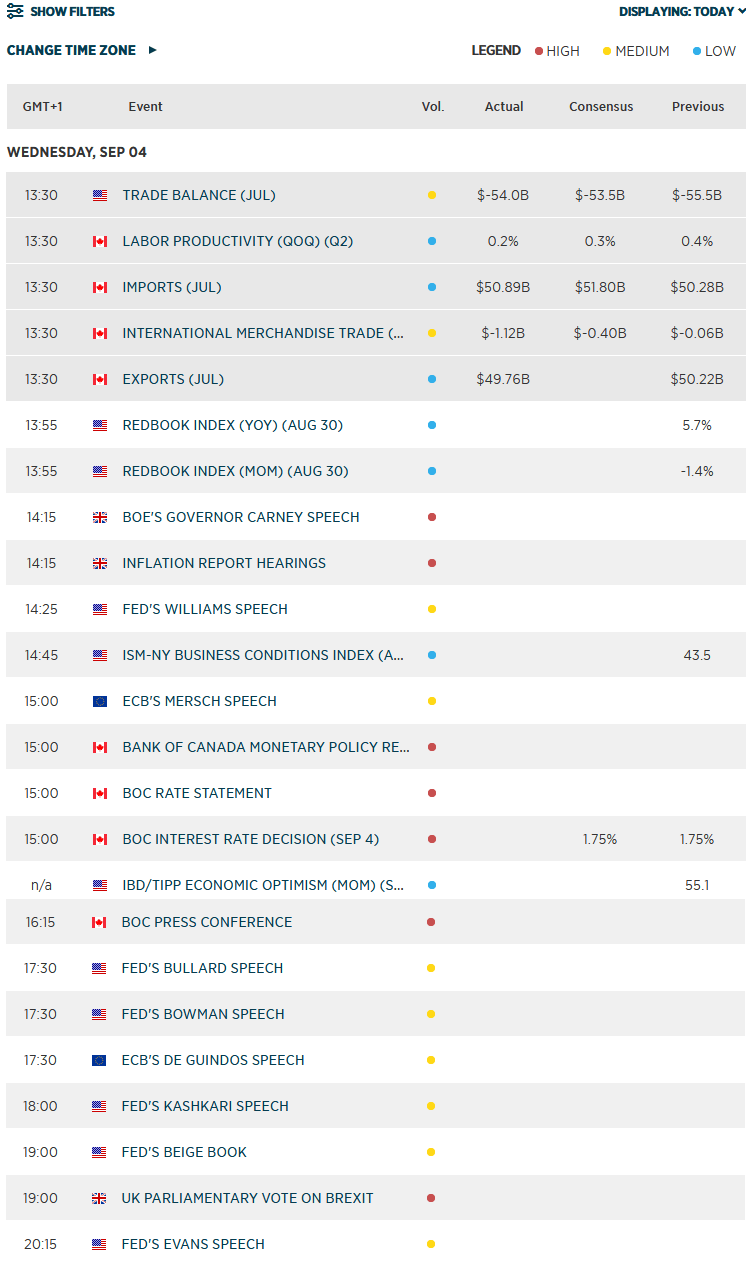
- BOC rate decision is today’s main event from North America, at 15:00 BST.
- Stocks have risen sharply so far in the day. Hong Kong chief executive Carrie Lam has said the controversial extradition bill has been fully withdrawn – this sent the Hang Seng sharply higher overnight, indirectly supporting the European markets and US index futures. We also had China’s services PMI come in ahead of expectations at 52.1 overnight. Along with the other markets, the UK’s FTSE 100 also rose – but less so because of the sharp rally in the pound.
- Crude oil also found support from the positive tone towards risk assets, even if the fundamental backdrop remains somewhat bearish for the black stuff.
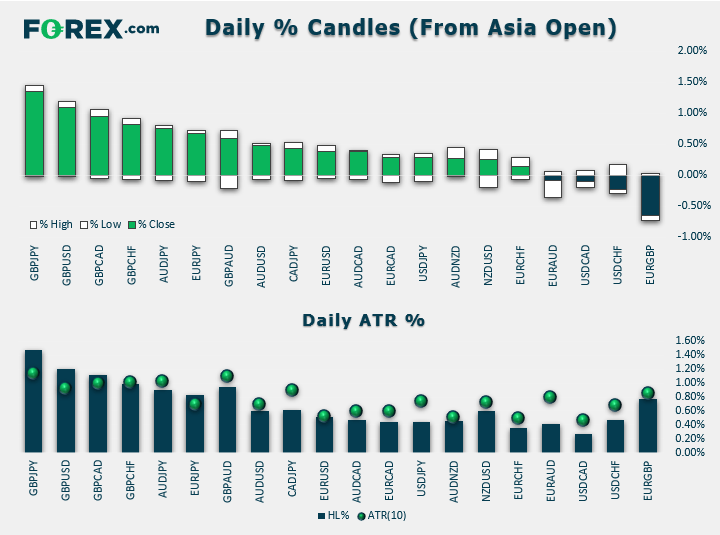
- GBP has been the standout winner in what has been a day of above-normal range in nearly all pound crosses. Could we see some retracement on profit-taking during the NY session? USD has extended its falls for the second day following that poor manufacturing PMI report from yesterday.
- UK services sector PMI was expected to ease to 51.0 from 51.4 but came in at 50.6 – not that it mattered much for the pound, which continued to squeeze the shorts after the dip to sub $1.20 proved to be short-lived yesterday as UK parament seized control of the Commons in a bid to stop no-deal Brexit. MPs will vote later today on a bill that would force Boris Johnson to ask EU for Brexit delay. If the bill passes, the PM has said will call a general election. Today’s services PMI miss means we now have a hat-trick of bad news after both manufacturing and construction PMIs fell deeper into contraction territory earlier this week. Earlier, Eurozone final services PMI was revised a tick higher to 53.5 from 53.4 thanks to upgrades for Germany and Spain. Eurozone retail sales came in -0.6% m/m as expected.
- BOC rate decision is today’s main event from North America, at 15:00 BST.
- Stocks have risen sharply so far in the day. Hong Kong chief executive Carrie Lam has said the controversial extradition bill has been fully withdrawn – this sent the Hang Seng sharply higher overnight, indirectly supporting the European markets and US index futures. We also had China’s services PMI come in ahead of expectations at 52.1 overnight. Along with the other markets, the UK’s FTSE 100 also rose – but less so because of the sharp rally in the pound.
- Crude oil also found support from the positive tone towards risk assets, even if the fundamental backdrop remains somewhat bearish for the black stuff.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Australian Dollar Technical Outlook: AUD/USD Breakdown Threatens Deeper Correction 9 23 2026
AUD/USD remains under pressure after breaking key trend support, with the latest decline putting the focus on the next major downside pivot.
USD/JPY forecast: US dollar strengths amid hawkish Fed despite recent oil weakness
The US dollar has extended its gains this morning, even if oil prices finished lower for the fifth consecutive day yesterday. Oil prices have bounced back in this first half of today’s session, causing a bit of pressure on currencies that rely on energy imports such as the euro, pound, Swiss franc, and Japanese yen. But it was the dollar that was exerting the most pressure, amid hawkish FedSpeak. Meanwhile, European indices and precious metals were also under a bit of pressure amid the strength of the dollar.


EUR/AUD, GBP/AUD Outlook: Rates, risk and metals reinforce bearish technical case
EUR/AUD and GBP/AUD are coiling near support, with recent correlations suggesting the Aussie’s strength is being driven more by rates, risk and metals than energy.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.