



Market Brief stronger Eurozone data lifts euro
A summary of news and snapshot of moves ahead of the US session.
Share this:

- At 13:30 GMT, the euro and yen were the strongest while North American dollars brought up the rear. Gold edged higher, stocks were mixed and bond yields fell back a little after yesterday’s gains. It has been a quieter session thus far, hopefully ahead of a bit more volatile US session later.

View our guide on how to interpret the FX Dashboard
- EUR managed to rebound a tad after yesterday’s sell-off on the back of better than expected data. Eurozone Final Services PMIs were revised higher with Italian flash PMI coming in one whole point better than expected. Meanwhile German factory orders rose 1.3% against 0.1% expected, while Eurozone retail sales was in line with a gain of 0.1% month-over-month.
- NZD recovered after initially dropping in Asian session when it was hurt by weak New Zealand employment data, which boosted expectations for RBNZ to cut rates again.
- Gold was somewhat desperately trying to cling onto key support around $1480, finding mild support thanks to the stock market rally pausing for a breather. The precious metal fell sharply on Tuesday, partly because we saw further unexpected improvement in economic data and thawing of US-China trade frictions, both helping to underpin the buck and undermine haven assets. But the buck and yields were both a touch weaker, allowing the metal to rebound.
- JPY was showing strength after being one of the weakest currencies over the previous two sessions. It was supported by short-side profit-taking as stocks eased back a tad.

- Stocks: Here are some of today’s main company news, courtesy of colleague Ken Odeluga:
- Marks & Spencer surged almost 8% initially on glimmers of hope in its flagship clothing division. The stock later faded to rise of 2%-4% as firm food sales contrast with weak profit growth and a 2.1% revenue drop.
- Intu Properties - 20% after warning it will probably need to raise fresh equity as the commercial rent downtrend shows no signs of abating.
- U.S.-listed shares of Japan's Softbank point lower after the WeWork investor reported a $6.5bn quarterly loss, its first in 14 years.
- BMW beat Q3 core profit estimates though kept guidance unchanged.
- SocGen +5.6%: Despite a big drop income from equities, strong capital growth proves to be a relief.
- Coty beat on Q1 EPS, shares indicated higher.
- At 13:30 GMT, the euro and yen were the strongest while North American dollars brought up the rear. Gold edged higher, stocks were mixed and bond yields fell back a little after yesterday’s gains. It has been a quieter session thus far, hopefully ahead of a bit more volatile US session later.
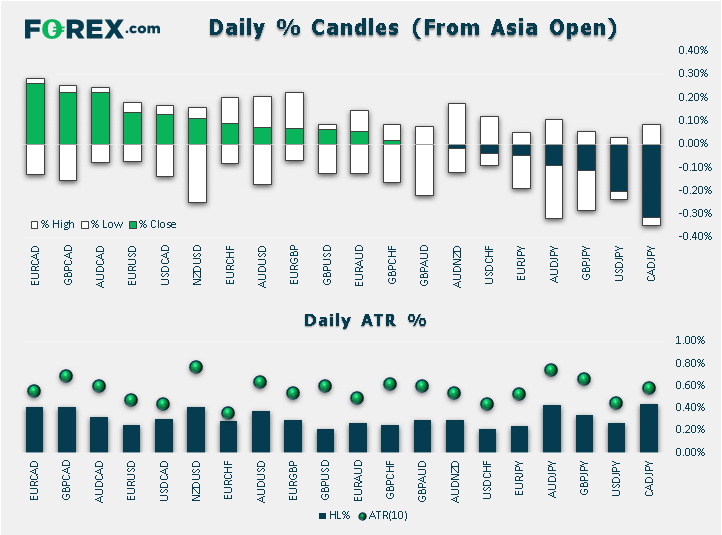
View our guide on how to interpret the FX Dashboard
- EUR managed to rebound a tad after yesterday’s sell-off on the back of better than expected data. Eurozone Final Services PMIs were revised higher with Italian flash PMI coming in one whole point better than expected. Meanwhile German factory orders rose 1.3% against 0.1% expected, while Eurozone retail sales was in line with a gain of 0.1% month-over-month.
- NZD recovered after initially dropping in Asian session when it was hurt by weak New Zealand employment data, which boosted expectations for RBNZ to cut rates again.
- Gold was somewhat desperately trying to cling onto key support around $1480, finding mild support thanks to the stock market rally pausing for a breather. The precious metal fell sharply on Tuesday, partly because we saw further unexpected improvement in economic data and thawing of US-China trade frictions, both helping to underpin the buck and undermine haven assets. But the buck and yields were both a touch weaker, allowing the metal to rebound.
- JPY was showing strength after being one of the weakest currencies over the previous two sessions. It was supported by short-side profit-taking as stocks eased back a tad.
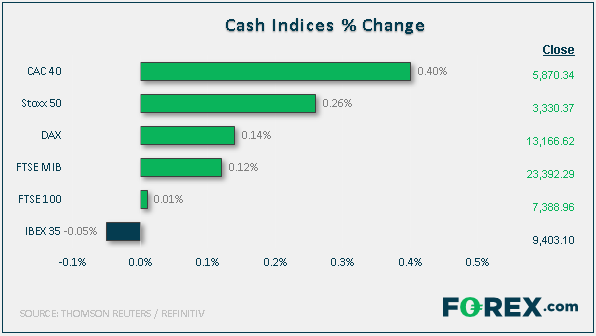
- Stocks: Here are some of today’s main company news, courtesy of colleague Ken Odeluga:
- Marks & Spencer surged almost 8% initially on glimmers of hope in its flagship clothing division. The stock later faded to rise of 2%-4% as firm food sales contrast with weak profit growth and a 2.1% revenue drop.
- Intu Properties - 20% after warning it will probably need to raise fresh equity as the commercial rent downtrend shows no signs of abating.
- U.S.-listed shares of Japan's Softbank point lower after the WeWork investor reported a $6.5bn quarterly loss, its first in 14 years.
- BMW beat Q3 core profit estimates though kept guidance unchanged.
- SocGen +5.6%: Despite a big drop income from equities, strong capital growth proves to be a relief.
- Coty beat on Q1 EPS, shares indicated higher.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.
USD/MXN Forecast: Peso Loses Momentum Ahead of Banxico Decision
Over recent trading sessions, the Mexican peso has started to show signs of losing strength against the U.S. dollar. This can be seen in the performance of USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting the dollar's renewed strength against the peso.

Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.