




Markets brief FOMC expected to cut interest rates
A summary of news and snapshot of moves ahead of the US session.
Share this:

Markets update:
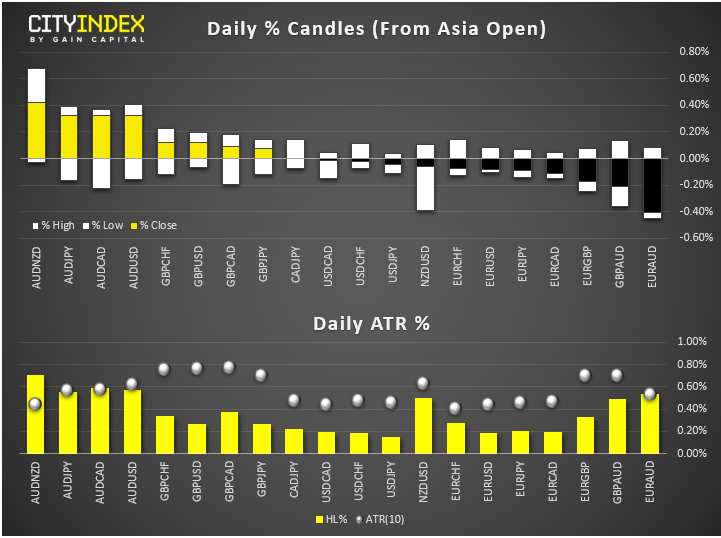
- Ahead of the US session, AUD was the strongest on CPI beat and EUR was among the weakest despite mixed-bag Eurozone data.
- Stocks in Europe still unable to find their feet after yesterday’s sell-off but were coming off their worst levels at the time of this writing.
- Gold was attempting to rise for the fourth day amid renewed weakness for government bond yields, and crude oil was in consolidation mode after yesterday’s rally and ahead of US oil inventories data later on.
- Sentiment remains cagey as investors weigh the impact of today’s positive earnings and mixed economic data against a potential rate cut from the Fed later on. There is growing uncertainty that there will be a breakthrough in US-China trade talks after Trump said the “problem with China [is that] they just don't come through" and "always changes the deal to their benefit."
Data recap
- Eurozone second quarter GDP was in light at +0.2%, a slowdown from +0.4% in Q1. There was good news from Germany for a change: retail sales grew by a solid 3.5% month over month compared to a 0.5% decline expected.
- Eurozone CPI was a tad higher than expected at 1.1% y/y versus 1.0% expected, but down from 1.2% in the previous month. This was not unexpected as German CPI had already come in ahead of expectations the day before. Eurozone core CPI was weaker than anticipated at 0.9%, slowing noticeably from 1.1% previously.
- Overnight
Earnings recap
- Lloyds shares slid 5% after taking a £500m PPI provision, while Next shares jumped 8% after the retailer lifted its sales growth forecast.
- European earnings are also coming in thick and fast now: Airbus beat earnings expectations, while L’Oreal said sales in North American slumped even if overall growth was the best in a decade. Meanwhile the major European banks reporting their results all beat expectations including Credit Suisse, BNP Paribas and BBVA.
- Apple shares rose +4% in afterhours trading last night as revenues topped expectations, although less than half of the group’s sales were generated from its flagship iPhone sales for the first time since 2012. This morning GE reported disappointing results, but shares rose 5% pre-market as the company lifted its EPS forecast.
Coming up
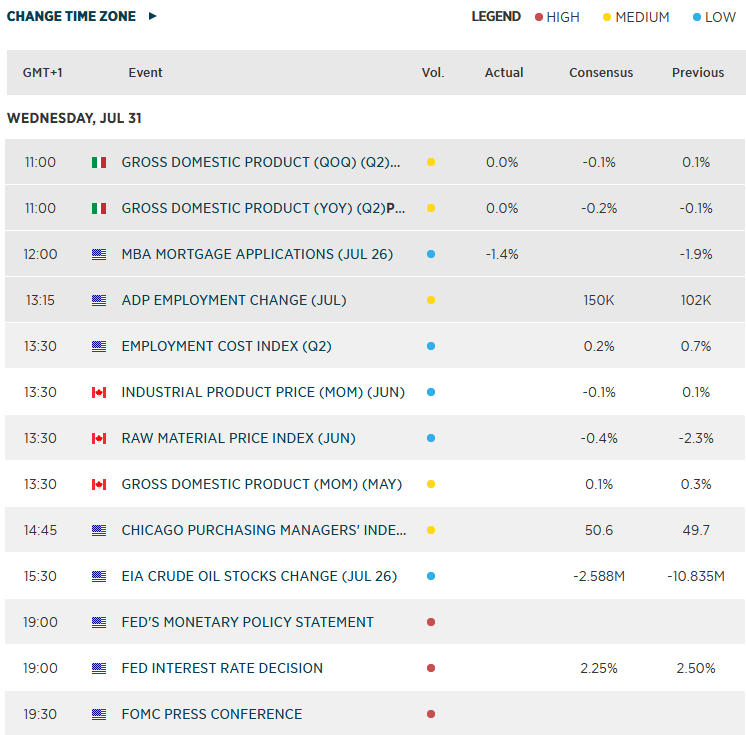
- The focus will now turn to the Federal Reserve’s policy decision, due at 19:00 BST with the press conference half an hour later at 19:30 BST.
- Ahead of this, we will have US ADP private sector payrolls report and oil inventories among a handful of data releases left for the remainder of today’s session:
Markets update:
- Ahead of the US session, AUD was the strongest on CPI beat and EUR was among the weakest despite mixed-bag Eurozone data.
- Stocks in Europe still unable to find their feet after yesterday’s sell-off but were coming off their worst levels at the time of this writing.
- Gold was attempting to rise for the fourth day amid renewed weakness for government bond yields, and crude oil was in consolidation mode after yesterday’s rally and ahead of US oil inventories data later on.
- Sentiment remains cagey as investors weigh the impact of today’s positive earnings and mixed economic data against a potential rate cut from the Fed later on. There is growing uncertainty that there will be a breakthrough in US-China trade talks after Trump said the “problem with China [is that] they just don't come through" and "always changes the deal to their benefit."
Data recap
- Eurozone second quarter GDP was in light at +0.2%, a slowdown from +0.4% in Q1. There was good news from Germany for a change: retail sales grew by a solid 3.5% month over month compared to a 0.5% decline expected.
- Eurozone CPI was a tad higher than expected at 1.1% y/y versus 1.0% expected, but down from 1.2% in the previous month. This was not unexpected as German CPI had already come in ahead of expectations the day before. Eurozone core CPI was weaker than anticipated at 0.9%, slowing noticeably from 1.1% previously.
- Overnight
Earnings recap
- Lloyds shares slid 5% after taking a £500m PPI provision, while Next shares jumped 8% after the retailer lifted its sales growth forecast.
- European earnings are also coming in thick and fast now: Airbus beat earnings expectations, while L’Oreal said sales in North American slumped even if overall growth was the best in a decade. Meanwhile the major European banks reporting their results all beat expectations including Credit Suisse, BNP Paribas and BBVA.
- Apple shares rose +4% in afterhours trading last night as revenues topped expectations, although less than half of the group’s sales were generated from its flagship iPhone sales for the first time since 2012. This morning GE reported disappointing results, but shares rose 5% pre-market as the company lifted its EPS forecast.
Coming up
- The focus will now turn to the Federal Reserve’s policy decision, due at 19:00 BST with the press conference half an hour later at 19:30 BST.
- Ahead of this, we will have US ADP private sector payrolls report and oil inventories among a handful of data releases left for the remainder of today’s session:

Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.


USD/MXN Forecast: Peso Loses Momentum Ahead of Banxico Decision
Over recent trading sessions, the Mexican peso has started to show signs of losing strength against the U.S. dollar. This can be seen in the performance of USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting the dollar's renewed strength against the peso.


Euro Short-term Outlook: EUR/USD Selloff Nears Critical Yearly Support 9 23 2026
Euro has fallen seven of the past nine sessions, with stretched momentum raising the stakes as EUR/USD closes in on a major inflection zone.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.