



Nasdaq 100 forecast: Stocks drop again but downside may be limited
Risk appetite continued to weaken Friday morning as European stocks and US futures resumed their slide after a brief bout of dip-buying faded – the sort of price action we have been accustomed to all week really. Some analysts warn that this year’s artificial-intelligence-led rally has finally come to a halt, while others suggest markets needed to cool down anyway with indices racing to record highs without much pause and new stimulus.
Share this:
Risk appetite continued to weaken Friday morning as European stocks and US futures resumed their slide after a brief bout of dip-buying faded – the sort of price action we have been accustomed to all week really. Some analysts warn that this year’s artificial-intelligence-led rally has finally come to a halt, while others suggest markets needed to cool down anyway with indices racing to record highs without much pause and new stimulus. The renewed weakness follows the sell-off on Thursday, which was led by some of the biggest beneficiaries of the AI-boom. US Treasuries rebounded off their earlier lows, and down went yields, which gave rise to fresh yen buying, causing pairs like the USD/JPY to ease off their earlier highs. Gold held steady amid the risk off tone, continuing to rest waters around the $4000 level, while Bitcoin tested waters just below $100K as it headed for its worst week since March. But will the dip buyers emerge and save the day? The Nasdaq 100 forecast could be hit if support at 25K doesn’t hold today.
Analysis: Why are markets falling?
There are multiple factors at play. For a start, the prolonged US government shutdown is finally weighing on risk appetite, which until recently had been largely ignored. But now that there appears to be further evidence of a cooling Us labour market, this is unsettling investors and prompting a shift towards defensive positioning, with Japanese yen finding some love. Yesterday, Challenger reported more than 153,000 job cuts in the US, concentrated mainly in the tech and warehousing sectors. With the federal data gap still being filled by private reports, these figures continue to drive sharp market reactions. Yesterday’s ADP payrolls report briefly lifted sentiment, but now money markets are pricing in a higher likelihood of a Federal Reserve rate cut in December. Still, equities are not sharing that optimism this time as they fall along with other assets. The message is clear really – rate cut hopes alone aren’t enough when reality sets in. Frankly, the market needed this dose of realism. After months of AI-driven euphoria, traders are being reminded that fundamentals still matter.
When will markets bounce back?
Well, it is tough to say, but don't rule anything out. So far, every short-term dip-buying recovery has stalled this month. Until we see a more decisive action from the bulls, it pays to be cautious. There may need to be a fundamental shift in sentiment which could be triggered for example by a reponing of US government. Either that, or equities will need to weaken more to make them look attractive again for investors. What could also help the market is central banks turn decidedly dovish once more, especially the Fed. Last week, there was a bit of hawkish repricing of US interest rates following Powell’s comments at the FOMC presser. That outweighed optimism over the recent extension of a trade truce between the US and China. But dip-buyers will be lurking as appetite for AI-related stocks remains strong, with earnings also largely being positive this reporting season. So, after a period of easing, I am expecting markets to find their feet again and support the Nasdaq 100 forecast.
Nasdaq 100 forecast: Technical levels to watch
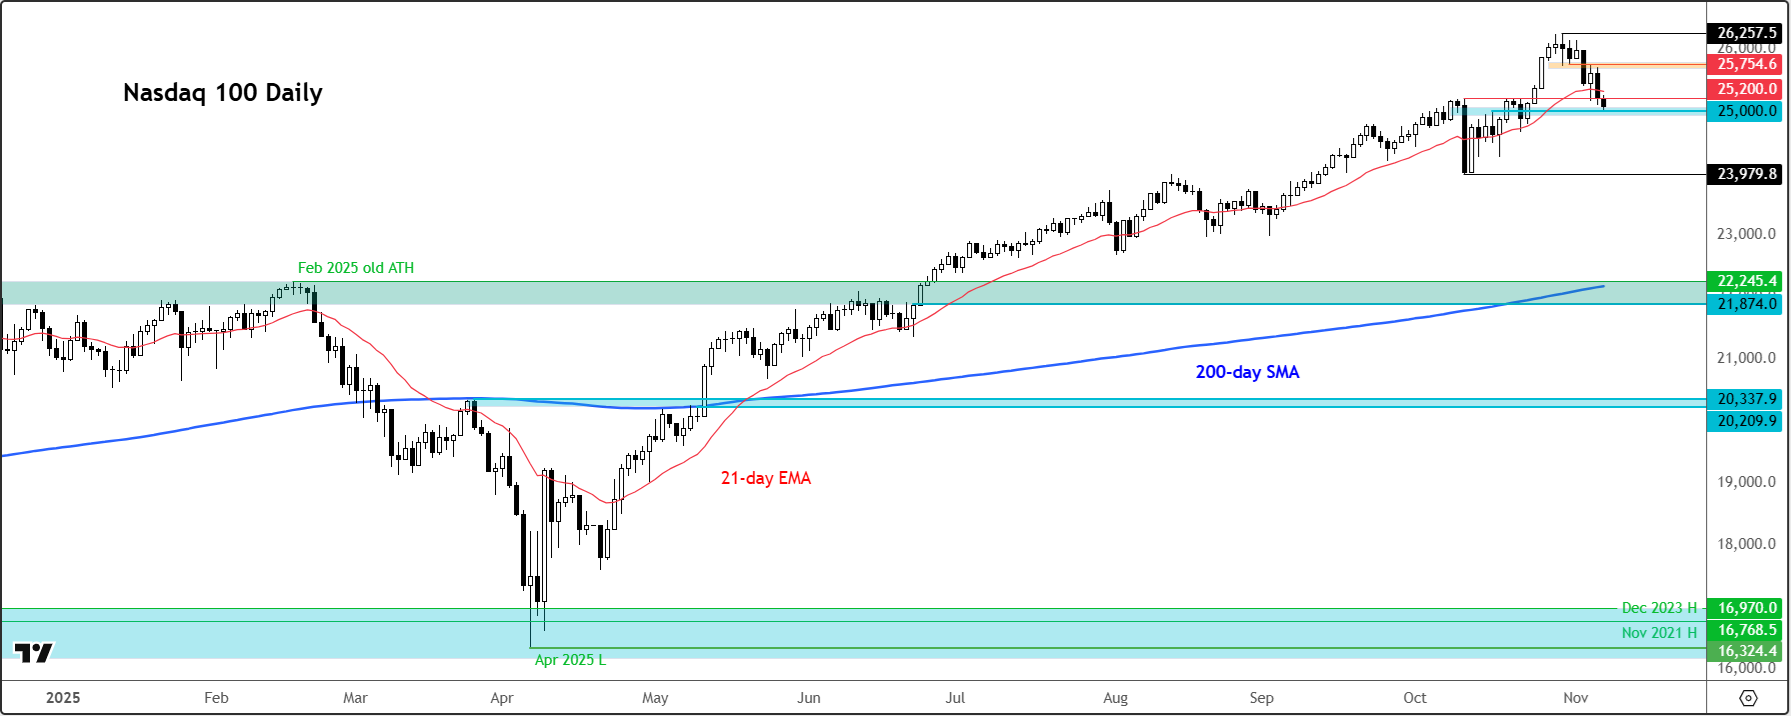
Our US 100 index, which is derived from the Nasdaq 100 futures chart, shows the index is now testing a key support area near 25,000. It is the area from where it took off a couple of weeks ago and so it really needs to hold to maintain a bullish bias. A clean breakdown could pave the way for further technical selling in the days ahead, with 24,500 being the next potential support, followed by 23,980. On the upside, 25,200 is now short-term resistance, followed by 25.500 and then 25,700.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.