



Risk Improves But Can It Last
European markets have opened cautiously higher on the open as investors see a glimmer of hope in Italy’s easing death rates and as oil prices rebound. Can it ladt with US initial jobless claims due later?
Share this:
European markets are pointing to a cautiously higher start on the open as investors see a glimmer of hope in Italy’s easing death rates and as oil prices rebound. However, it is questionable whether the lift in risk sentiment will be last the session, let alone into the weekend.
Italy provides glimmer of hope
Signs are growing that the worst could be over in Italy, the epicentre of Europe’s coronavirus outbreak as the death rate continues to fall and as the number of new cases ease. Yet despite the optimism, the lock down which has brought the spread of the virus under control and simultaneously brought the economy to a grinding halt, will be in place for longer than initially thought. This ultimately means the economy will be paralysed for an extended period of time.
Signs are growing that the worst could be over in Italy, the epicentre of Europe’s coronavirus outbreak as the death rate continues to fall and as the number of new cases ease. Yet despite the optimism, the lock down which has brought the spread of the virus under control and simultaneously brought the economy to a grinding halt, will be in place for longer than initially thought. This ultimately means the economy will be paralysed for an extended period of time.
Oil jumps 10%
A surge in the price of oil is also playing its part in boosting stocks. China’s plans to boost its oil reserves has seen oil soar over 10% in early trade. WTI reached a high of $22.55 overnight and is easing off that level at the start of the European session. Despite today’s announcement $20 remains the clear line in the sand for oil as the global backdrop remains challenging. Whilst today’s news will provide some brief reprieve, the fundamentals for oil remain weak. Heavyweight oil majors are pushing higher in early trade.
A surge in the price of oil is also playing its part in boosting stocks. China’s plans to boost its oil reserves has seen oil soar over 10% in early trade. WTI reached a high of $22.55 overnight and is easing off that level at the start of the European session. Despite today’s announcement $20 remains the clear line in the sand for oil as the global backdrop remains challenging. Whilst today’s news will provide some brief reprieve, the fundamentals for oil remain weak. Heavyweight oil majors are pushing higher in early trade.
US initial jobless claims
Whilst risk sentiment is just about holding up on the open it is questionable whether it will remain the case across the session. US initial jobless claims are set to show another record-breaking number of sign ups and reveal the devastating impact that the coronavirus outbreak in having on the US labour market. The figures come just ahead of tomorrow’s non-farm payrolls; a weak reading today could see risk being whipped off the table with traders reluctant to put risk back on the table until after the weekend.
Whilst risk sentiment is just about holding up on the open it is questionable whether it will remain the case across the session. US initial jobless claims are set to show another record-breaking number of sign ups and reveal the devastating impact that the coronavirus outbreak in having on the US labour market. The figures come just ahead of tomorrow’s non-farm payrolls; a weak reading today could see risk being whipped off the table with traders reluctant to put risk back on the table until after the weekend.
FTSE levels to watch
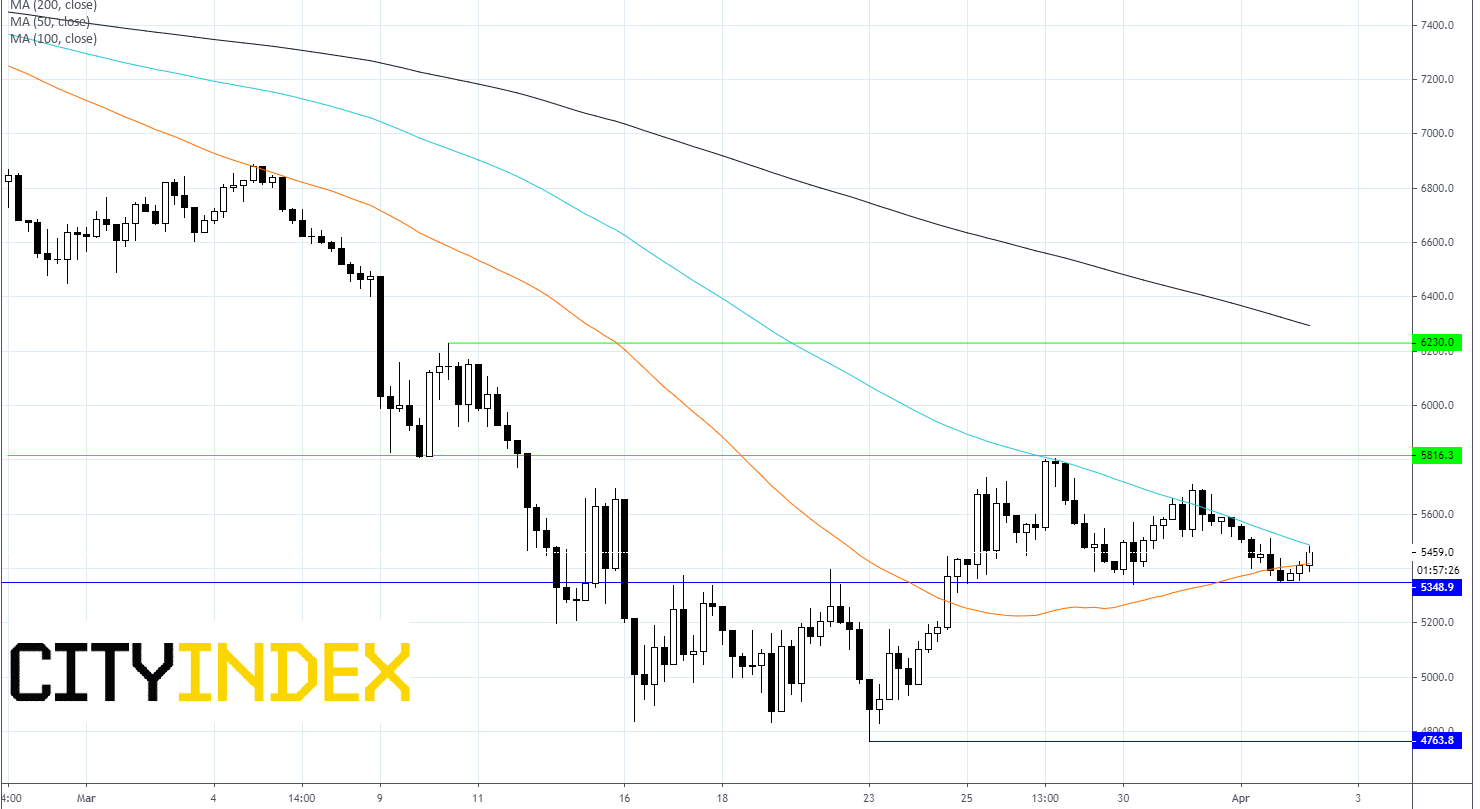
The FTSE has jumped over 2% on the open. Whilst it has pushed over its 50 sma on 4 hour chart, it failed to break through the 100 sma at 5485.
Immediate support can be seen at 5350, a level which has capped losses since 25th March. A breakout below this level could see the FTSE target the round number level of 5200.
Immediate resistance can be seen at 100 sma of 5485. A breakthrough here could see more bulls jump in. A key level to watch would be a break out above 5816.




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
FTSE 100 and GBP/USD forecast: UK data gives BoE March cut a further boost
The FTSE 100 edged higher to close in on last week’s record, as the pound weakened following the release of UK wages and Jobs data that puts a March rate cut firmly on the table, barring any surprises in tomorrow’s inflation report. Unless we see a sharp turnaround in data, I would be expecting another rate cut in June, and possibly more in the summer if inflation risks ease. This should keep the longer term FTSE 100 forecast firmly supported and keep a lid on sterling.

FTSE 100 forecast - Indices weekend outlook | February 16, 2026
With the US out on Monday for Presidents’ Day and China celebrating Spring Festival all week, it makes sense to focus on European markets to start the week off. So the FTSE 100 forecast is in focus for this week’s weekend indices outlook. We have plenty of UK, European and US earnings to look forward to as the week progresses, while key data from the UK and US will make rate cut expectations a key talking point on both sides of the pond.
Indices weekly outlook: FTSE holds steady ahead of UK data after tech volatility
Last week saw the technology sector take a plunge, before dip buyers stepped in on Friday to save the day, helping to fuel a late rally on Wall Street. In Europe, the major indices also came off their earlier lows to close either flat or in the positive. In the week ahead, the global macro calendar is lighter, with US market closed on Tuesday in observance of Veterans Day.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.