


S&P 500 forecast: Hawkish Fed, resilient equities
The Fed was quite hawkish yesterday and we saw what kind of a reaction it triggered in the FX and equity markets. Yet despite those initial falls, index futures have already recovered to around their pre-FOMC levels at the time of writing today. The resilience of the stock market continues to surprise.
Share this:
The Fed was quite hawkish yesterday and we saw what kind of a reaction it triggered in the FX and equity markets. Yet despite those initial falls, index futures have already recovered to around their pre-FOMC levels at the time of writing today. The resilience of the stock market continues to surprise. For now, we still maintain a cautious S&P 500 forecast, amid uncertainty over oil prices.
FOMC was hawkish
On the face of it, there was little ambiguity about the message from yesterday’s meeting. The widely expected 25bp rate increase was accompanied by a dot plot showing a strong consensus for another hike this year. Twelve of the 18 officials see one further increase, while four expect two more. Growth and inflation forecasts were also revised higher, while the unemployment projection was lowered.
Chair Kevin Warsh did not give much away at the press conference, but reiterated the Fed’s commitment to price stability and offered little suggestion that policy is particularly restrictive at current levels. In his words, the Fed had simply reduced a “dose of accommodation”.
Markets are now pricing around 13bp of additional tightening for October and 32bp by December. In other words, one more 25 basis point hike is fully priced in before the end of the year.
So why are equities holding up?
Well, there are plenty of reasons. For one, oil prices have fallen for the second consecutive day. For another, bond yields have edged lower. But even though yields have risen notably in recent weeks, they don’t always go hand in hand with greater pressure on stocks. It is true, that all else being equal, higher yields should, in theory, weigh on equity valuations. But that ignores earnings.
When yields rise, investors demand a higher return from equities as there is clearly an opportunity cost: tying up your capital in stocks that may or may not appreciate in price means you are missing out on the guaranteed nominal returns from interest payments of bonds.
However, if corporate profits continue to grow, then this will counter the above argument. Rising earnings can offset at least some of the pressure from lower valuation multiples. That is essentially what we have seen so far. Investors clearly don’t think we are in a stagflation environment. Will they ultimately be proven right or wrong is another question. For now, as long as earnings are growing that seems to be the most important consideration for stock investors.
But if in the coming months we see a sharp deterioration in economic data, while oil prices remain high, or break even higher, then stagflation concerns will resurface. In that environment, equity markets could suffer as valuations come under pressure while earnings expectations also deteriorate.
It is important, though, that oil prices ease back down soon or at worst don’t rise much further. US consumers could soon feel the pressure. Higher gas prices clearly squeeze household budgets, and the longer they remain elevated, the more significant that squeeze becomes. But so far, apparently the pressure has not been sufficient enough to derail corporate earnings or push the broader economy into contraction.
Technical S&P 500 forecast and levels to watch
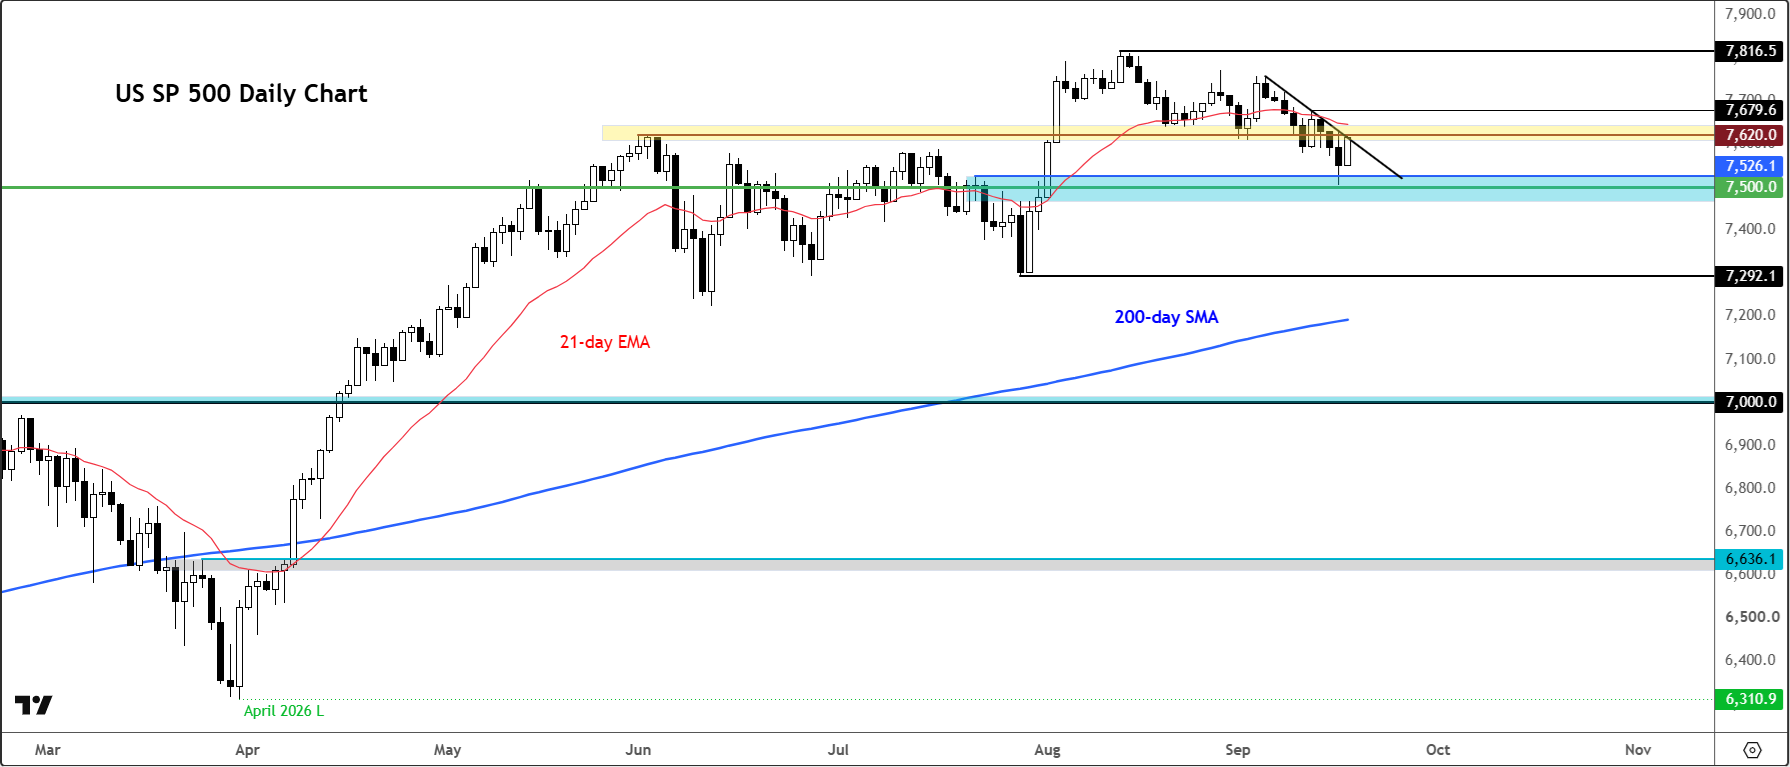
We had previously been calling for a drop to the key 7500 area on our US SP 500 chart, which is derived from the underlying S&P 500 futures. We pretty much got there yesterday in the aftermath of the Fed decision, before bouncing nicely from there. This is where the index previously broke out from back in early August. Now, the questions is do we continue heading higher from here or will the selling resume.
Well, the index is now testing the key 7620/40 area, which is where a short-term bear trend meets the previous horizontal resistance and the 21-day exponential average. If the index closes above this pivotal area, then all bearish bets will be off in the near-term outlook – particularly if we then get a local higher high above 7680. In that case, we could then see follow-up technical buying towards a new all-time high.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY forecast: US dollar strengths amid hawkish Fed despite recent oil weakness
The US dollar has extended its gains this morning, even if oil prices finished lower for the fifth consecutive day yesterday. Oil prices have bounced back in this first half of today’s session, causing a bit of pressure on currencies that rely on energy imports such as the euro, pound, Swiss franc, and Japanese yen. But it was the dollar that was exerting the most pressure, amid hawkish FedSpeak. Meanwhile, European indices and precious metals were also under a bit of pressure amid the strength of the dollar.

EUR/AUD, GBP/AUD Outlook: Rates, risk and metals reinforce bearish technical case
EUR/AUD and GBP/AUD are coiling near support, with recent correlations suggesting the Aussie’s strength is being driven more by rates, risk and metals than energy.

British Pound Short-term Outlook: GBP/USD Selloff Breaks June Uptrend 9 22 2026
Sterling has slipped below its 200-day moving average as downside momentum carries GBP/USD toward another major technical support zone.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.