



S&P 500 Forecast: SPX rises modestly lower ahead of key catalyst week
U.S. stocks are under pressure at the start of the week, extending last week's losses, with technology stocks leading the decline. Investors are becoming more cautious ahead of a busy week featuring Nvidia earnings, core PCE inflation and the Federal Reserve's annual Jackson Hole symposium.
Share this:
US futures
Dow futures -0.15%, S&P futures -0.2% & Nasdaq futures -0.65%
European futures
FTSE -0.05%, DAX -0.15%
- US stocks fall after last week’s decline
- Nvidia earnings, core PCE inflation and Fed Warsh’s speech in focus
- US Treasury Secretary Scott Bessent speaks later today on Iran sanctions
- Oil slips after 5% rise last week
U.S. Stocks Under Pressure Ahead of Nvidia and Jackson Hole
U.S. stocks are under pressure at the start of the week, extending last week's losses, with technology stocks leading the decline. Investors are becoming more cautious ahead of a busy week featuring Nvidia earnings, core PCE inflation and the Federal Reserve's annual Jackson Hole symposium.
The Nasdaq fell 2% last week, while the Dow Jones lost 0.8%. Rising bond yields were a key source of pressure, with the 30-year Treasury yield reaching a 19-year high before Treasury Secretary Scott Bessent stepped in with measures to support the long-end of the bond market.
That relief has proved temporary, leaving investors focused on whether yields can remain contained.
This week's main macro event is July core PCE, the Fed's preferred measure of inflation. The bigger event could be Fed Chair Kevin Warsh's speech at Jackson Hole on Friday.
Warsh has generally provided limited forward guidance, meaning investors shouldn't necessarily expect a clear signal on September rates. He could instead use the speech to outline his broader policy priorities and his approach to the Fed's new regime.
That uncertainty matters because markets remain relatively divided over the next move in rates.
Attention will also remain on the Middle East, with Treasury Secretary Scott Bessent due to outline further sanctions on Iran later today. Any measures that threaten oil supply could push crude prices higher and revive inflation concerns.
The key market question this week is whether higher oil prices and renewed inflation pressure are strong enough to push yields higher again — or whether softer inflation and a cautious Warsh can keep the recent easing in financial conditions intact.
Corporate Movers
Alibaba is falling 2% after announcing plans to issue $10.2 billion of new shares to non-U.S. investors. The company said the proceeds will be used to fund AI projects and infrastructure.
Chipmakers remain under pressure after falling more than 5% last week. The iShares Semiconductor ETF is down almost 2%, while memory stocks are also lower, with SanDisk falling 5% and Micron down 3.5%.
Crypto-related stocks will also be in focus after Bitcoin rallied more than 20% last week. Coinbase gained more than 20% during the rally.
S&P 500 Forecast – Technical Analysis
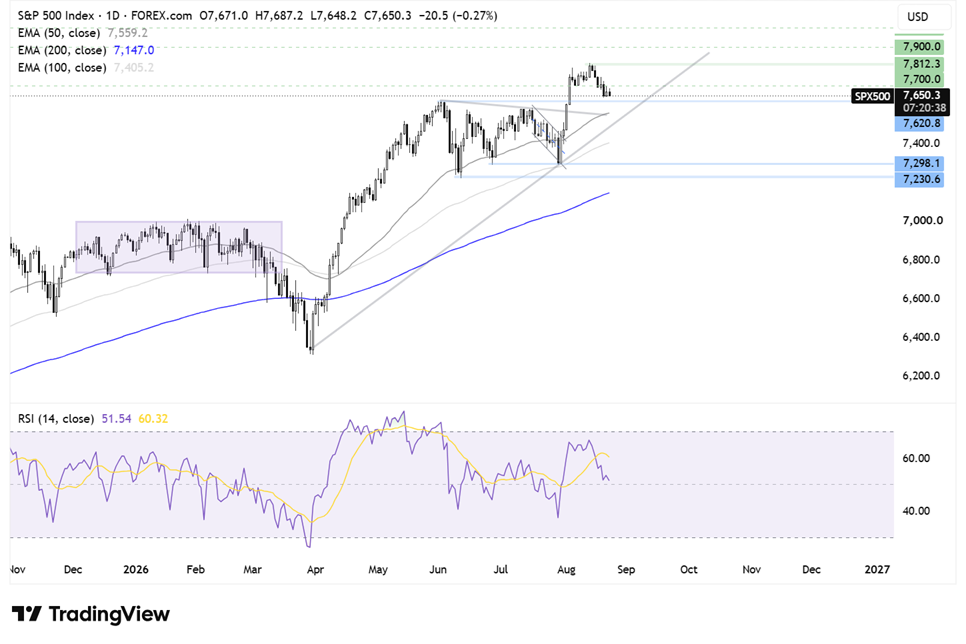
The S&P 500 remains above its rising trend line and the 50, 100 and 200 EMAs, keeping the broader trend constructive.
The index ran into resistance at the record high of 7,810 before falling back below 7,700. Despite the pullback, the broader uptrend remains intact.
Immediate support is at 7,620, the June 26 high, followed by 7,560, where the falling trend line and 50 EMA converge.
A break below this area would weaken the near-term outlook, although it would take a move below 7,300 to create a lower low and change the broader structure.
On the upside, buyers will look to reclaim 7,700 and break above 7,810 to create a fresh record high, opening the door to 7,900 and 8,000.
FX Markets – Dollar Firms, EUR/USD Holds Above 1.1650
The U.S. dollar is edging higher on safe-haven demand ahead of Treasury Secretary Scott Bessent's comments on Iran, although the upside is being limited by falling Treasury yields.
EUR/USD is holding above 1.1650, close to a three-month high, supported by expectations that the ECB could raise rates in September as elevated oil prices keep inflationary pressure high.
GBP/USD is edging higher for a fourth consecutive session, helped by a softer dollar. With the UK economic calendar relatively quiet this week, the pound's next major move is likely to depend more on the dollar and broader risk sentiment.
Oil falls ahead of Bessent’s speech on Iran
Oil prices are holding near recent highs after gaining around 5% last week as hopes for a diplomatic solution in the Middle East faded and traffic through the Strait of Hormuz remained severely restricted.
The market is now waiting for Scott Bessent to announce further sanctions on Iran. Tougher measures could put additional pressure on Iranian oil exports and tighten an already constrained market.
However, Brent remains around $90 a barrel rather than the $120-$150 levels seen in some more extreme supply scenarios, suggesting that some oil is still making its way through the Strait of Hormuz.
Morgan Stanley has raised its Brent forecast to $100.



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

US Core PCE Preview: Stale or Significant for the Fed
Core PCE inflation takes center stage Wednesday, with traders watching for signs of renewed price pressure and clues on whether the Fed could hike again in October.


Nasdaq 100 Forecast: NDX rises as oil eases and tech gains
U.S. stocks are heading higher on Tuesday, helped by a pullback in oil prices and after details about Anthropic's IPO boosted sentiment towards tech stocks.

EUR/USD, USD/JPY Outlook: Oil, yields and an FX identity crisis
Crude oil is setting the tone across rates and FX, leaving EUR/USD vulnerable and USD/JPY caught between higher Treasury yields and the growing threat of intervention

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.