




SP500 remains vulnerable to another leg lower
Although this weeks FOMC meeting, provided dovish reinforcement to the Feds new policy framework announced at the Jackson Hole Symposium, it failed to put an end to the more cautious tone evident in the U.S. stock market in September.
Share this:

Overshadowing the Feds renewed commitment to ultra-dovish policy, investors remain cautious due to some of the factors listed below.
- Fading hopes that a 4th stimulus package will be agreed before the November 4th U.S. election
- Brexit negotiations in Europe
- A second wave of the virus in Europe
- Uncertainty around the outcome of the U.S. election
- The Federal Reserve is not due to meet again until after the U.S election.
There is also a concern that the significant improvement in economic data that until now has helped power U.S stocks higher, has stalled and begun to decelerate.
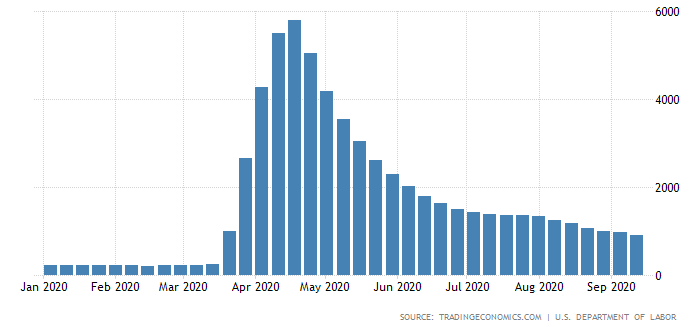
Looking at the chart of the 4 week average of US jobless claims below, it can be observed that after a sharp spike higher in April following the lockdowns, the pace of improvement has noticeably decelerated in August and September.
Seasonally, September is a month that usually provides its fair share of speed bumps, particularly after the expiry of U.S. equity indices which occurs tonight.
Research by US investment bank, Morgan Stanley shows that since 1998, E-mini S&P 500 futures have underperformed over the 5 days following the quarterly expiry. After the September expiry, the effect is more pronounced and exhibits a median 5-day return of -1.22%.
All in all, September will likely be the S&P500’s first negative month since it began its 65% rally in late March. The current downdraught is viewed as being part of a corrective pullback, rather than a reversal lower.
A break of short term support 3290/80 will allow the correction to deepen initially towards 3230/00 and then towards the wave equality target at 3128 and the 200-day ma 3100 area.
From the 3128/3100 support area, we will look for signs of stabilisation and for the uptrend to resume.
Source Tradingview. The figures stated areas of the 18th of September 2020. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?


USD/JPY unwind accelerates as GPIF headlines spark yen buying
Japanese assets are rallying after the government floated the prospect of the GPIF investing more heavily at home. While the proposal could have significant implications for global capital flows, it does not yet change the broader forces driving Japanese bond yields and USD/JPY.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.