



Traders hedge the Nasdaq’s rally during a typically volatile month
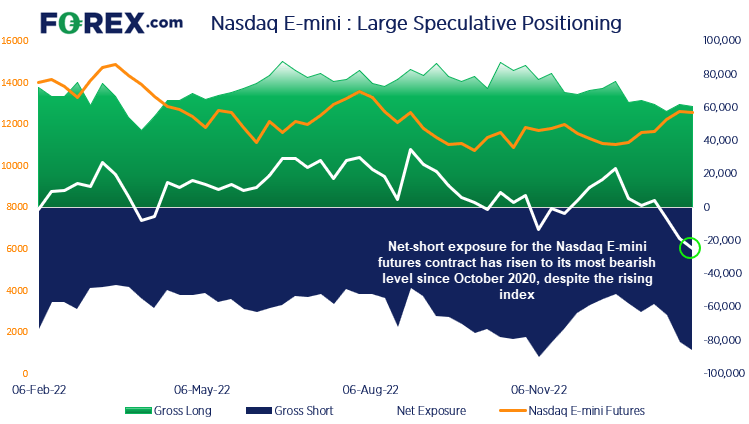
We noted that futures traders are increasingly net-short the Nasdaq, and that February has been the most volatile months for the index over the past five years.
Share this:

Traders increase bearish exposure to the Nasdaq whilst prices rise
It’s been a great start to the year for the Nasdaq 100, which has risen over 14% so far and has outperformed the Dow Jones and S&P 500. Yet after such strong moves, there comes a point where mean reversion must surely kick in. And looking at the market positioning of large speculators, they’re either erring on the side of caution or betting that the index will fall over.
The most recent COT report (commitment of traders) shows that net-short exposure for the Nasdaq 100 E-mini futures contract is at its most bearish level since October 2020. This means the market has to fall to justify the net-short exposure, otherwise a break higher could trigger some short-covering and add fuel to a bullish fire.

Seasonality has favoured bears in February, over the past thirty years
We like to see seasonality on a market as it can sometimes provide a tendency for prices to move one way or another. So it is interesting to note that the Nasdaq has averaged negative returns in February over the past 30-years.
- The Nasdaq 100 has posted a negative average return of -0.28% in February over the past 30 years
- It has also closed lower 55.2% of the time.
- The average winning month has been 6.05%
- The average negative month has been -5.4%
However, more recent years this seasonal tendency has been less reliable, with a positive average return over the past 10 and 15 years yet a negative avg, return over the past five. So whilst this muddies the water for seasonally-generated bias for February we have noted something of interest for potential volatility.
February has been the most volatile month (on average) over the past five years
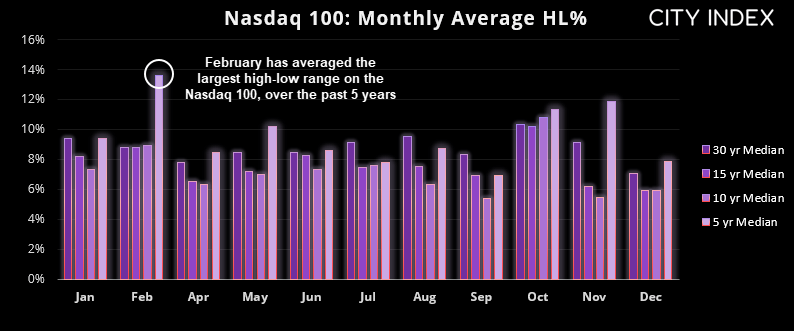
Over the past five years, the high-to-low range (HLR) of the Nasdaq’s monthly candle has been 13.6% - and the most volatile month of the year. Yet the prior 10, 15 and 30-years averaged a high-to-low month around 8.8%. Does this mean we’re in for another volatile month?
So far this month, the Nasdaq has produced a HLR of 3.25%, which is just under a quarter for February’s 5-year average. We’ve had six trading days in Feb so far and 14 to go, which leaves over half of the month left to post a strong move in either direction. Of course, a key driver for market sentiment at the moment is being derived from key US economic data and Fed members speaking, as traders try to decipher if we really will see interest rates ‘higher for longer’ (bearish for stocks), or whether the Fed will cut sooner than later (bullish for stocks).
US inflation is a key data point next week for global markets
The main event next week is the US inflation report at 00:30 AEDT on Wednesday morning (Tuesday in the US) and it can easily turn the dial for Fed expectation. A soft print likely lowers the Fed fun futures curve, weighs on the US dollar and send stocks higher. However, the more volatility reaction may come from a hotter-than-expected inflation report, as it is the last thing markets want to hears. And that could topple indices further from their YTD highs, drag gold with it and propel the US dollar higher.
Nasdaq 100 daily chart:
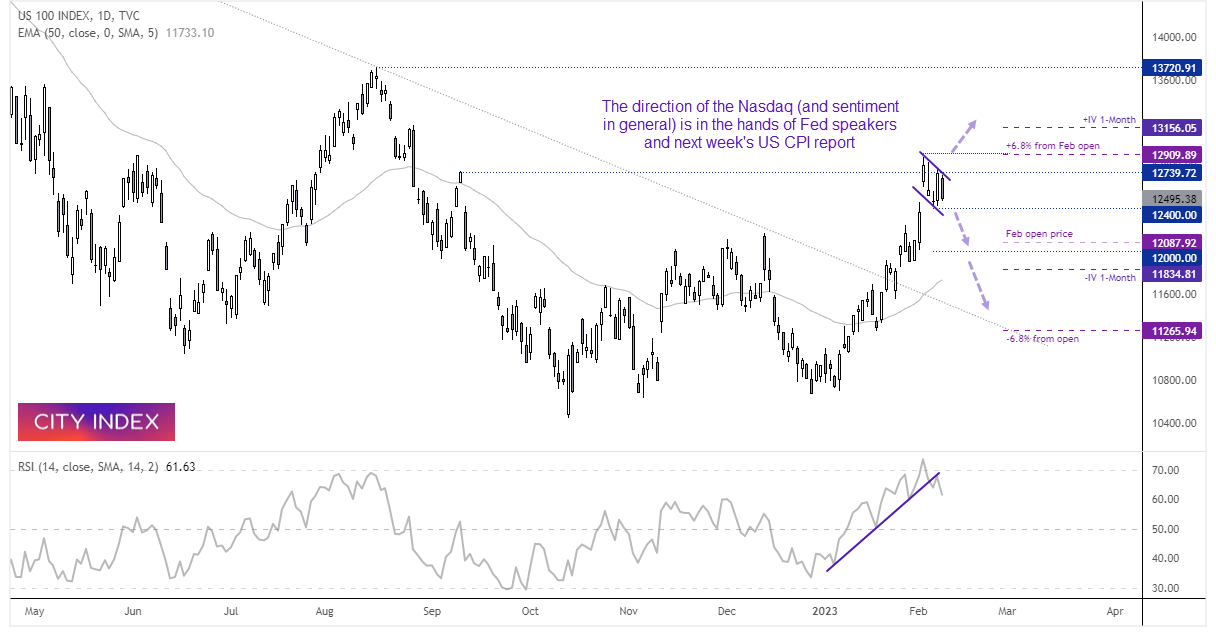
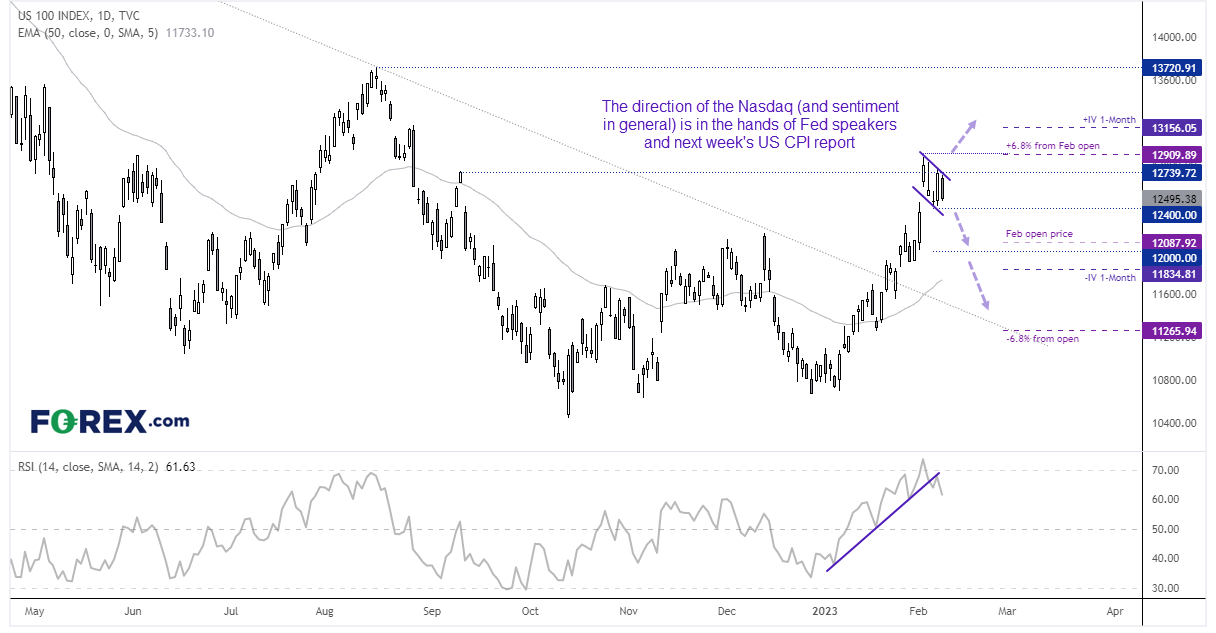
The Nasdaq briefly traded above the September high before pulling back. Momentum has been strong into the current highs with little in the way of a pullback (which a hot CPI report would likely trigger, although RSI (14) recently entered the overbought zone and has since pulled back with prices.
Bearish scenario:
A daily close or break below 12400 suggests a correction is underway, with 12,000 being a viable target due to its round-number status, and it is also near the monthly open price. But if momentum does turn lower and the Fed become increasingly hawkish, note that -6.8% from Feb’s open (half of February’s HLR) is all the way down at 11,265, although the 1-month implied volatility is currently around 11,834.
Bullish scenario:
If any downside break lacks bearish legs, bulls could seek low volatility dips above 12000 – 12,100 and anticipated a break to news highs. Alternatively bulls could wait for a break above the cycle high to assume bullish continuation. And of we project the full HLR average of 13.6% from February’s open, the upper bound sits above 16,000.
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum

S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.


Nasdaq Breakout Potential into Q4 for Melt Up Scenarios
The headlines seem negative in almost any place that you look, with surging Treasury yields and frothy AI valuations getting more and more attention. But, if it’s so bad, why hasn’t the Nasdaq melted down yet, even as the Fed has started hiking rates?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.