



Turnaround Tuesday As Stimulus Comes Into Focus
Turnaround Tuesday or dead cat bounce? It depends on the global response.
Share this:
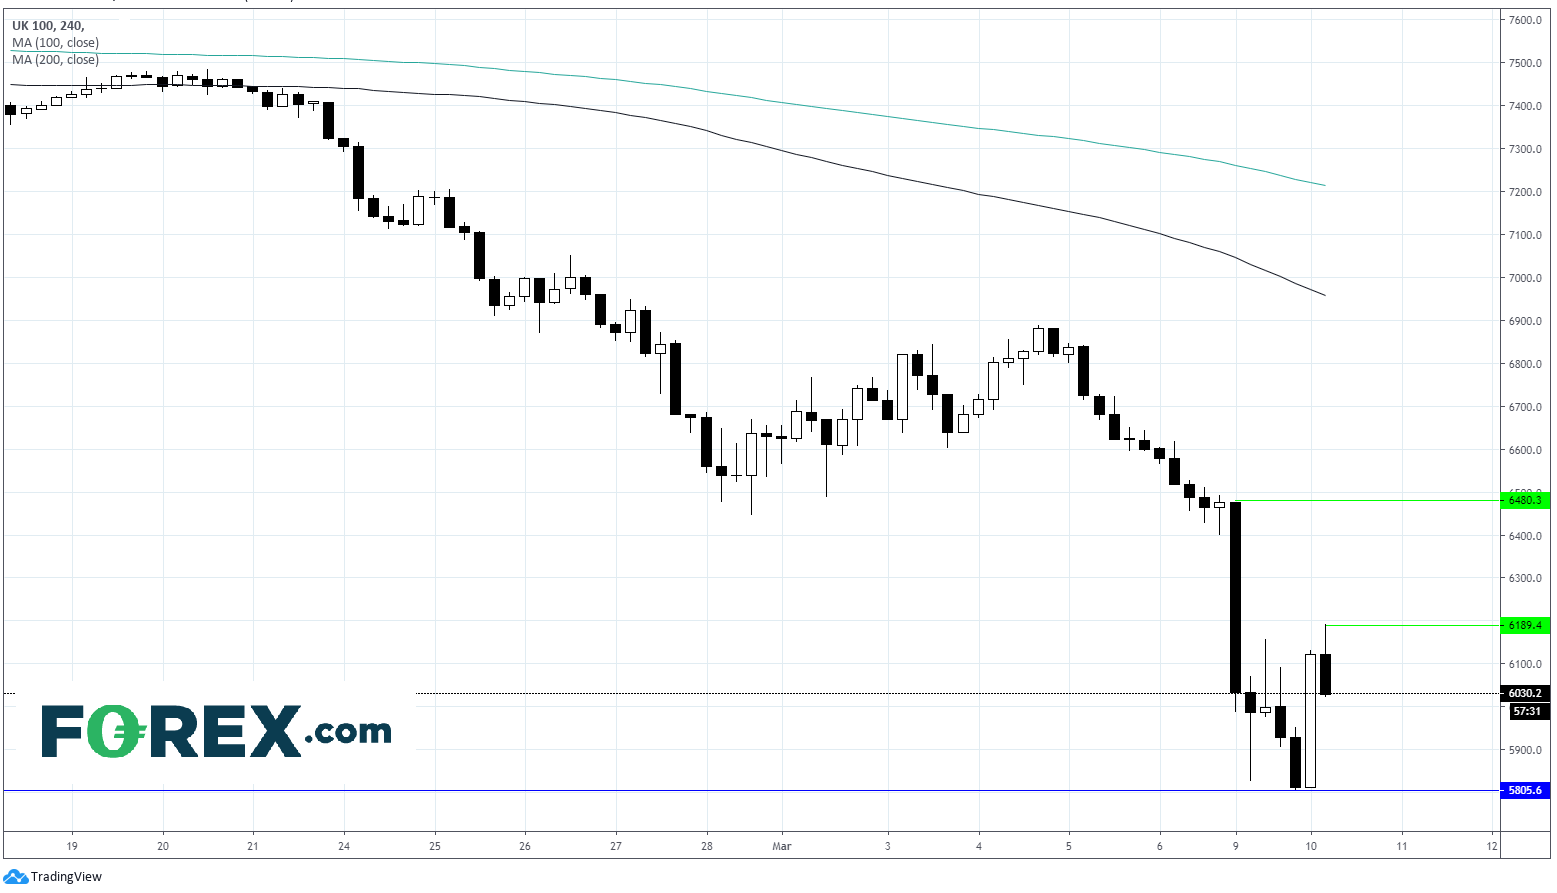
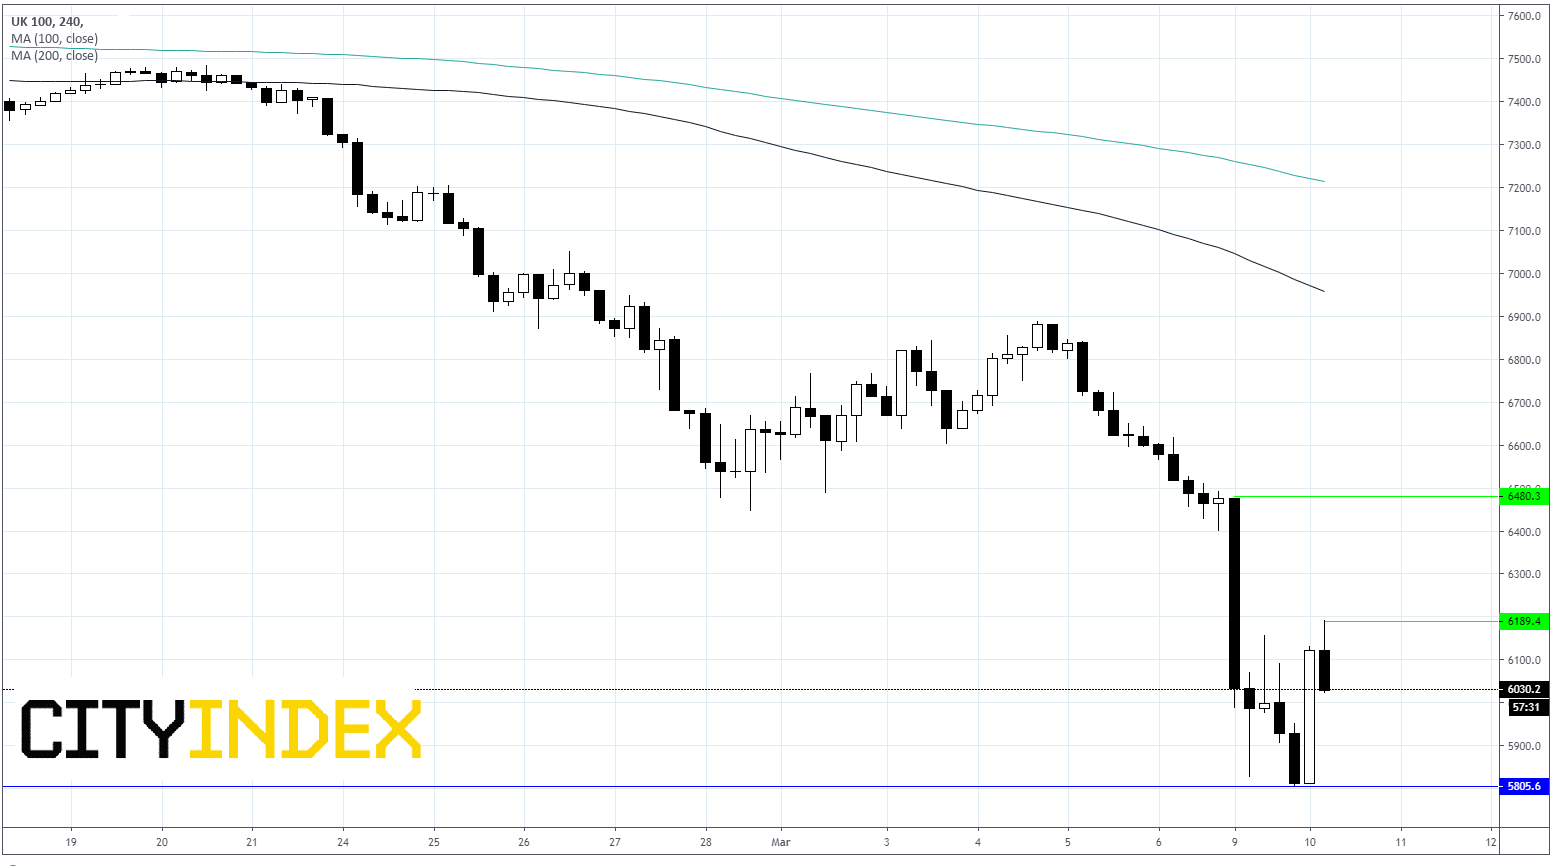
The markets are stabilising after the biggest rout since the financial crisis on Monday. US futures are on the rise, US bond yields are picking up, Asian markets traded higher overnight, and crude has jumped 7% as it recovers from losses of 30% at its worst in the previous session.
Reasons why the market is rebounding?
In the cold light of day, yesterday’s frenzied selling looks very overdone. Today the market appears to be gaining some perspective following a sell off which saw the FTSE and the S&P briefly move into bear market territory. The million-dollar question is whether this is a dead cat bounce or the start of a more meaningful recovery?
In the cold light of day, yesterday’s frenzied selling looks very overdone. Today the market appears to be gaining some perspective following a sell off which saw the FTSE and the S&P briefly move into bear market territory. The million-dollar question is whether this is a dead cat bounce or the start of a more meaningful recovery?
A Temporary Issue
Wuhan, the epicentre to the deadly outbreak is opening its borders once again after a symbolic visit from President Xi. This serves as a reminder to the markets that coronavirus is a temporary issue. Furthermore, China only had 43 new cases yesterday, like the UK. However, this is significantly down from the 3000 new daily cases at the height of the outbreak. So even as Italy goes into full lock down mode, there is light at the end of the tunnel and a V shaped recover can’t be completely written off.
Wuhan, the epicentre to the deadly outbreak is opening its borders once again after a symbolic visit from President Xi. This serves as a reminder to the markets that coronavirus is a temporary issue. Furthermore, China only had 43 new cases yesterday, like the UK. However, this is significantly down from the 3000 new daily cases at the height of the outbreak. So even as Italy goes into full lock down mode, there is light at the end of the tunnel and a V shaped recover can’t be completely written off.
Economic support
An announcement from President Trump that he will ask Congress for economic relief for workers has also helped lift sentiment. A cut from the Fed combined with economic support from Washington is not the same as the Fed standing alone. US futures are on the rise, US treasury yields are rebounding from the record low and the battered US dollar staging a comeback.
An announcement from President Trump that he will ask Congress for economic relief for workers has also helped lift sentiment. A cut from the Fed combined with economic support from Washington is not the same as the Fed standing alone. US futures are on the rise, US treasury yields are rebounding from the record low and the battered US dollar staging a comeback.
Markets are clear that they want to see serious stimulus efforts to stave off the collapse in the financial markets and a global recession.
The UK Budget tomorrow and Thursday’s ECB meeting will be in focus and could help the market decide whether the actions being taken are sufficient to stem the market fallout and recession fears
The UK Budget tomorrow and Thursday’s ECB meeting will be in focus and could help the market decide whether the actions being taken are sufficient to stem the market fallout and recession fears
What Next?
It certainly feels too early to call the bottom of this selloff. However, the market is giving signals that with the right response, a combined effort from central banks and governments this may not necessarily be the start of a bear market run.
The markets are stabilising after the biggest rout since the financial crisis on Monday. US futures are on the rise, US bond yields are picking up, Asian markets traded higher overnight, and crude has jumped 7% as it recovers from losses of 30% at its worst in the previous session.
Reasons why the market is rebounding?
In the cold light of day, yesterday’s frenzied selling looks very overdone. Today the market appears to be gaining some perspective following a sell off which saw the FTSE and the S&P briefly move into bear market territory. The million-dollar question is whether this is a dead cat bounce or the start of a more meaningful recovery?
In the cold light of day, yesterday’s frenzied selling looks very overdone. Today the market appears to be gaining some perspective following a sell off which saw the FTSE and the S&P briefly move into bear market territory. The million-dollar question is whether this is a dead cat bounce or the start of a more meaningful recovery?
A Temporary Issue
Wuhan, the epicentre to the deadly outbreak is opening its borders once again after a symbolic visit from President Xi. This serves as a reminder to the markets that coronavirus is a temporary issue. Furthermore, China only had 43 new cases yesterday, like the UK. However, this is significantly down from the 3000 new daily cases at the height of the outbreak. So even as Italy goes into full lock down mode, there is light at the end of the tunnel and a V shaped recover can’t be completely written off.
Wuhan, the epicentre to the deadly outbreak is opening its borders once again after a symbolic visit from President Xi. This serves as a reminder to the markets that coronavirus is a temporary issue. Furthermore, China only had 43 new cases yesterday, like the UK. However, this is significantly down from the 3000 new daily cases at the height of the outbreak. So even as Italy goes into full lock down mode, there is light at the end of the tunnel and a V shaped recover can’t be completely written off.
Economic support
An announcement from President Trump that he will ask Congress for economic relief for workers has also helped lift sentiment. A cut from the Fed combined with economic support from Washington is not the same as the Fed standing alone. US futures are on the rise, US treasury yields are rebounding from the record low and the battered US dollar staging a comeback.
An announcement from President Trump that he will ask Congress for economic relief for workers has also helped lift sentiment. A cut from the Fed combined with economic support from Washington is not the same as the Fed standing alone. US futures are on the rise, US treasury yields are rebounding from the record low and the battered US dollar staging a comeback.
Markets are clear that they want to see serious stimulus efforts to stave off the collapse in the financial markets and a global recession.
The UK Budget tomorrow and Thursday’s ECB meeting will be in focus and could help the market decide whether the actions being taken are sufficient to stem the market fallout and recession fears
The UK Budget tomorrow and Thursday’s ECB meeting will be in focus and could help the market decide whether the actions being taken are sufficient to stem the market fallout and recession fears
What Next?
It certainly feels too early to call the bottom of this selloff. However, the market is giving signals that with the right response, a combined effort from central banks and governments this may not necessarily be the start of a bear market run.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
FTSE 100 and GBP/USD forecast: UK data gives BoE March cut a further boost
The FTSE 100 edged higher to close in on last week’s record, as the pound weakened following the release of UK wages and Jobs data that puts a March rate cut firmly on the table, barring any surprises in tomorrow’s inflation report. Unless we see a sharp turnaround in data, I would be expecting another rate cut in June, and possibly more in the summer if inflation risks ease. This should keep the longer term FTSE 100 forecast firmly supported and keep a lid on sterling.
FTSE 100 forecast - Indices weekend outlook | February 16, 2026
With the US out on Monday for Presidents’ Day and China celebrating Spring Festival all week, it makes sense to focus on European markets to start the week off. So the FTSE 100 forecast is in focus for this week’s weekend indices outlook. We have plenty of UK, European and US earnings to look forward to as the week progresses, while key data from the UK and US will make rate cut expectations a key talking point on both sides of the pond.
Indices weekly outlook: FTSE holds steady ahead of UK data after tech volatility
Last week saw the technology sector take a plunge, before dip buyers stepped in on Friday to save the day, helping to fuel a late rally on Wall Street. In Europe, the major indices also came off their earlier lows to close either flat or in the positive. In the week ahead, the global macro calendar is lighter, with US market closed on Tuesday in observance of Veterans Day.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.