



Two trades to watch: Nasdaq, WTI oil
Nasdaq extends gains with Microsoft, Alphabet earnings due. US crude oil eases ahead of API stockpile data.
Share this:

Nasdaq extends gains with Microsoft, Alphabet earnings due
The Nasdaq close closed 0.9% higher in the previous session, helped along by a 12% jump in Tesla following an order from Hertz for 100,000 EVs.
The US tech heavy index is set to push higher again today. After the close Facebook reported earnings, beating forecasts with EPS at $3.22 vs $3.17 est. on revenue of $29.01 billion. Monthly active users rose 6%. So far the change in iOS privacy policy isn’t being reflected in softer ad spend.
Today more earnings from big names such as Microsoft and Alphabet are due.
Data wise the key focus will be on US consumer confidence which is set to decline to 108.3 from 109.3.
Where next for the Nasdaq?
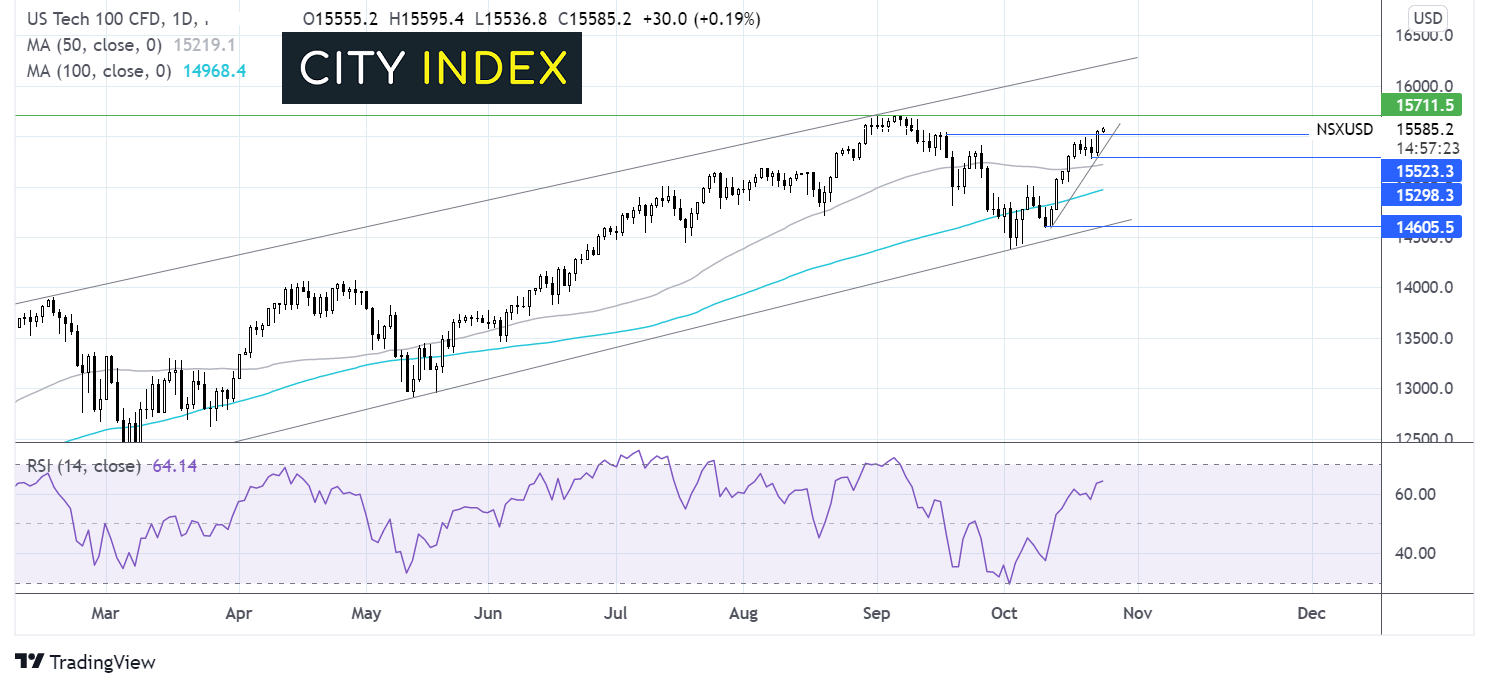
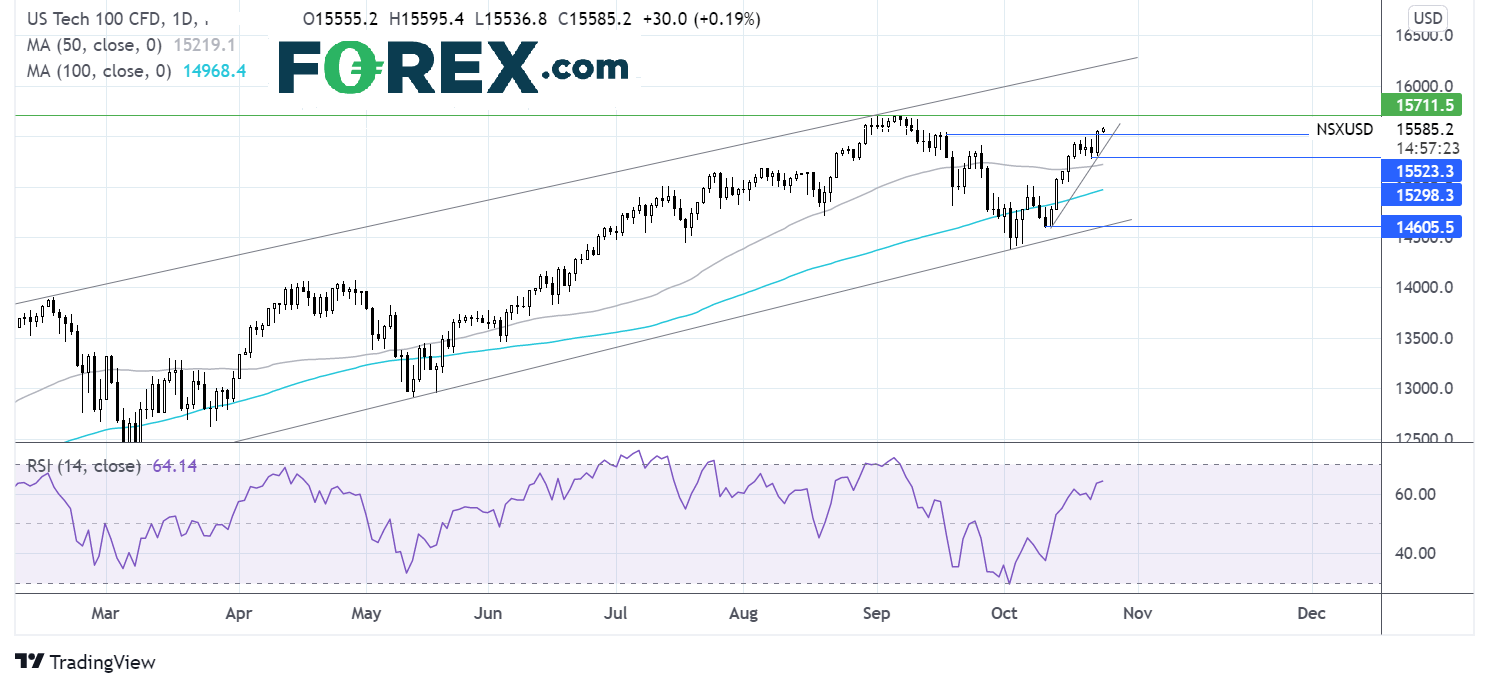
The Nasdaq has extended its rebound off 14600 hit October 12, retaking both the 50 & 100 sma. The index trades above a steep rising trendline from this date.
The price breaking out above resistance at 15500 and the bullish RSI point to further upside to come.
A break above 15700 is needed for fresh all-time highs to be reached.
There are several points of support near term, starting with 15500 the mid-September high. Break through here could open the door to 15425 the rising trendline resistance, exposing the 50 sma at 15200. A break below this level could negate the near-term uptrend. It would take a move below 14600 for the sellers to gain traction.
US crude oil eases ahead of API stockpile data
WTI crude pulled back from 85.26 a 7 year high reached yesterday and trades mildly under pressure below 84.00.
Broadly speaking fundamentals remain supportive amid strong demand in the US and the ongoing energy crisis. Whilst China’s intervention into the power and coal markets have seen prices cool slightly, global energy prices still remain elevated amid the onset of winter in the northern hemisphere. Goldman Sachs sees oil prices reaching $90 by the end of the year.
Traders look ahead to the release of weekly stockpile data from the API. Crude stockpiles are expected to have risen by 1.7 million.
Traders are also awaiting the outcome of talks between Iran and the West after comments from the US that talks were at a crucial phase.
Separately, Saudi Arabia’s aim to reach net zero by 2060 could challenge the bulls.
Where next for WTI oil prices?
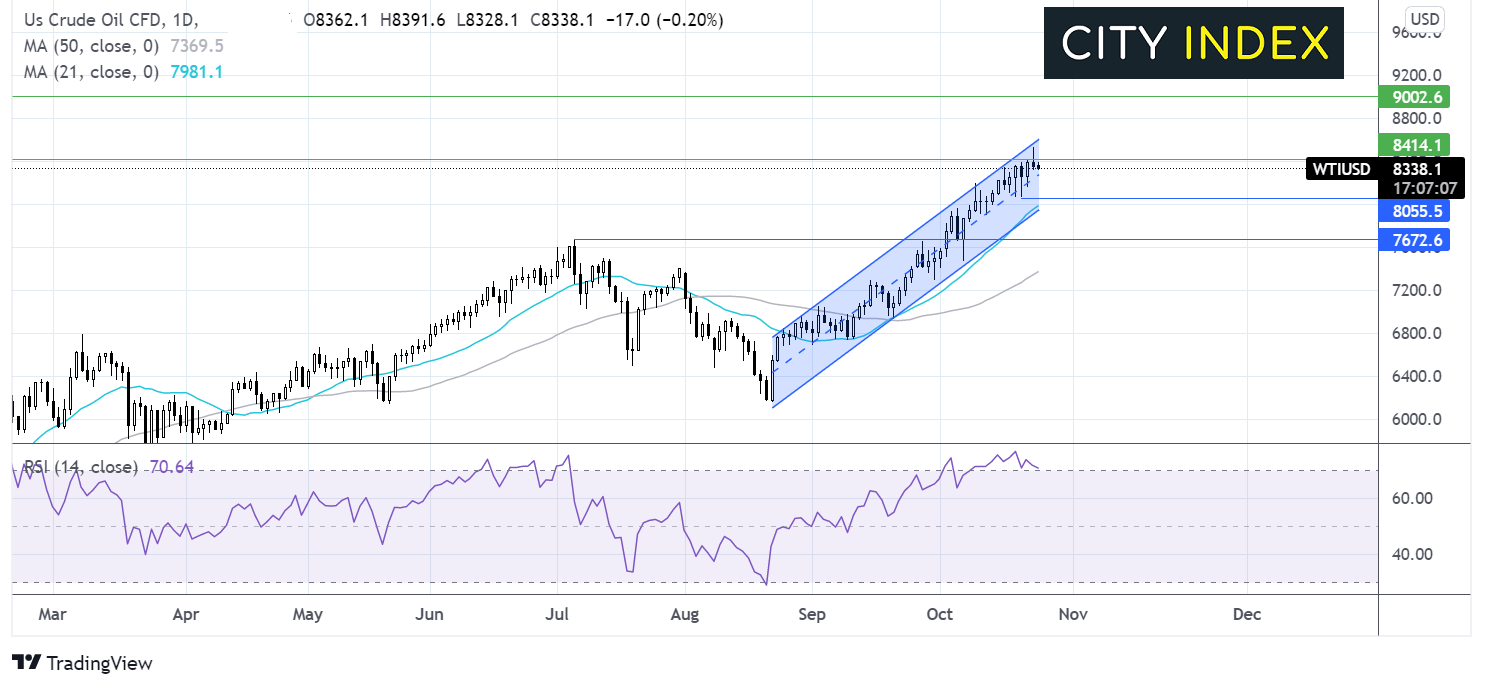
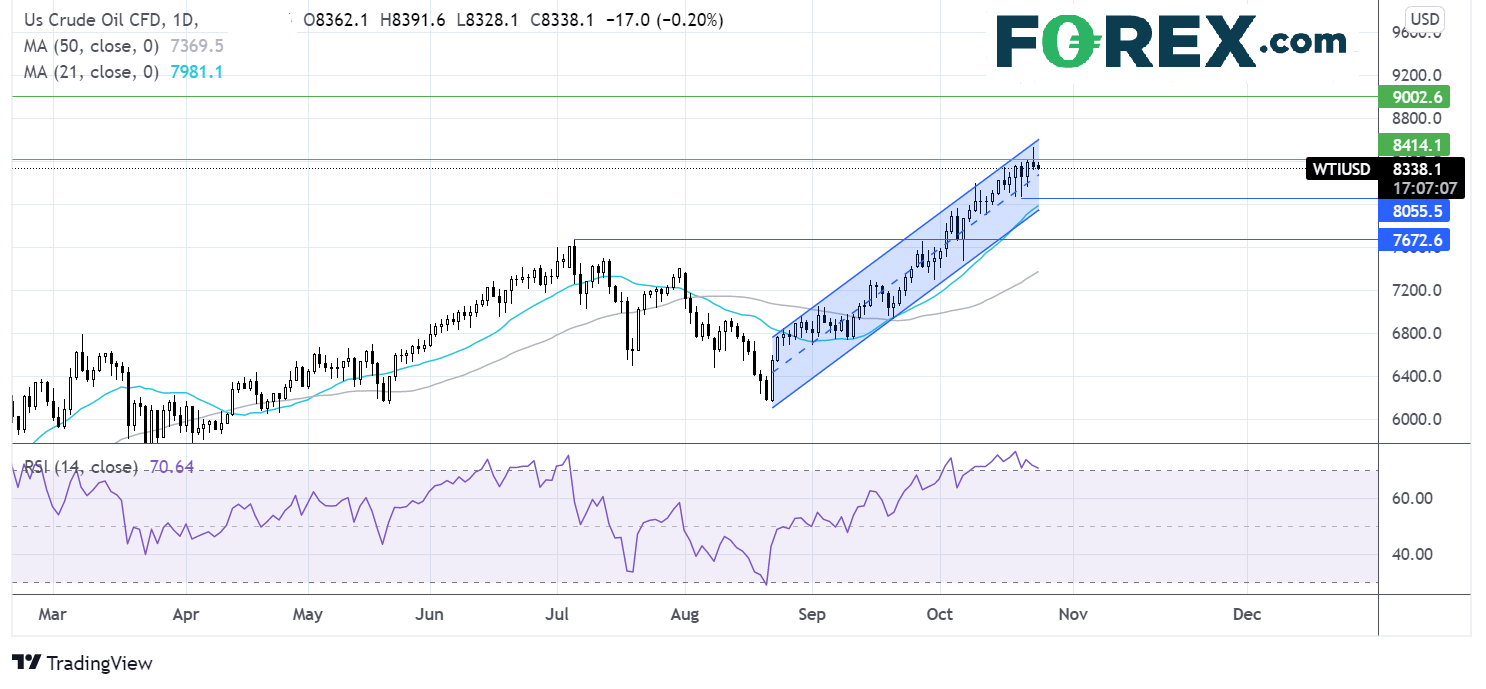
The strong rebound from the 61.20 low in late August remains intact. Oil continues to trade within the multi-month ascending channel.
After hitting a 7 year high and the upper band of the rising channel the price has eased lower. The RSI is in over bought territory so a move lower or some consolidation is expected before further gains towards $90.
Meanwhile, support can be seen at 80.70 last week’s low and 79.71 the lower band the rising channel and the 21 sma which could be a tough nut to crack.
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels
- Place the trade.
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD forecast: Eurozone stagflation risks mount as dollar holds firm ahead of data
The dollar was bouncing back at the time of writing, after it had eased overnight on the back of some weaker-than-expected economic data yesterday which had prompted markets to scale back expectations of an October Fed rate hike. However, with more significant US data due today and Friday, and with oil prices continuing to remain elevated, the dollar’s broader direction remains bullish.

Treasury Yields Lose Momentum as Energy ETF Retreats
The 10-year Treasury yield is testing a resistance zone respected since the 1920s, as bearish RSI divergence signals fading upside momentum.


AUD/USD outlook: Aussie slips despite hawkish RBA ahead of key data
The AUD/USD was unable to benefit from the Reserve Bank of Australia’s 25-basis-point rate hike overnight. The RBA lifted the cash rate to 4.60%, in line with expectations. However, the Australian dollar weakened following the decision, with much of the Bank’s hawkish stance seemingly priced in ahead of the announcement. The US dollar has also remained largely supported following the recent turmoil in the bond markets.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.