



US bad data dump; but it’s inflation that matters!
The US released a host of December economic data this morning, and all missed BIGLY.
Share this:

The US released a host of December economic data this morning, and all missed BIGLY. December Retail Sales was -1.9% MoM vs and expectation of 0% and a lower revised November print to 0.2% MoM. This was apparently due to people moving forward their holiday shopping to make sure items arrived on time. December’s Retail Sales ex-Autos print was -2.3% MoM vs +0.2% MoM expected and a lower revised November print to 0.1% MoM. Also, this morning, the US released Industrial Production for December at -0.1% MoM vs +0.3% MoM expected. The November print was revised slightly higher to 0.7% MoM for November; however, the revision wasn’t enough to make December’s print stronger. Manufacturing Production for December was -0.3% MoM vs +0.5% MoM expected and a lower revised print for November of 0.6%. Again, a miss.
That brings us to January’s preliminary Michigan Consumer Sentiment data. The headline print was 68.8 vs 70 expected and 70.6 in December. The miss was primarily in the expectations component, which was 65.9 vs 66.5 expected. The current conditions component was 73.2 vs 73.3 expected.
None of that matters! The Fed is looking at inflation. The 1-year inflation outlook from the consumer sentiment data was in-line at 4.9% vs 4.8% in November. The 5-year inflation outlook was 3.1% vs 2.9% expected and 2.9% in November. This means that in 5 years, consumers expect inflation to still be 3.1%. Remember: The Fed targets 2% inflation!
It's not a surprise that Fed speakers this week were all hawkish. Fed members Barkin, Messer, George, Daly, Harker, Waller and Williams all spoke this week, in addition to the nomination hearings for Powell and Brainard. Most suggested a rate hike in March may be appropriate! Even the biggest Fed dove, Neel Kashkari said that he is looking for 2 rate hikes this year! This is despite the weaker Non-Farm Payroll data over the last 2 months, which averaged only +224,000 jobs.
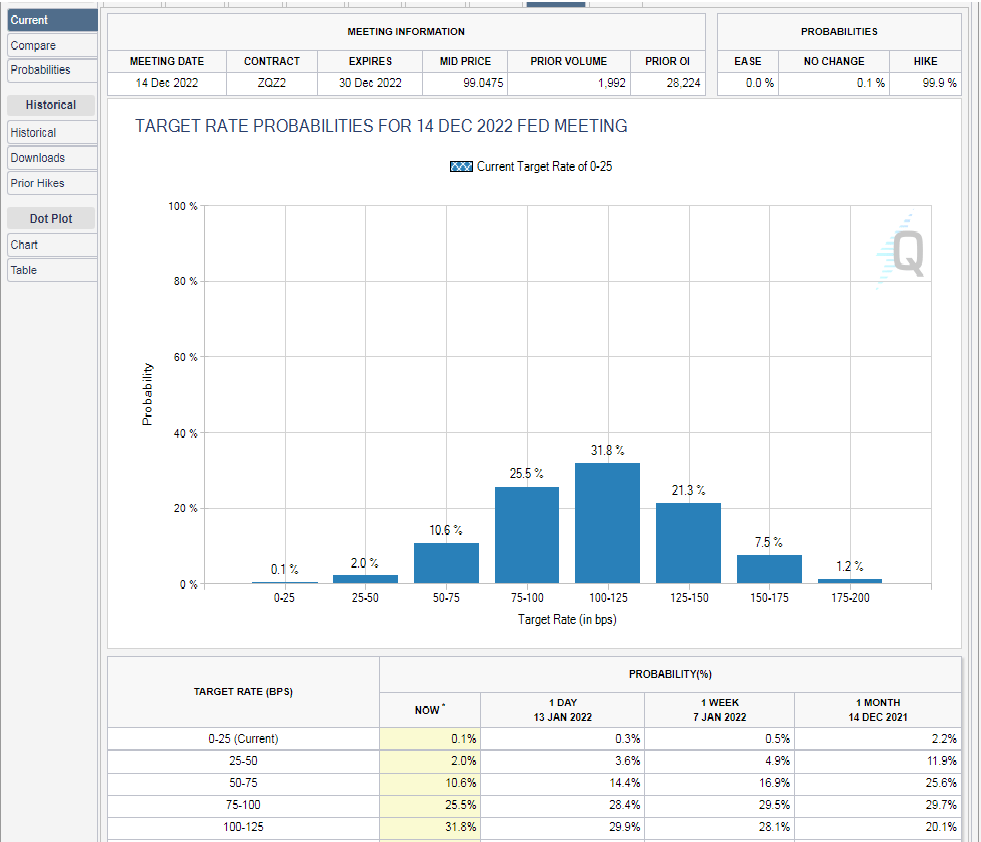
As a result, markets are currently pricing in 4 rate hikes over the remainder of 2022 according to the CME FedWatch Tool:
Source: CME
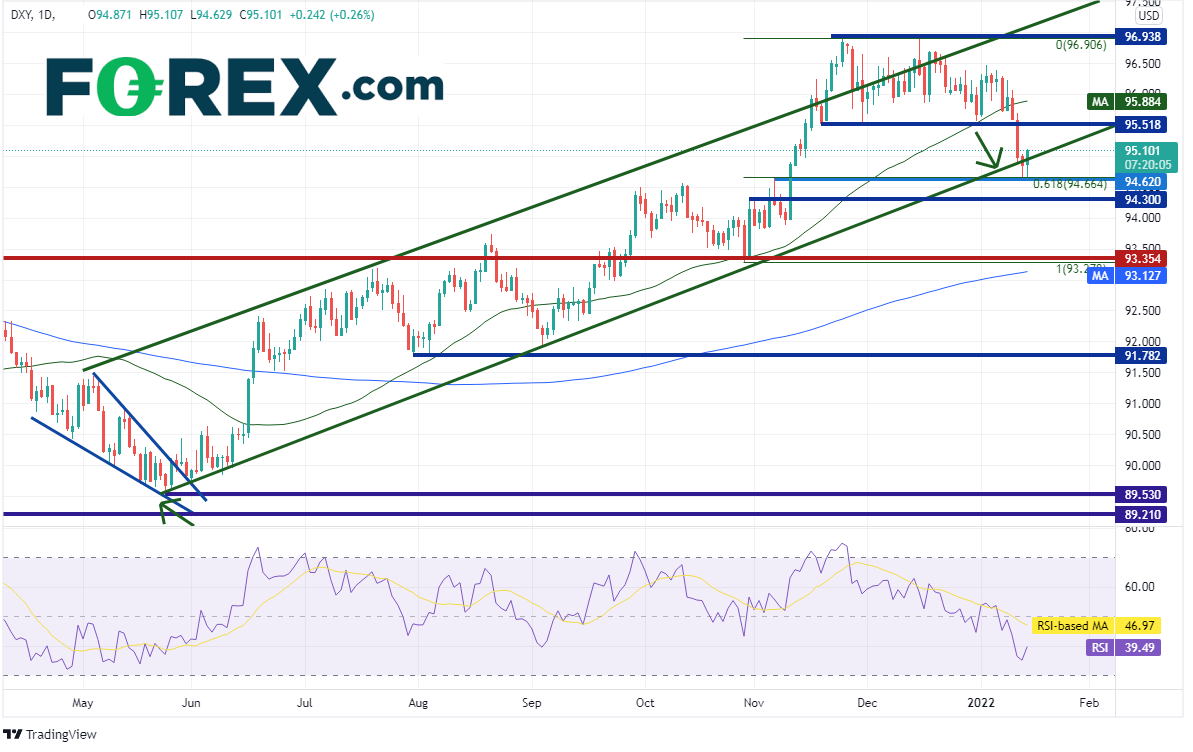
This should be bullish news for the US Dollar Index. The DYX has moved back above the bottom trendline of the long-term, upward sloping channel the pair has been in since May 2021. Horizontal resistance above is at 95.52 ahead of the 50 Day Moving Average at 95.88. Thus far, price has held the 61.8% Fibonacci retracement from the October 28th, 2021 lows to the November 24th highs near 94.66. If the DXY breaks below there, it can fall to the horizontal support at 94.30 and 93.35.
Source: Tradingview, Stone X
Today’s US data releases were all worse than expected. But the only ones the truly matter are the inflation components of the Michigan Consumer Sentiment Survey. With inflation expectations well above the Fed’s 2% target, the Fed is signaling rate hikes are coming sooner than later! Watch the DXY for clues on how to trade US Dollar pairs.
The US released a host of December economic data this morning, and all missed BIGLY. December Retail Sales was -1.9% MoM vs and expectation of 0% and a lower revised November print to 0.2% MoM. This was apparently due to people moving forward their holiday shopping to make sure items arrived on time. December’s Retail Sales ex-Autos print was -2.3% MoM vs +0.2% MoM expected and a lower revised November print to 0.1% MoM. Also, this morning, the US released Industrial Production for December at -0.1% MoM vs +0.3% MoM expected. The November print was revised slightly higher to 0.7% MoM for November; however, the revision wasn’t enough to make December’s print stronger. Manufacturing Production for December was -0.3% MoM vs +0.5% MoM expected and a lower revised print for November of 0.6%. Again, a miss.
That brings us to January’s preliminary Michigan Consumer Sentiment data. The headline print was 68.8 vs 70 expected and 70.6 in December. The miss was primarily in the expectations component, which was 65.9 vs 66.5 expected. The current conditions component was 73.2 vs 73.3 expected.
None of that matters! The Fed is looking at inflation. The 1-year inflation outlook from the consumer sentiment data was in-line at 4.9% vs 4.8% in November. The 5-year inflation outlook was 3.1% vs 2.9% expected and 2.9% in November. This means that in 5 years, consumers expect inflation to still be 3.1%. Remember: The Fed targets 2% inflation!
Forecasting 2022 inflation: Transitory no more?
It's not a surprise that Fed speakers this week were all hawkish. Fed members Barkin, Messer, George, Daly, Harker, Waller and Williams all spoke this week, in addition to the nomination hearings for Powell and Brainard. Most suggested a rate hike in March may be appropriate! Even the biggest Fed dove, Neel Kashkari said that he is looking for 2 rate hikes this year! This is despite the weaker Non-Farm Payroll data over the last 2 months, which averaged only +224,000 jobs.
Central Banks: Liftoff in Focus?
As a result, markets are currently pricing in 4 rate hikes over the remainder of 2022 according to the CME FedWatch Tool:
Source: CME
Trade DXY now: Login or Open a new account!
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
This should be bullish news for the US Dollar Index. The DYX has moved back above the bottom trendline of the long-term, upward sloping channel the pair has been in since May 2021. Horizontal resistance above is at 95.52 ahead of the 50 Day Moving Average at 95.88. Thus far, price has held the 61.8% Fibonacci retracement from the October 28th, 2021 lows to the November 24th highs near 94.66. If the DXY breaks below there, it can fall to the horizontal support at 94.30 and 93.35.
Source: Tradingview, Stone X
Today’s US data releases were all worse than expected. But the only ones the truly matter are the inflation components of the Michigan Consumer Sentiment Survey. With inflation expectations well above the Fed’s 2% target, the Fed is signaling rate hikes are coming sooner than later! Watch the DXY for clues on how to trade US Dollar pairs.
Learn more about forex trading opportunities.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.
Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.