



US CPI Preview: Could a Cool CPI Put a 50bps Fed Cut in Play?
The post-blackout coordinated slowdown in the jobs market and producer prices opens the door for a potential 50bps “double” rate cut from the Fed if this month’s CPI report follows the PPI report in reporting cooler-than-anticipated price pressures.
Share this:

US CPI KEY TAKEAWAYS:
- US CPI expectations: 2.9% y/y headline inflation, 3.1% y/y core inflation
- A surprise drop in this week’s CPI report could put a 50bps Fed rate cut firmly on the table, something the market sees as just a 10% probability
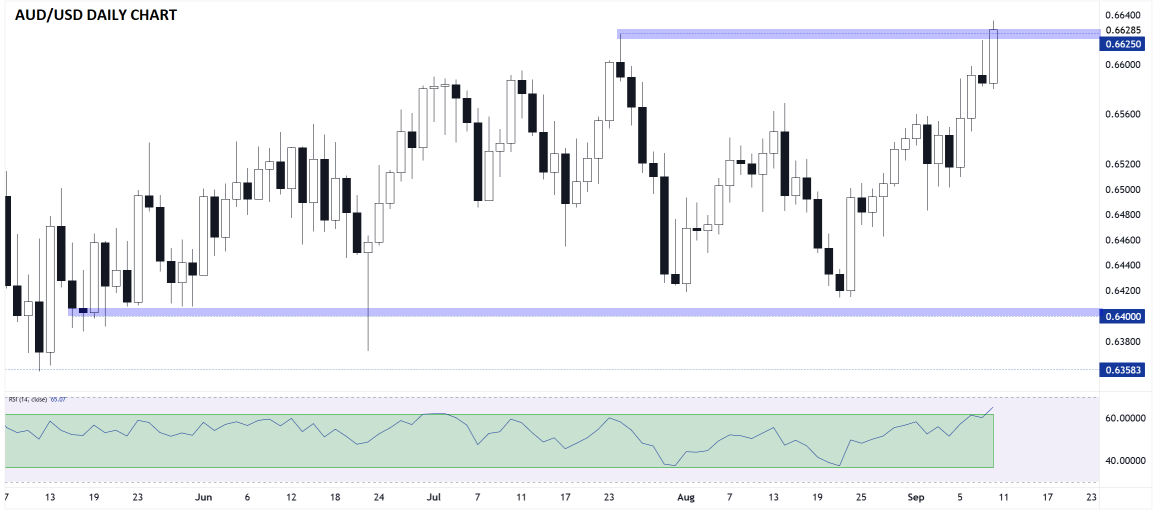
- AUD/USD bulls will be watching for a potential miss in US CPI that drives a breakout above 0.6625 resistance and a potential continuation higher.
When is the US CPI report?
The US CPI report for August will be released at 8:30ET (12:30 GMT) on Thursday, September 11.
What are the US CPI Report Expectations?
Traders and economists are projecting headline CPI to come in at 2.9% y/y, with the core (ex-food and -energy) reading expected at 3.1% y/y. Both of those readings, if fulfilled, would mark upticks from last month’s inflation rate.
US CPI Forecast
Quirks of the calendar are an under-discussed aspect of market volatility, and this month’s economic data is clear example of that dynamic.
With Federal Reserve meetings taking place semi-quarterly, or about every six or seven weeks, they often don’t align perfectly with the monthly release cadence of most important economic data points. To wit, this month’s weaker-than-expected NFP report coincided with the start of the Fed’s media “blackout period,” so traders have no new updates on how the central bank is viewing the state of the labor market ahead of its monetary policy meeting next week. That issue was compounded by yesterday’s far larger-than-expected downward revision to previous jobs data, meaning that we now know that the labor market is substantially weaker than it was the last time we heard from any Federal Reserve official.
Transitioning into the other side of the Fed’s dual mandate, this morning’s PPI report also came in substantially below expectations (though still in-line with recent readings over Q2). The post-blackout coordinated slowdown in both the labor market and producer prices opens the door for a potential 50bps “double” rate cut from the Fed if this month’s CPI report follows the PPI report in reporting cooler-than-anticipated price pressures.
Broadly speaking, US consumer inflation has seen its decline toward the Fed’s 2% target stall for more than a year now, with headline CPI readings stuck between the 2.3% and 3.0% y/y range for that period. Meanwhile, Core CPI, which filters out more volatile food and energy prices to better show the underlying trend in prices, has turned higher in recent months after dropping as low as 2.8% y/y earlier this year.
This puts the Federal Reserve in a sticky position heading into next week’s meeting, as the consistently above-target inflation readings may limit its scope to deliver the more aggressive interest rate cuts that the jobs market side of the dual mandate prescribes. In terms of a potential market reaction, a surprise drop in this week’s CPI report could alleviate that tension and put a 50bps rate cut firmly on the table, something the market sees as just a 10% probability as we go to press:
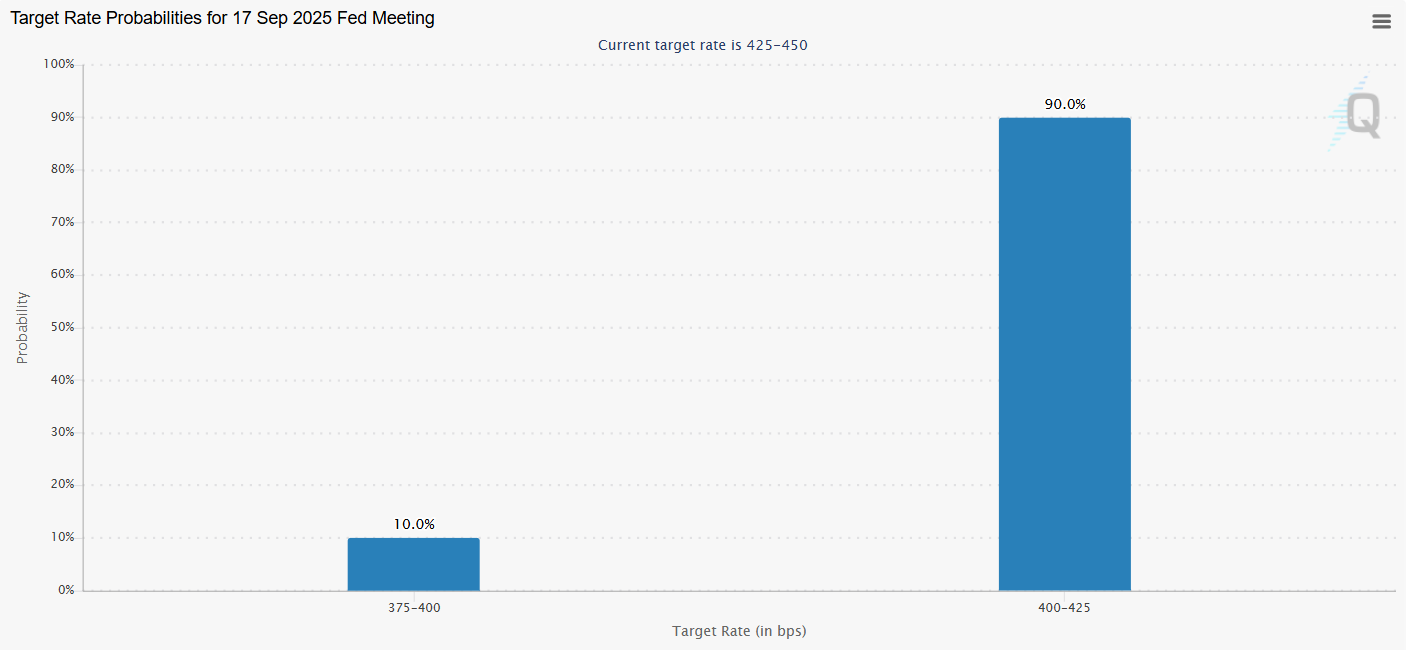
Source: CME FedWatch
As many readers know, the Fed technically focuses on a different measure of inflation, Core PCE, when setting its policy, but for traders, the CPI report is at least as significant because it’s released weeks earlier. As we noted above, CPI has generally ticked lower so far this year, but it remains stubbornly above the Fed’s 2% target:

Source: TradingView, StoneX
Looking at the chart above, the “Prices” component of the PMI reports has accelerated sharply higher over the last couple of months, and even before the Trump administration’s tariffs were formally announced (and subsequently paused). Despite signs of slowing economic growth, firms are having to pay up for goods and services amidst the ongoing uncertainty around trade policy, potentially putting upward pressure on the CPI report in the coming months.

US Dollar Technical Analysis – AUD/USD Daily Chart
Source: TradingView, StoneX
One of the most interesting currency pairs to watch around the US CPI report will be AUD/USD, which is currently testing a 10-month high at 0.6625. The pair has been trapped in a consolidation zone between this resistance level and 0.6400 support since late May, setting the stage for a potential higher volatility breakout if we see a confirmed breakout this week.
AUD/USD bulls will be watching for a potential miss in US CPI that puts a 50bps rate cut on the table for next week (or at least increases the odds of three straight 25bps rate cuts to close out the year). In that scenario, a breakout and continuation toward the 0.6700 handle or the 78.6% Fibonacci retracement of the 2024-2025 slide near 0.6725 would be in play.
Meanwhile, a hotter-than-anticipated CPI reading would pour cold water on hopes of a double interest rate cut any time soon, likely leading to an AUD/USD reversal off resistance. If that is indeed what we see, the pair may quickly retrace this week’s rally back to the mid-0.6500s or even the middle of the recent range near 0.6500.
-- Written by Matt Weller, Global Head of Research
Check out Matt’s Daily Market Update videos on YouTube and be sure to follow Matt on Twitter: @MWellerFX



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD forecast: Eurozone stagflation risks mount as dollar holds firm ahead of data
The dollar was bouncing back at the time of writing, after it had eased overnight on the back of some weaker-than-expected economic data yesterday which had prompted markets to scale back expectations of an October Fed rate hike. However, with more significant US data due today and Friday, and with oil prices continuing to remain elevated, the dollar’s broader direction remains bullish.

NZD/USD pressure mounts as payrolls looms large
NZD/USD has fallen sharply as Fed rate expectations reset higher, but extreme downside stretch and major support raise the risk of a violent counter-trend rebound.


US Core PCE Preview: Stale or Significant for the Fed
Core PCE inflation takes center stage Wednesday, with traders watching for signs of renewed price pressure and clues on whether the Fed could hike again in October.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.