



US headline PPI as expected; Core PPI higher
The reaction to today’s PPI print was relatively muted compared to that of yesterday’s CPI print.
Share this:

Following yesterday’s higher than expected CPI data, the US Producer Price Index was roughly as expected and lower than July’s readings. The headline PPI for August was 8.7% YoY vs 8.8% YoY expected and 9.8% YoY in July, while the Core PPI was 7.3% YoY vs 7.1% YoY expected and a 7.6% YoY reading from July. For the producers, final demand prices were lower in August than July. This is good! However, note that although the Core PPI was lower than July’s reading, it was higher than expectations. This would indicate that when food and energy are removed from the equation, the PPI print is still higher than expectations. For the Fed, this may indicate that inflation expectations at the producer level has spilled over and may become entrenched in producer prices.
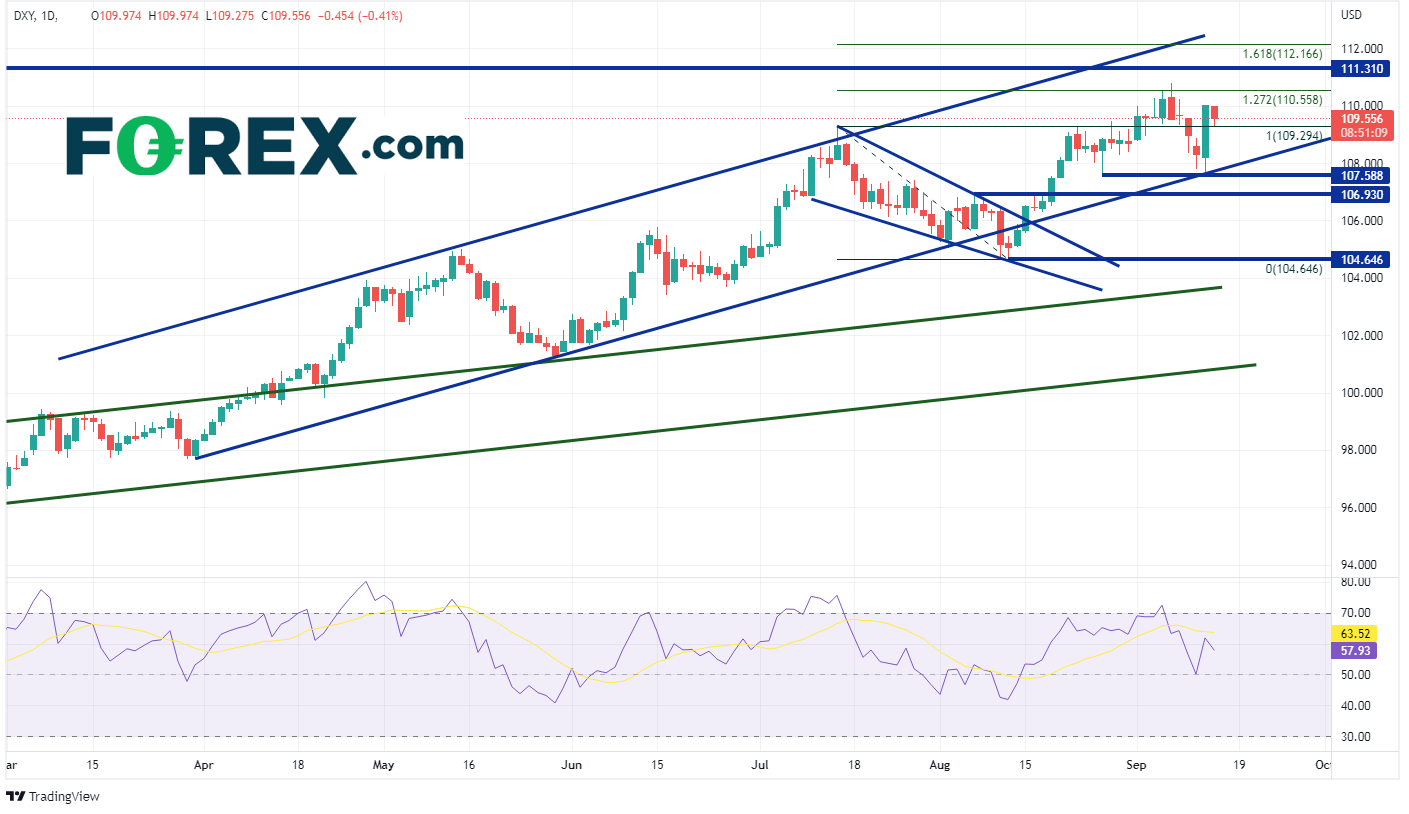
Due to the mixed PPI readings, the US Dollar is relatively unchanged from before the print. However, the US Dollar Index (DXY) is trading lower today as profit taking seems to have taken place. After yesterday’s CPI print, the DXY bounced off the August 26th lows and the upward sloping bottom trendline of the long-term channel that they index has been in since March. The DXY rose nearly 171 pips yesterday! Some profit taking today is to be expected, however that doesn’t mean the DXY won’t continue higher. The first resistance is at the highs of September 7th, at 110.79. Above there, price can move to horizontal resistance at 111.31, which is resistance from September 2001, then the 161.8% Fibonacci extension from the highs of July 14th to the lows of August 11th at 112.17. First support is all the way down at yesterday’s low of 107.68. Below there, the DXY can fall to support at the highs of August 5th near 106.93 and then the lows of August 11th at 104.65.
Source: Tradingview, Stone X
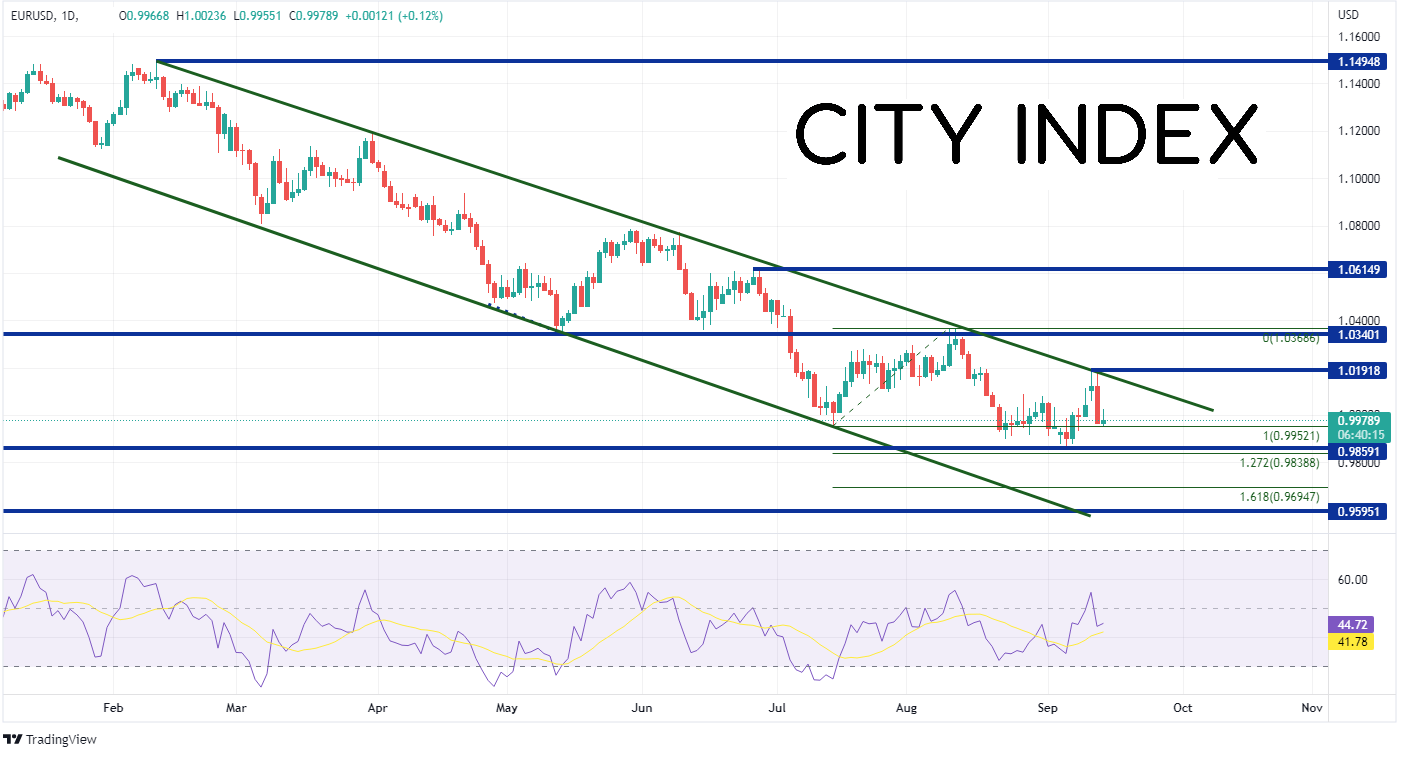
As the Euro makes up 57% of the DXY, one could expect that EUR/USD is moving in the opposite direction to the US Dollar Index. After yesterday’s loss of nearly 155 pips, in which price bounced off the top trendline that the pair has been in since February, EUR/USD is seeing some profit taking today. But that doesn’t mean the pair can’t move lower. First support is at the lows of September 6th at 0.9859. Just below there is the 127.2% Fibonacci extension from the lows of July 14th to the highs of August 10th at 0.9839 and then the 161.8% Fibonacci extension from the same timeframe at 0.9695. First resistance is at yesterday’s highs of 1.0187, then the August 10th highs at 1.0367. Above there, price can move to the highs of June 27th near 1.6149.

Source: Tradingview, Stone X
The reaction to today’s PPI print was relatively muted compared to that of yesterday’s CPI print. Although the August Core PPI was hotter than expected, it was still lower than July’s print. Does that mean lower inflation is working its way from PPI to CPI? Maybe. However, today’s readings are still very high, relatively speaking, and the Fed is still expected to hike rates by 75bps at the FOMC meeting next week!
Following yesterday’s higher than expected CPI data, the US Producer Price Index was roughly as expected and lower than July’s readings. The headline PPI for August was 8.7% YoY vs 8.8% YoY expected and 9.8% YoY in July, while the Core PPI was 7.3% YoY vs 7.1% YoY expected and a 7.6% YoY reading from July. For the producers, final demand prices were lower in August than July. This is good! However, note that although the Core PPI was lower than July’s reading, it was higher than expectations. This would indicate that when food and energy are removed from the equation, the PPI print is still higher than expectations. For the Fed, this may indicate that inflation expectations at the producer level has spilled over and may become entrenched in producer prices.
Due to the mixed PPI readings, the US Dollar is relatively unchanged from before the print. However, the US Dollar Index (DXY) is trading lower today as profit taking seems to have taken place. After yesterday’s CPI print, the DXY bounced off the August 26th lows and the upward sloping bottom trendline of the long-term channel that they index has been in since March. The DXY rose nearly 171 pips yesterday! Some profit taking today is to be expected, however that doesn’t mean the DXY won’t continue higher. The first resistance is at the highs of September 7th, at 110.79. Above there, price can move to horizontal resistance at 111.31, which is resistance from September 2001, then the 161.8% Fibonacci extension from the highs of July 14th to the lows of August 11th at 112.17. First support is all the way down at yesterday’s low of 107.68. Below there, the DXY can fall to support at the highs of August 5th near 106.93 and then the lows of August 11th at 104.65.

Source: Tradingview, Stone X
Trade the DXY now: Login or Open a new account!
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
As the Euro makes up 57% of the DXY, one could expect that EUR/USD is moving in the opposite direction to the US Dollar Index. After yesterday’s loss of nearly 155 pips, in which price bounced off the top trendline that the pair has been in since February, EUR/USD is seeing some profit taking today. But that doesn’t mean the pair can’t move lower. First support is at the lows of September 6th at 0.9859. Just below there is the 127.2% Fibonacci extension from the lows of July 14th to the highs of August 10th at 0.9839 and then the 161.8% Fibonacci extension from the same timeframe at 0.9695. First resistance is at yesterday’s highs of 1.0187, then the August 10th highs at 1.0367. Above there, price can move to the highs of June 27th near 1.6149.
Source: Tradingview, Stone X
Trade EUR/USD now: Login or Open a new account!
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
The reaction to today’s PPI print was relatively muted compared to that of yesterday’s CPI print. Although the August Core PPI was hotter than expected, it was still lower than July’s print. Does that mean lower inflation is working its way from PPI to CPI? Maybe. However, today’s readings are still very high, relatively speaking, and the Fed is still expected to hike rates by 75bps at the FOMC meeting next week!
Learn more about forex trading opportunities.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.
Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.