


US Market Open: Markets Shift Focus to Earnings as Geopolitical Risks Ease
After weeks dominated by geopolitical headlines, investors are turning their attention back to company fundamentals. As tensions in the Middle East ease and oil prices retreat, markets are preparing for the start of the second-quarter earnings season led by the major US banks.
Share this:
US Market Open: Markets Pause as Geopolitical Risks Ease Ahead of Earnings Season
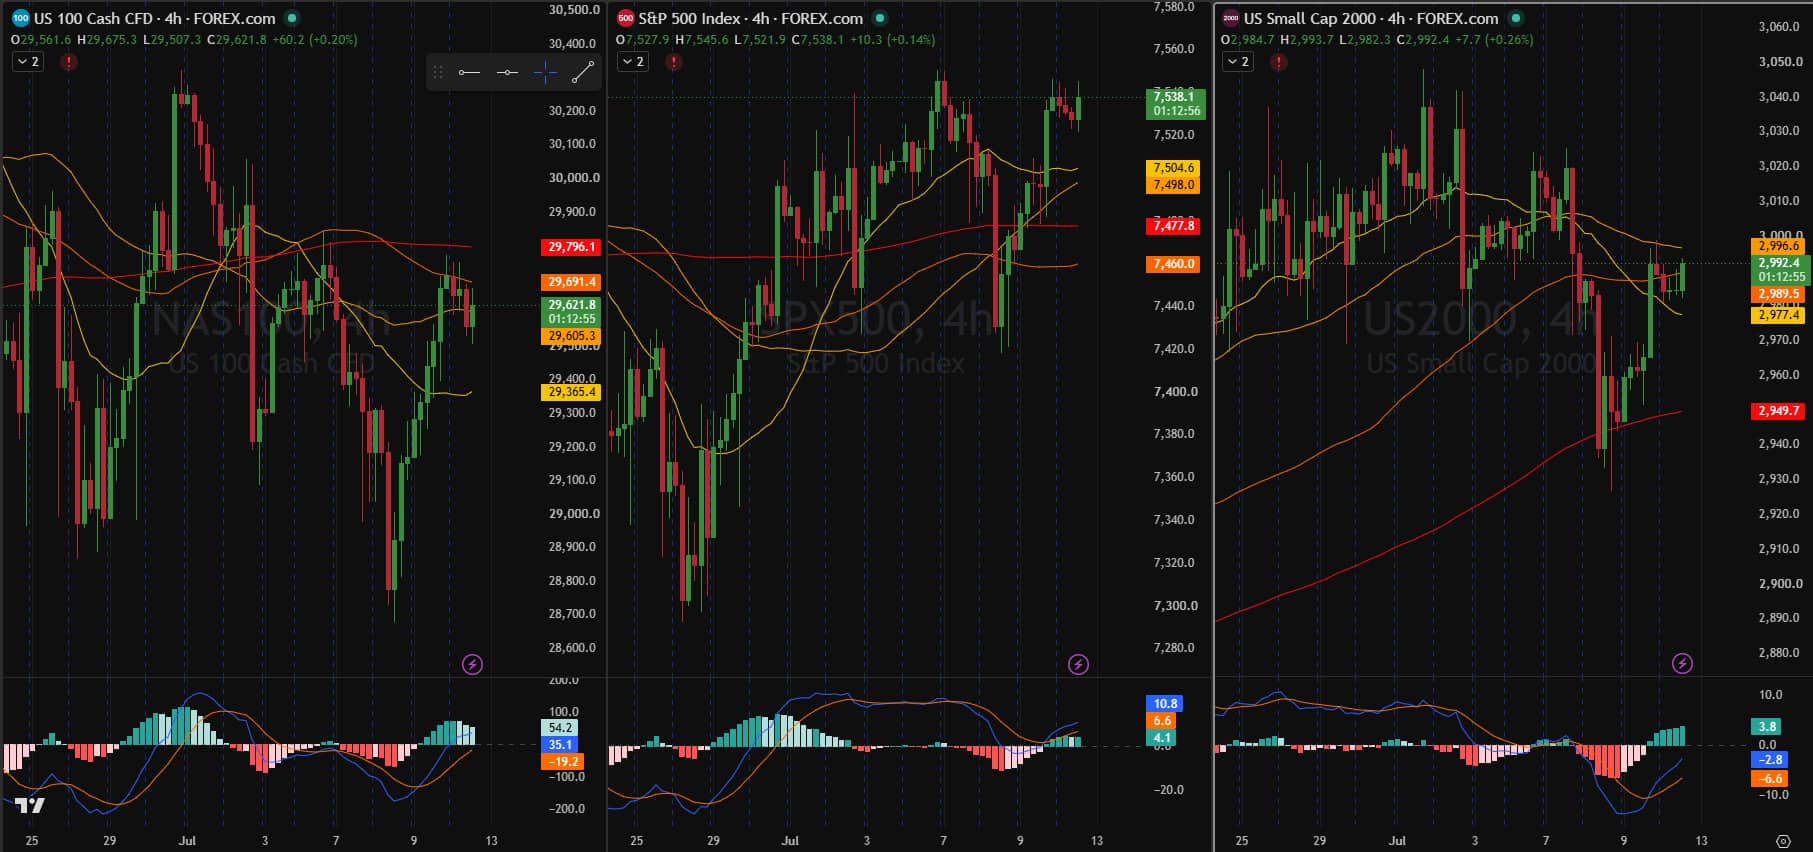
US equity futures are pointing to a slightly softer open following Thursday's strong rally. The Nasdaq is underperforming, largely due to positioning ahead of SK Hynix's highly anticipated US ADR debut, while the S&P 500 and Russell 2000 are holding up relatively well.
Although markets remain sensitive to geopolitical headlines, investors are increasingly shifting their focus back toward fundamentals. With the second-quarter earnings season set to begin next week, attention is gradually turning away from macro uncertainty and toward corporate results, starting with the major US banks.
Geopolitical Tensions Cool, but Risks Remain
The tone across markets has improved after a relatively quiet night in the Middle East.
According to both CNN and Axios, regional mediators are working to bring the United States and Iran back to the negotiating table. While no agreement has been reached, the absence of fresh military escalation has helped calm investor nerves after several volatile sessions.
Investors are still watching developments closely, but for now the market is assigning a higher probability to continued diplomatic efforts than to a broader regional conflict.
Oil Gives Back Part of Its Risk Premium
That improving geopolitical backdrop is reflected in the oil market.
Brent crude is modestly lower and trading around the middle of this week's range as traders wait for either renewed negotiations or fresh military developments. The International Energy Agency also added a slightly bearish tone after lowering its 2026 oil demand forecast while highlighting stronger supply growth and continued oil shipments through the Strait of Hormuz.
As long as global energy supplies remain largely unaffected, investors appear comfortable removing some of the geopolitical premium that had built into crude prices earlier this week.
Currency Markets Focus on Japan
The US dollar is trading slightly weaker against most major currencies.
The Japanese yen is leading gains after Finance Minister Katayama proposed measures aimed at encouraging pension funds to increase investments in domestic assets. The comments supported both Japanese government bonds and the yen, although investors remain cautious about whether such proposals can ultimately be implemented.
Equities Shift Back Toward Company-Specific Catalysts
European markets are trading broadly steady, while US futures suggest a mixed start to the session.
Technology shares are underperforming ahead of SK Hynix's US listing, while communications and travel stocks are among the strongest performers in Europe. In Asia, semiconductor stocks continued to lead gains, with South Korea outperforming as investors positioned for the SK Hynix debut.
The relatively muted reaction across global equity markets suggests investors are becoming more comfortable looking through geopolitical headlines unless they materially alter the economic outlook.
Looking Ahead: Earnings Season Takes Centre Stage
While geopolitical developments remain an important source of uncertainty, markets are preparing for another major shift in focus.
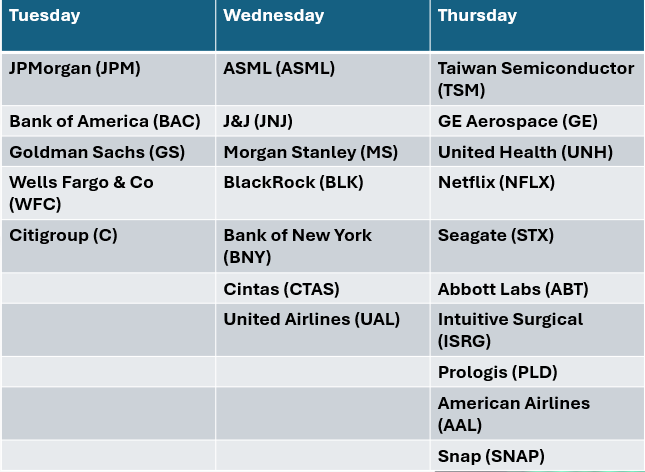
Second-quarter earnings season officially gets underway next week, led by the major US banks. Investors will be watching closely for commentary on loan growth, consumer spending, credit quality, investment banking activity and capital markets revenues. Just as importantly, management teams will provide updated guidance on the economic outlook, offering one of the first comprehensive reads on how corporate America is navigating the current environment.
With equity markets trading near record highs, expectations have risen considerably. Strong earnings and constructive guidance could provide another leg higher for equities, while disappointing results may prompt investors to reassess current valuations.
What to Watch Today
Today's calendar is relatively light, with the Canadian employment report representing the main macro event. Delta Air Lines will also report earnings, offering an early indication of consumer demand and travel trends ahead of next week's broader earnings season.
For today's session, markets remain focused on one key question: can diplomatic momentum continue in the Middle East? As long as tensions remain contained and energy markets stay stable, investor attention is likely to continue shifting toward company fundamentals and the upcoming earnings season.
Philip J Papageorgiou - Head of Investment Research
Find Philip on X (x twitter) - PhilipForexCom
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.