




US open Earnings Fed Biden in focus
US stocks are heading for a mixed start ahead of a busy session with more top tier earnings due, the Fed rate decision & a key speech from Biden.
Share this:

US futures
Dow futures -0.2% at 33910
S&P futures +0.02% at 4187
Nasdaq futures 10.14% at 13941
In Europe
FTSE +0.7% at 6950
Dax +0.44% at 15315
Euro Stoxx +0.2% at 4017
Learn more about trading indices
US stocks point to a mixed open
US stocks are heading for a mixed start on Wednesday as investors digest a more earnings from tech giants and ahead of the two key risk events this week, the Fed’s rate decision and a key speech from Biden.
Earnings
Alphabet impressed with earning on Tuesday after the close and trades +5% pre-market. Google parent posted a 34% gain in revenue as firms upped their advertising spend in anticipation if the economy reopening. Alphabet announced a $50 billion share buyback programme.
Microsoft reported solid but less spectacular numbers.
Looking ahead Facebook, Apple are due to report after the close.
Booing is set to release its earnings report which should shed some light on the travel industries recovery.
Federal Reserve
The Fed are not expected to move on policy so much of the focus will be on Fed Chair Powell’s pursuant press conference. With the US economic recovery looking increasing more convincing Powell will need to continue walking the fine line between sounding optimistic whilst reining in expectations. Should the Fed start sounding slightly hawkish, growth stocks could come under pressure.
The June meeting is likely to be much more significant as the US population will likely be close to the 75% vaccinated which the Fed has mentioned as a starting point to talk tapering.
Biden
Biden is due to give his first speech before a joint Congress. He is expected to lay out his plans for huge public spending financed in part by tax hikes.
Biden could confirm plans to raise capital gains tax to 39.6% to help pay for his $1.8 trillion spending plans covering education and childcare.
Previously reports of tax hikes have sent stocks lower so any signs that plans for tax hikes are becoming more concrete could unnerve investors. However, it is worth noting that this package faces more opposition from Republicans.
Where next for the Dow Jones?
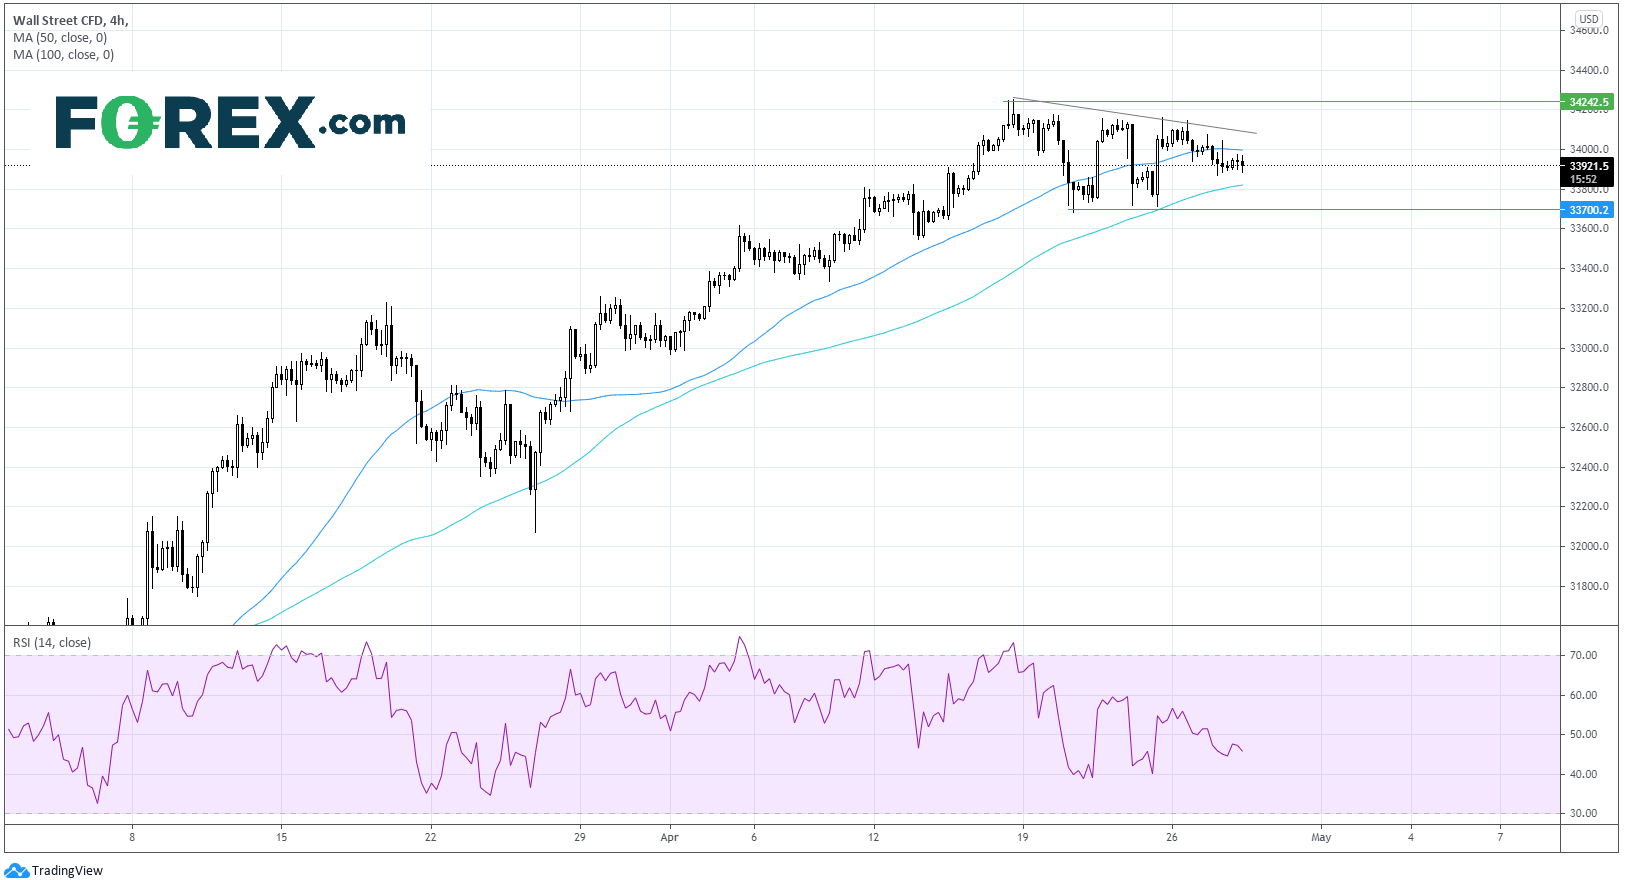
The Dow has been easing lower, consolidating after hitting an all time high on April 16th of 34250. The Dow trades below a mild descending trend line and is caught between its 50 sma & 100 sma on the hour hour chart ahead of the Fed. A break above 34100 the trend line brings the bullish view back into play with a potential move back to the all time high. A move below 33850 the 100 sma could see 33700 tested and open the door to further losses.
FX – US Dollar extends gains, EUR fall on weak German confidence data
The US Dollar is extending gains from Tuesday, boosted by strong consumer confidence data. US consumer morale jumped to a 14 month high as business reopened, boosting hiring and demand.
EUR/USD trades under pressure following disappointing German consumer confidence. The closerly watched GFK consumer confidence index for May fell -8.8 points, down from -6.1 points in April. Expectations had been for a rise to -3.5 points. Given Germany’s current covid situation optimism surrounding the easing of lockdown restrictions and a revival of consumption have been dampened.
GBP/USD +0.3% at 1.3866
EUR/USD -0.21% at 1.2065
Oil rises despite OPEC+ sticking with plans to raise output
Oil is extending gains for a second straight session, despite OPEC+ sticking with plans to raise oil output. The OPEC+ group ditched that planned meeting instead agreeing to move ahead with easing restriction curbs between May 1st – July.
The oil market is focused on the upbeat demand forecast which has prompted OPEC’s decision rather than the fact that more oil will be released back into the market.
Goldman Sachs has added to the upbeat mood surrounding oil, lifting it price forecast to $80 as demand recovers.
The decision by OPEC+ comes even as the covid crisis continues in India the world’s third largest importer of oil.
EIA data is due later today.
US crude trades +0.7% at $63.29
Brent trades +0.5% at $66.27
Learn more about trading oil here.
The complete guide to trading oil markets
Looking ahead
13:30 US Trade balance
15:00 ECB Lagarde speech
15:30 EIA crude stock piles
19:00 Fed interest rate decision
19:30 Fed press conference
US futures
Dow futures -0.2% at 33910
S&P futures +0.02% at 4187
Nasdaq futures 10.14% at 13941
In Europe
FTSE +0.7% at 6950
Dax +0.44% at 15315
Euro Stoxx +0.2% at 4017
Learn more about trading indices
US stocks point to a mixed open
US stocks are heading for a mixed start on Wednesday as investors digest a more earnings from tech giants and ahead of the two key risk events this week, the Fed’s rate decision and a key speech from Biden.
Earnings
Alphabet impressed with earning on Tuesday after the close and trades +5% pre-market. Google parent posted a 34% gain in revenue as firms upped their advertising spend in anticipation if the economy reopening. Alphabet announced a $50 billion share buyback programme.
Microsoft reported solid but less spectacular numbers.
Looking ahead Facebook, Apple are due to report after the close.
Booing is set to release its earnings report which should shed some light on the travel industries recovery.
Federal Reserve
The Fed are not expected to move on policy so much of the focus will be on Fed Chair Powell’s pursuant press conference. With the US economic recovery looking increasing more convincing Powell will need to continue walking the fine line between sounding optimistic whilst reining in expectations. Should the Fed start sounding slightly hawkish, growth stocks could come under pressure.
The June meeting is likely to be much more significant as the US population will likely be close to the 75% vaccinated which the Fed has mentioned as a starting point to talk tapering.
Biden
Biden is due to give his first speech before a joint Congress. He is expected to lay out his plans for huge public spending financed in part by tax hikes.
Biden could confirm plans to raise capital gains tax to 39.6% to help pay for his $1.8 trillion spending plans covering education and childcare.
Previously reports of tax hikes have sent stocks lower so any signs that plans for tax hikes are becoming more concrete could unnerve investors. However, it is worth noting that this package faces more opposition from Republicans.
Where next for the Dow Jones?
The Dow has been easing lower, consolidating after hitting an all time high on April 16th of 34250. The Dow trades below a mild descending trend line and is caught between its 50 sma & 100 sma on the hour hour chart ahead of the Fed. A break above 34100 the trend line brings the bullish view back into play with a potential move back to the all time high. A move below 33850 the 100 sma could see 33700 tested and open the door to further losses.
FX – US Dollar extends gains, EUR fall on weak German confidence data
The US Dollar is extending gains from Tuesday, boosted by strong consumer confidence data. US consumer morale jumped to a 14 month high as business reopened, boosting hiring and demand.
EUR/USD trades under pressure following disappointing German consumer confidence. The closerly watched GFK consumer confidence index for May fell -8.8 points, down from -6.1 points in April. Expectations had been for a rise to -3.5 points. Given Germany’s current covid situation optimism surrounding the easing of lockdown restrictions and a revival of consumption have been dampened.
GBP/USD +0.3% at 1.3866
EUR/USD -0.21% at 1.2065
Oil rises despite OPEC+ sticking with plans to raise output
Oil is extending gains for a second straight session, despite OPEC+ sticking with plans to raise oil output. The OPEC+ group ditched that planned meeting instead agreeing to move ahead with easing restriction curbs between May 1st – July.
The oil market is focused on the upbeat demand forecast which has prompted OPEC’s decision rather than the fact that more oil will be released back into the market.
Goldman Sachs has added to the upbeat mood surrounding oil, lifting it price forecast to $80 as demand recovers.
The decision by OPEC+ comes even as the covid crisis continues in India the world’s third largest importer of oil.
EIA data is due later today.
US crude trades +0.7% at $63.29
Brent trades +0.5% at $66.27
Learn more about trading oil here.
The complete guide to trading oil markets
Looking ahead
13:30 US Trade balance
15:00 ECB Lagarde speech
15:30 EIA crude stock piles
19:00 Fed interest rate decision
19:30 Fed press conference
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.