



US open: Stocks tumble high US inflation persists
Stocks fall after inflation rises by more than expected in April, dashing hopes of a quick fall back towards 2%.
Share this:

US futures
Dow futures -0.6 % at 32530
S&P futures -0.8% at 4065
Nasdaq futures -1.26% at 12468
In Europe
FTSE -0.1% at 7280
Dax +0.02% at 13630
Euro Stoxx -0.3% at 3612
Peak inflation may have passed, but don’t expect a quick drop
US stocks are falling after US inflation slowed for the first time since August last year but was still ahead of forecasts.
US CPI rose 8.3% YoY in April, down from 8.5% in March but above the 8.1% that was forecast. The data suggests that elevated consumer prices and the squeeze on households and businesses will persist, fueling bets of a hawkish Federal Reserve.
Whilst there is a good chance that inflation has peaked, it is not expected to drop away rapidly. Instead, given the breadth of price rises across the economy, combined with higher wages, the picture suggests that elevated inflation is here to stay.
The data supports the Fed’s more hawkish approach after a 50bp rate hike last week and most likely several more to come.
COVID lockdowns in China mean more supply chain disruptions, which, combined with high oil prices and resilient services demand, point to a long road to get inflation back towards the 2% target.
Where next for the Nasdaq?
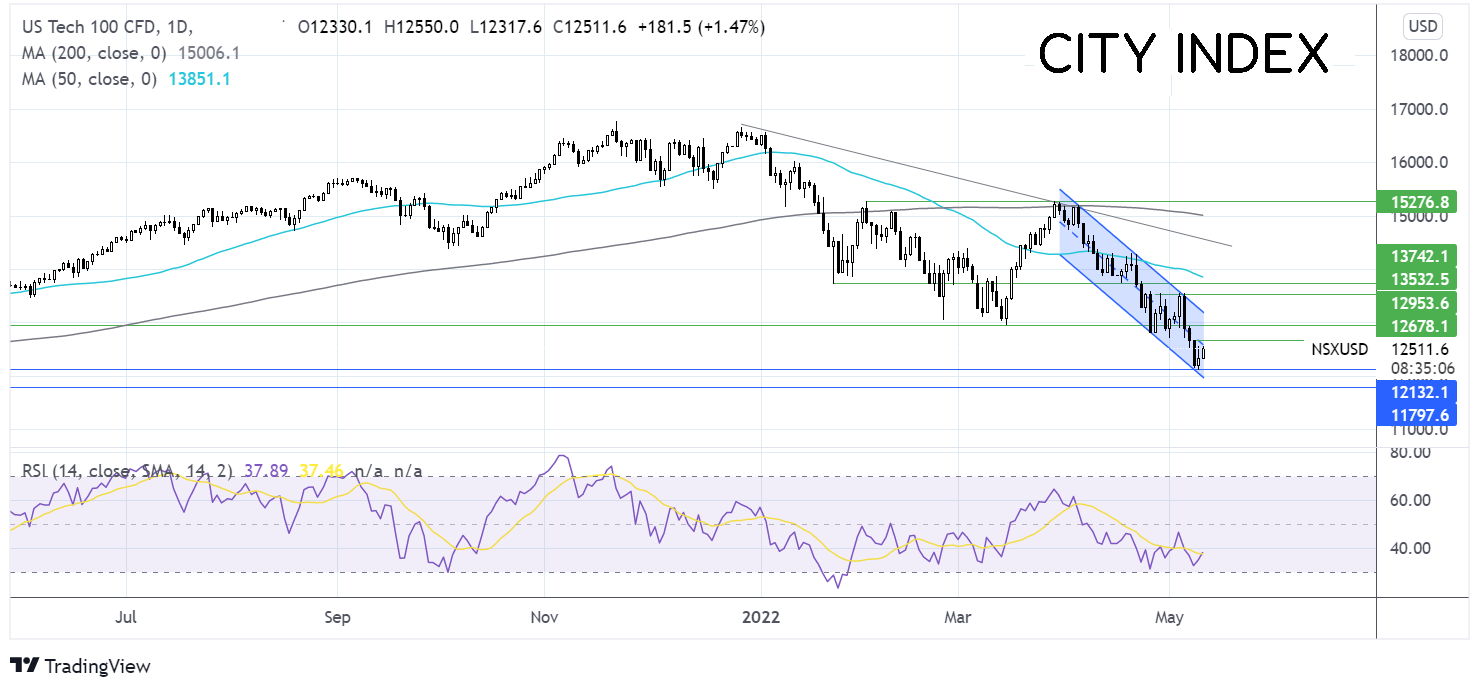
The Nasdaq has traded within a falling channel since the start of April, reaching a fresh 2022 low of 12100 yesterday before rebounding. The RSI remains out of oversold territory, suggesting that there is more downside to be had. Sellers need a move below 12100 to continue the bearish trend towards 11800, the late late November low. Buyers will be looking for a move over 12678, the weekly high, to bring 12950 into play.

FX markets USD rises
USD is rising after the inflation data boosts hawkish Fed bets. Inflation was higher than forecast and suggests that the Fed will need to keep acting firmly to rein in consumer prices that remain around a 4-decade high.
AUD/USD – is surging higher after Chinese inflation data revealed that consumer prices rose 2.1%. However, PPI fell to its lowest level in a year, giving the PBoC headroom to inject further stimulus into the slowing economy.
EUR/USD falls on USD strength after German CPI confirmed the 7.4% preliminary print and ECB Governor Christine Lagarde fueled a July rate hike expectations.
GBP/USD -0.23% at 1.2340
EUR/USD -0.15% at 1.0560
Oil rises after a steep selloff.
Oil is rebounding higher after falling around 10% in just two days, as supply concerns once again take center stage. The EU ban on Russian oil is looming large over the market ahead of a vote this week. While Hungary is still digging in its heels, an agreement could see the oil market, which is already tight, tighten further as oil flows slow.
The fact that the deal still hasn’t been agreed upon, but oil prices are rising anyway, suggests that firstly the recent selloff was overdone, and secondly, that the market is confident that Hungary will get onside sooner rather than later through exemptions, concessions, or some workaround.
Adding to the upbeat mood in the oil market was the prospect of further stimulus from Beijing. Factory gate inflation eased to a one-year low giving policymakers headroom for further stimulus. After all the disappointment regarding future demand amid the Chinese COVID lockdowns, the prospect of the additional stimulus was just the sugar rush that the oil market needed.
Before today oil prices had fallen sharply on demand concerns as China’s COVID lockdowns tightened amid fears of slowing global growth.
EIA data is expected later, and if API data is anything to go by, it could highlight demand concerns capping gains.
WTI crude trades +4.7% at $102.78
Brent trades +3.9% at $105.74
Looking ahead
15:30 EIA crude oil stockpile data
US futures
Dow futures -0.6 % at 32530
S&P futures -0.8% at 4065
Nasdaq futures -1.26% at 12468
In Europe
FTSE -0.1% at 7280
Dax +0.02% at 13630
Euro Stoxx -0.3% at 3612
Learn more about trading indices
Peak inflation may have passed, but don’t expect a quick drop
US stocks are falling after US inflation slowed for the first time since August last year but was still ahead of forecasts.
US CPI rose 8.3% YoY in April, down from 8.5% in March but above the 8.1% that was forecast. The data suggests that elevated consumer prices and the squeeze on households and businesses will persist, fueling bets of a hawkish Federal Reserve.
Whilst there is a good chance that inflation has peaked, it is not expected to drop away rapidly. Instead, given the breadth of price rises across the economy, combined with higher wages, the picture suggests that elevated inflation is here to stay.
The data supports the Fed’s more hawkish approach after a 50bp rate hike last week and most likely several more to come.
COVID lockdowns in China mean more supply chain disruptions, which, combined with high oil prices and resilient services demand, point to a long road to get inflation back towards the 2% target.
In corporate news:
More news on the stocks to watch
Where next for the Nasdaq?
The Nasdaq has traded within a falling channel since the start of April, reaching a fresh 2022 low of 12100 yesterday before rebounding. The RSI remains out of oversold territory, suggesting that there is more downside to be had. Sellers need a move below 12100 to continue the bearish trend towards 11800, the late late November low. Buyers will be looking for a move over 12678, the weekly high, to bring 12950 into play.
FX markets USD rises
USD is rising after the inflation data boosts hawkish Fed bets. Inflation was higher than forecast and suggests that the Fed will need to keep acting firmly to rein in consumer prices that remain around a 4-decade high.
AUD/USD – is rises higher after Chinese inflation data revealed that consumer prices rose 2.1%. However, PPI fell to its lowest level in a year, giving the PBoC headroom to inject further stimulus into the slowing economy.
EUR/USD falls on the stronger USD and after German CPI confirmed the 7.4% preliminary print and ECB Governor Christine Lagarde fueled a July rate hike expectations.
GBP/USD -0.23% at 1.2340
EUR/USD -0.15% at 1.0560
Oil rises after a steep selloff.
Oil is rebounding higher after falling around 10% in just two days, as supply concerns once again take center stage. The EU ban on Russian oil is looming large over the market ahead of a vote this week. While Hungary is still digging in its heels, an agreement could see the oil market, which is already tight, tighten further as oil flows slow.
The fact that the deal still hasn’t been agreed upon, but oil prices are rising anyway, suggests that firstly the recent selloff was overdone, and secondly, that the market is confident that Hungary will get onside sooner rather than later through exemptions, concessions, or some workaround.
Adding to the upbeat mood in the oil market was the prospect of further stimulus from Beijing. Factory gate inflation eased to a one-year low giving policymakers headroom for further stimulus. After all the disappointment regarding future demand amid the Chinese COVID lockdowns, the prospect of the additional stimulus was just the sugar rush that the oil market needed.
Before today oil prices had fallen sharply on demand concerns as China’s COVID lockdowns tightened amid fears of slowing global growth.
EIA data is expected later, and if API data is anything to go by, it could highlight demand concerns capping gains.
WTI crude trades +4.7% at $102.78
Brent trades +3.9% at $105.74
Learn more about trading oil here.
Looking ahead
15:30 EIA crude oil stock piles
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.