



US open: Stocks falls as earnings roll in & MSFT disappoints
Microsoft posts the slowest revenue growth in 6 years and warns of further weakness to come. The Nasdaq falls over 1% driven lower by tech jitters.
Share this:

US futures
Dow futures -0.62% at 33513
S&P futures -0.76% at 3985
Nasdaq futures -1.27% at 11695
In Europe
FTSE -0.37% at 7747
Dax -0.47% at 15029
Microsoft disappoints; Tesla is up next
US stocks are set to open lower, with the tech-heavy Nasdaq leading the charge lower after Microsoft earnings disappoint.
The Nasdaq futures have tumbled over 1%, snapping a two-day rally after Microsoft warned of slowing growth and as earnings reports from other big names such as 3M and chipmaker Texas Instruments fueled concerns over the health of corporate America, and over the outlook for the economy across the coming year.
Worries over weak earnings outlook, combined with recession fears after PMI data yesterday showed business activity slowed for a 7th straight month are weighing on risk sentiment.
Geopolitical concerns are also adding to the downbeat mood after Germany approved the export of German-made tanks, a move that could mark an escalation in the Russian war.
Corporate news
Microsoft is falling pre-market after mixed earnings. The tech giant posted revenue growth of just 2%, its slowest growth in 6 years. Revenue was $52.7 billion, missing forecasts of $53.17 as sales of Windows and Xbox related services slumped. Meanwhile, EPS fell 12% to $2.32 but beating consensus of $2.30.
Next up is Tesla which reports Q4 earnings after the close. The EV maker is expected to report adjusted EPS of $1.13 on sales of $24.7 billion. This is compared to $0.85c on sales of $17.7 billion in Q4 2021. However, the outlook will be very much in focus as competition heats up and Tesla has cut its prices.
Where next for the S&P500?
After pushing above the 200 sma, the lack of conviction in the move raises questions over the markets’ ability to push the price meaningfully above the multi-month falling trendline and break above 4040, the 2023 high. A move above 4040 is needed in order to attack 4145 the December high. Bears are testing the 100 sma at 3985, a decisive break below here could open the door to the 200 sma at 3945 and 3885, last week’s low.

FX markets – USD rises, AUD rises
The USD is rising, paring some losses in the previous session. While the greenback is ticking higher, it remains close to its 9-month low as the Fed is expected to slow the pace of rate hikes in the February FOMC meeting next week.
AUD/USD is rising, outperforming major pairs after Australian inflation jumped to a 30-year high in December, raising the prospect of further RBA rate hikes. Inflation jumped to 7.8% in Q4 up from 7.3%. The Aussie briefly pushed above 0.71 to a 5-month high.
EUR/USD is slipping on USD strength and despite encouraging eurozone data and hawkish ECB comments. German Ifo business sentiment hit a seven-month high in January as business morale brightens. The index rose to 90.2, up from 88.6 in December and adds to mounting evidence not a recession in the eurozone's largest economy could be milder than initially feared.
AUS/USD +0.63% at 0.7088
EUR/USD -0.2% at 1.0868
Oil slips ahead of inventory data
Oil prices are inching lower, extending gains from the previous session following a rise in US crude oil inventories and as recession fears overshadow optimism surrounding China’s reopening.
Hopes of a strong rebound in China's demand have helped oil prices rally across recent weeks. However, a continuation of this rally really depends on how quickly China's demand bounces back this quarter. Separately, PMI data showing that US business activity contracted for a 7th straight month is raising concerns over a recession in the US, the world’s largest consumer of oil.
In the meantime, the focus has been on inventory data from the API, which showed that US oil stockpiles raised by 3.4 million barrels in the week ending January 20th; this was well up from the 1 million forecast. EIA stockpile data is due later this afternoon.
WTI crude trades -0.3% at $80.00
Brent trades at -0.25% at $85.95
Looking ahead
15:00 BoC rate decision
15:30 EIA crude oil inventories
US futures
Dow futures -0.62% at 33513
S&P futures -0.76% at 3985
Nasdaq futures -1.27% at 11695
In Europe
FTSE -0.37% at 7747
Dax -0.47% at 15029
Learn more about trading indices
Microsoft disappoints; Tesla is up next
US stocks are set to open lower, with the tech-heavy Nasdaq leading the charge lower after Microsoft earnings disappoint.
The Nasdaq futures have tumbled over 1%, snapping a two-day rally after Microsoft warned of slowing growth and as earnings reports from other big names such as 3M and chipmaker Texas Instruments fueled concerns over the health of corporate America and over the outlook for the economy across the coming year.
Worries over weak earnings outlook, combined with recession fears after PMI data yesterday showed business activity slowed for a 7th straight month are weighing on risk sentiment.
Geopolitical concerns are also adding to the downbeat mood after Germany approved the export of German-made tanks, a move that could mark an escalation in the Russian war.
Corporate news
Microsoft is falling pre-market after mixed earnings. The tech giant posted revenue growth of just 2%, its slowest growth in 6 years. Revenue was $52.7 billion, missing forecasts of $53.17 as sales of Windows and Xbox related services slumped. Meanwhile, EPS fell 12% to $2.32 but beating consensus of $2.30.
Next up is Tesla which reports Q4 earnings after the close. The EV maker is expected to report adjusted EPS of $1.13 on sales of $24.7 billion. This is compared to $0.85c on sales of $17.7 billion in Q4 2021. However, the outlook will be very much in focus as competition heats up and Tesla has cut its prices.
Where next for the S&P500?
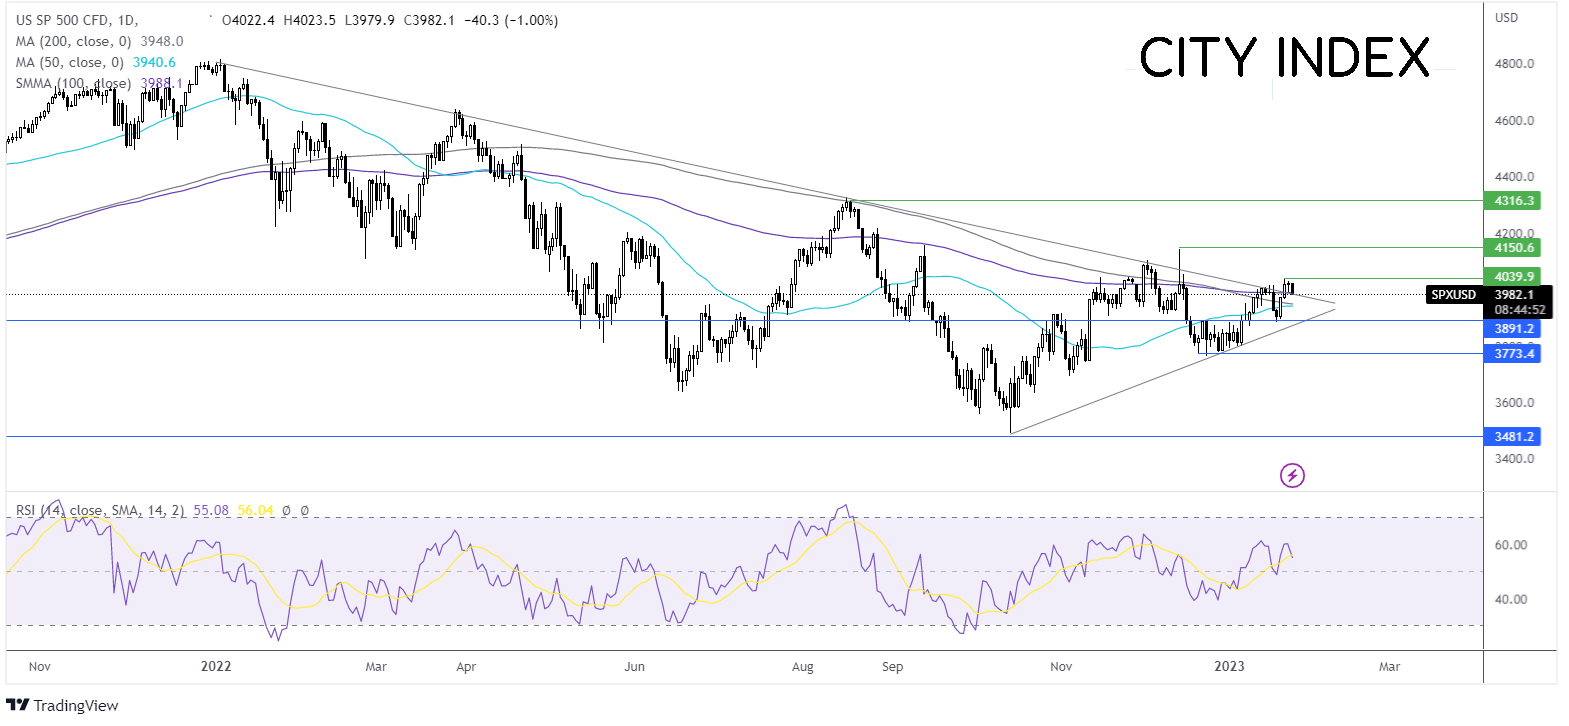
After pushing above the 200 sma, the lack of conviction in the move raises questions over the markets’ ability to push the price meaningfully above the multi-month falling trendline and break above 4040, the 2023 high. A move above 4040 is needed in order to attack 4145 the December high. Bears are testing the 100 sma at 3985, a decisive break below here could open the door to the 200 sma at 3945 and 3885, last week’s low.
FX markets – USD rises, AUD rises
The USD is rising, paring some losses in the previous session. While the greenback is ticking higher, it remains close to its 9-month low as the Fed is expected to slow the pace of rate hikes in the February FOMC meeting next week.
AUD/USD is rising, outperforming major pairs after Australian inflation jumped to a 30-year high in December, raising the prospect of further RBA rate hikes. Inflation jumped to 7.8% in Q4 up from 7.3%. The Aussie briefly pushed above 0.71 to a 5-month high.
EUR/USD is slipping on USD strength and despite encouraging eurozone data and hawkish ECB comments. German Ifo business sentiment hit a seven-month high in January as business morale brightens. The index rose to 90.2, up from 88.6 in December and adds to mounting evidence not a recession in the eurozone's largest economy could be milder than initially feared.
AUS/USD +0.63% at 0.7088
EUR/USD -0.2% at 1.0868
Oil slips ahead of inventory data
Oil prices are inching lower, extending gains from the previous session following a rise in US crude oil inventories and as recession fears overshadow optimism surrounding China’s reopening.
Hopes of a strong rebound in China's demand have helped oil prices rally across recent weeks. However, a continuation of this rally really depends on how quickly China's demand bounces back this quarter. Separately, PMI data showing that US business activity contracted for a 7th straight month is raising concerns over a recession in the US, the world’s largest consumer of oil.
In the meantime, the focus has been on inventory data from the API, which showed that US oil stockpiles raised by 3.4 million barrels in the week ending January 20th; this was well up from the 1 million forecast. EIA stockpile data is due later this afternoon.
WTI crude trades -0.3% at $80.00
Brent trades at -0.25% at $85.95
Learn more about trading oil here.
Looking ahead
15:00 BoC rate decision
15:30 EIA crude oil inventories
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
You can trade with FOREX.com by following these four easy steps:
- Open an account, or log in if you’re already a customer
- Search for the instrument you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.