



US open yields ease stocks rise Nike misses
US futures point higher as yields ease back from yesterday's 14 month high. US - China relations set off to a frosty start and Nike misses on sales.
Share this:

US futures
Dow futures +0.03% at 32900
S&P futures +0.1% 3928
Nasdaq futures +0.15%% at 12820
In Europe
FTSE -1% at 6700
Dax -0.81% at 14621
Euro Stoxx -0.5% at 3839
Learn more about trading indices
Stocks set for higher open as bond bears pause for breath
After a steep selloff particularly in tech stocks, US stocks are looking to open higher as bond yields eased down from yesterday’s 14 month high. However, the cyclical dominant Dow Jones is the only index on course to end the week in positive territory.
There could be heightened volatility given quadruple witching expires at the end of the day.
Stocks in focus
Nike – trades -2.6% pre-market after releasing mixed results. Nike reported higher Q3 profits, although sales fell short of forecasts, dropping 10% YoY. Sales will be hit by ongoing congestion at ports in the US and amid ongoing store closures in Europe. However, Nike did see digital sales continue to pick up momentum. EPS 90c vs 76c on Revenue $10.36 billion versus $11.02 billion expected.
FedEx – trades 5% higher announcing that its quarterly profit jumped more than expected on higher prices and surging volume, boosted by the pandemic fueled rise in e-commerce deliveries during the holiday season.
Where next for Fedex share price?
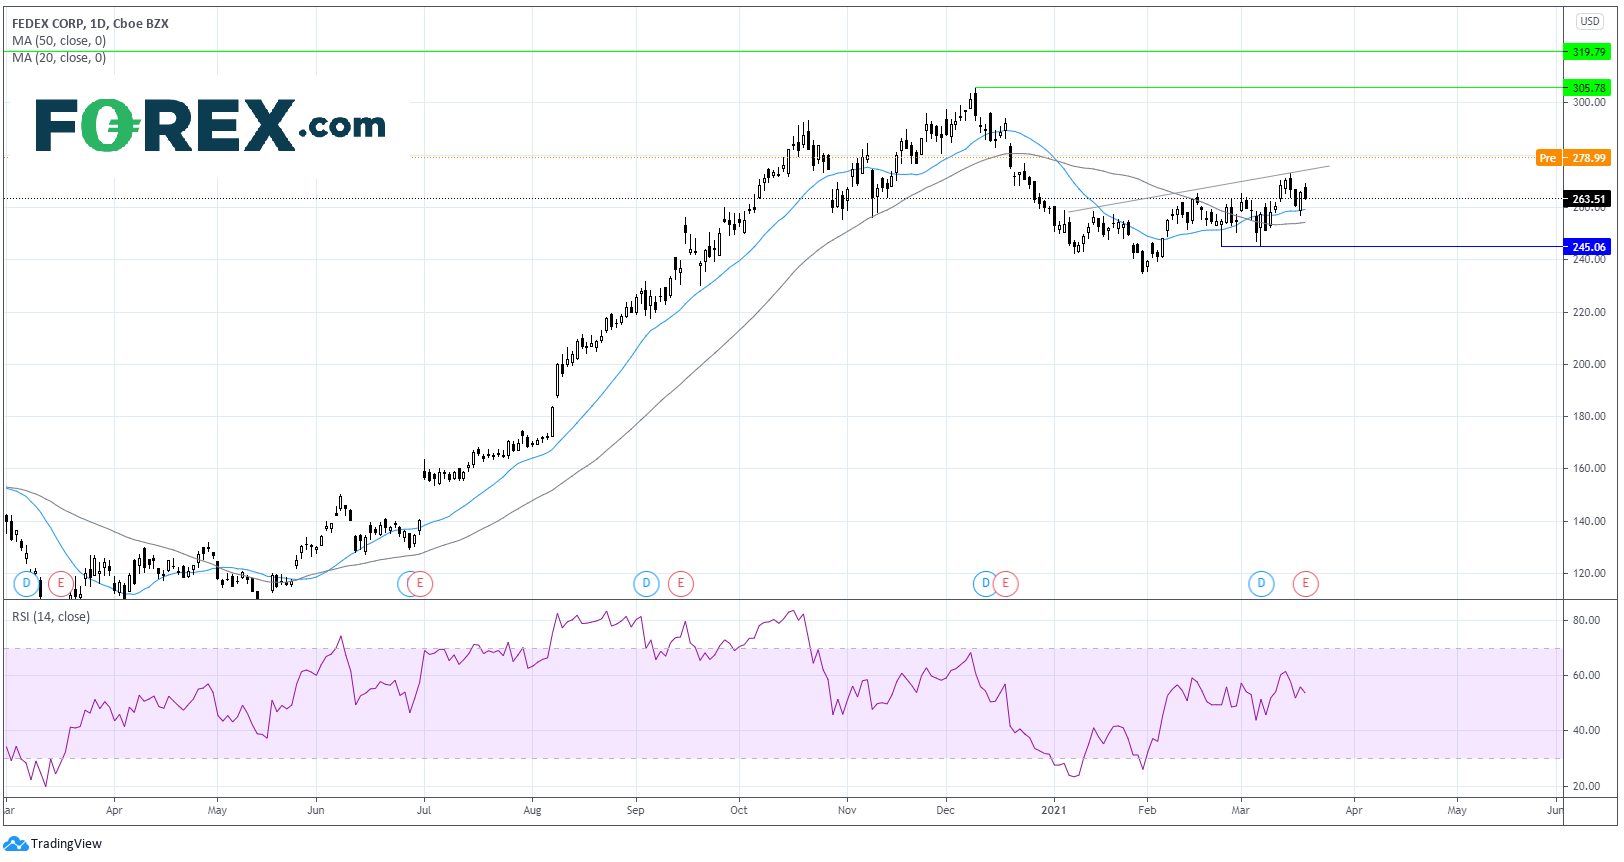
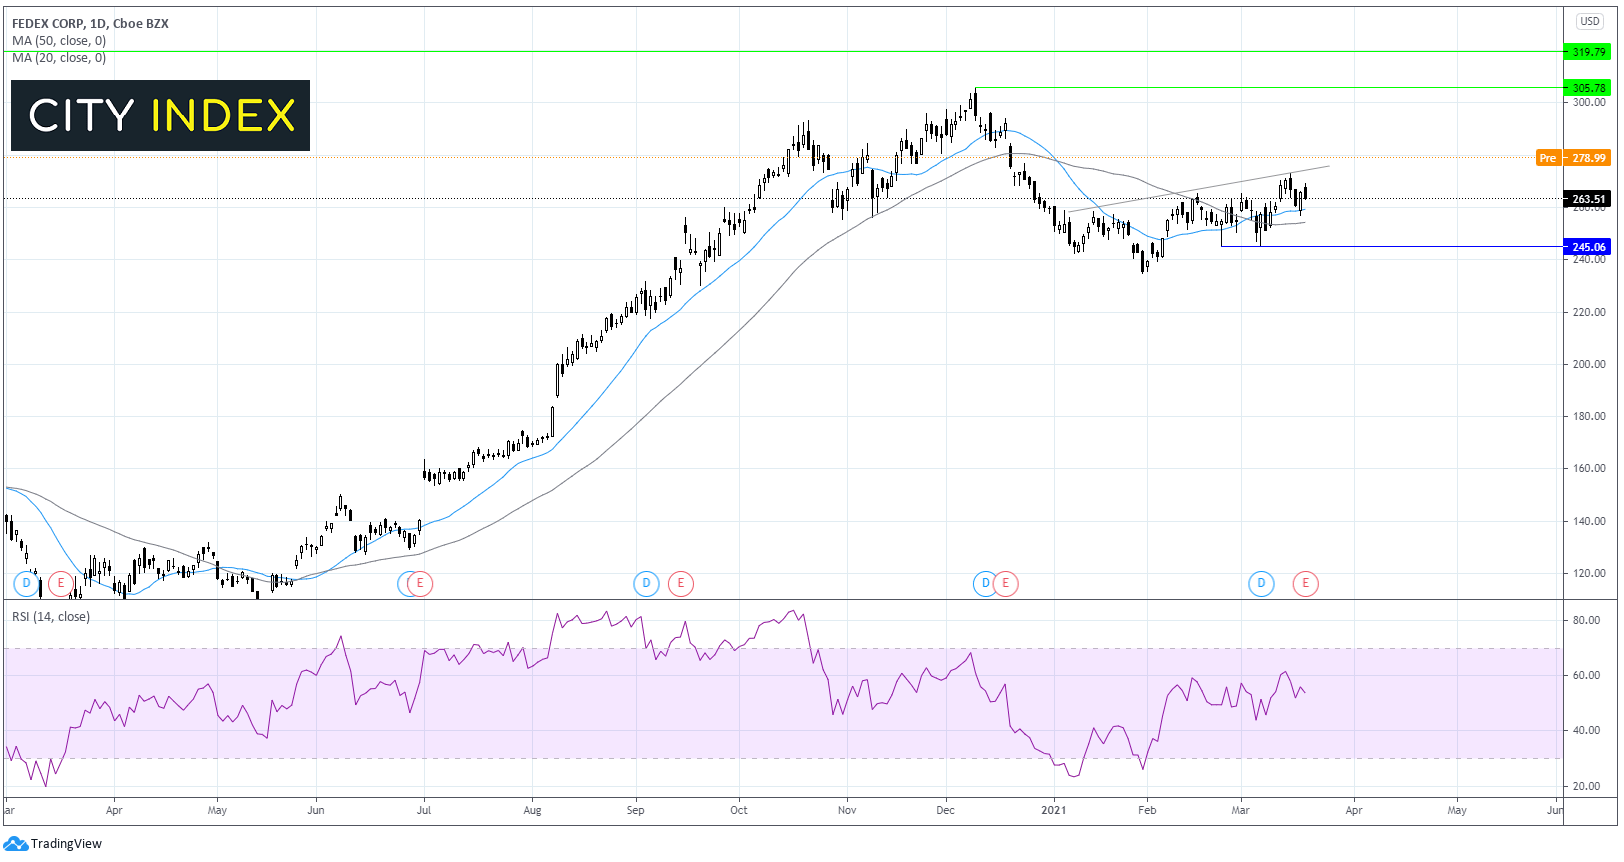
After trending sharply lower through December and January, hitting a low of 235.00, FedEx has been crawling higher.
Today’s 5% bounce on the open has seen the share price jump over its ascending trendline dating back to early January. It also trades well over its 20 & 50 sma. The 20 sma recently crossed above the 50 sma in a bullish signal.
Furthermore, the RSI is supportive of further gains. With this bullish break out, buyers could target December’s high 300.00.
Immediate support is seen at 275.00 the ascending trendline resistance turned support, ahead of the 20 sma at 260.00.
US – China relations have a frosty start
The first face to face meeting a between President Biden and Chinese officials in Alaska set off on the wrong foot with the two sides hurling insults. Expectations were low for the meeting with China standing firm that issues in Xinjiang, Hong Kong and Taiwan are domestic affairs.
The tense tone to the talks helped send Chinese equities lower with A-shares index tanking 3%.
The two-day talks are set to conclude today.
BoJ ends a week of central banks
The BoJ famed for its decade long assert purchase programme hinted that it may be losing faith in its approach to avoid deflation. The BoJ abandoned its pledge to buy 60 trillion yen worth of bonds instead looking to other tools.
This was the final central bank meeting of the week which saw Fed and BoE stay pat on policy whilst Bank of Russia, Brazil and Turkey gave hawkish surprises.
FX – GBP/USD shrugs off record PSNB
FX markets are muted on Friday trading within familiar ranges. After a weaker start the US Dollar is creeping higher, even a treasury yields slip lower.
GBP/USD has given up earlier gains after public sector net borrowing came in at an eye opening £19.1 billion in February, the highest ever amount in February, but was still less than the £21 billion forecast. Elevated covid spending and falling tax receipts were to blame.
GBP/USD 0% at 1.3927
EUR/USD trades -0.1% at 1.1902
Oil extends losses for a fifth straight session
Oil is steadying after a 7% sell off in the previous session – the largest one day decline for the commodity since April. Concerns over rising covid cases in Europe and a renewed lockdown in France unnerved investors, despite falling covid cases in the US the world’s largest oil consumer. The stronger US Dollar added to oil’s woes. However, the price rebounded of the 50 sma and has retaken $60.00.
The Baker Hughes rig count is due later today.
US crude trades +0.3% at $60.25
Brent trades +0.3% at $63.29
Learn more about trading oil here.
The complete guide to trading oil markets
Looking ahead
17:00 Baker Hughes Rig Count
US futures
Dow futures +0.08% at 32911
S&P futures +0.2% 3923
Nasdaq futures +0.3%% at 12780
In Europe
FTSE -1.1% at 6705
Dax -0.81% at 14721
Euro Stoxx -0.5% at 3846
Learn more about trading indices
Stocks set for higher open as bond bears pause for breath
After a steep selloff particularly in tech stocks, US stocks are looking to open higher as bond yields eased down from 14 month high. However, the cyclical dominant Dow Jones is on course to end the week in positive territory.
There could be heightened volatility given quadruple witching expires at the end of the day.
Stocks in focus
Nike – trades -2.6% pre-market after releasing mixed results. Nike reported higher Q3 profits, although sales fell short of forecasts, dropping 10% YoY. Sales will be hit by ongoing congestion at ports in the US and amid ongoing store closures in Europe. However, Nike did see digital sales continue to pick up momentum. EPS 90c vs 76c on Revenue $10.36 billion versus $11.02 billion expected.
FedEx – trades 5% higher announcing that its quarterly profit jumped more than expected on higher prices and surging volume, boosted by the pandemic fueled rise in e-commerce deliveries during the holiday season.
Where next for Fedex share price?
After trending sharply lower through December and January, hitting a low of 235.00, FedEx has been crawling higher.
Today’s 5% bounce on the open has seen the share price jump over its ascending trendline dating back to early January. It also trades well over its 20 & 50 sma. The 20 sma recently crossed above the 50 sma in a bullish signal.
Furthermore, the RSI is supportive of further gains. With this bullish break out, buyers could targe December’s high 300.00.
Immediate support is seen at 275.00 the ascending trendline resistance turned support, ahead of the 20 sma at 260.00.
US – China relations have a frosty start
The first face to face meeting a between President Biden and Chinese officials in Alaska set off on the wrong foot with the two sides hurling insults. Expectations were low for the meeting with China standing firm that issues in Xinjiang, Hong Kong and Taiwan are domestic affairs.
The tense tone to the talks helped send Chinese equities lower with A-shares index tanking 3%.
The two-day talks are set to conclude today.
BoJ
The BoJ famed for its decade long assert purchase programme hinted that it may be losing faith in its approach to avoid deflation. The BoJ abandoned its pledge to buy 60 trillion yen worth of bonds instead looking to other tools.
This was the final central bank meeting of the week which saw Fed and BoE stay pat on policy whilst Bank of Russia, Brazil and Turkey gave hawkish surprises.
FX – GBP/USD shrugs off record PSNB
FX markets are muted on Friday trading within familiar ranges. After a weaker start the US Dollar is creeping higher, even a treasury yields slip lower.
GBP/USD has given up earlier gains after public sector net borrowing came in at an eye opening £19.1 billion in February, the highest ever amount in February, but was still less than the £21 billion forecast. Elevated covid spending and falling tax receipts were to blame.
GBP/USD 0% at 1.3927
EUR/USD trades -0.1% at 1.1902
Oil extends losses for a fifth straight session
Oil is steadying after a 7% sell off in the previous session – the largest one day decline for the commodity since April. Concerns over rising covid cases in Europe and a renewed lockdown in France unnerved investors, despite falling covid cases in the US the world’s largest oil consumer. The stronger US Dollar added to oil’s woes. However, the price rebounded of the 50 sma and has retaken $60.00.
The Baker Hughes rig count is due later today.
US crude trades +0.3% at $60.25
Brent trades +0.3% at $63.29
Learn more about trading oil here.
The complete guide to trading oil markets
Looking ahead
17:00 Baker Hughes Rig Count

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.