




Weekly equities forecast: Tesla, Lloyds & Barclays earnings preview
S&P 500 and the FTSE fell last week after the market pushed back Fed rate cut expectations and as geopolitical tensions hurt risk sentiment. Look ahead; US core PCE will be a key focus next week, as well as earning season with Tesla earnings and UK bank's earnings.
Share this:

- Tesla reports Q1 earnings on Tuesday, April 23, after the close.
- Lloyds reports on Wednesday, April 24, ahead of the open
- Barclays reports on Thursday, April 25, ahead of the open.
The S&P 500 fell 0.6% across the week after Federal Reserve speakers, including Fed Chair Jerome Powell, dampened rate cut expectations and as geopolitical tensions weighed on market sentiment. Fed Chair Powell warned that rate cuts may need to be delayed, and other Fed policymakers said that there was no urgency for the bank to loosen monetary policy.
Looking ahead, next week sees the focus on US GDP data and core PCE, the Fed’s preferred gauge for inflation, for clues over the future path for US interest rates. A strong economy and hotter inflation could raise questions over the Fed’s ability to cut rates.
Meanwhile, earnings season will ramp up with earnings from Tesla, PepsiCo, UPS, Boeing, and American Airlines, among many others.
Tesla Q1 earnings
The EV maker posted a decline in Q1 deliveries to 386,810. This marked an 8.5% year-on-year decline amid declining EV demand despite price cuts across the quarter. Declining demand, intensifying competition, and a challenging macro backdrop of high rates for longer are setting Tesa up for a disappointing quarter.
EPS is expected to be $0.55, down from $0.85c in the same quarter a year earlier, on revenue of $22.73 billion, down from $23.33 billion a year earlier and $25.17 billion in the previous quarter.
The results come after Tesla announced it will cut 10% of the global workforce to cut costs and drive efficiencies. Tesla appears to be moving away from the idea of bringing the EV to the average driver and instead focusing on chasing the Robo-taxi dream. However, no developments are expected until after the summer.
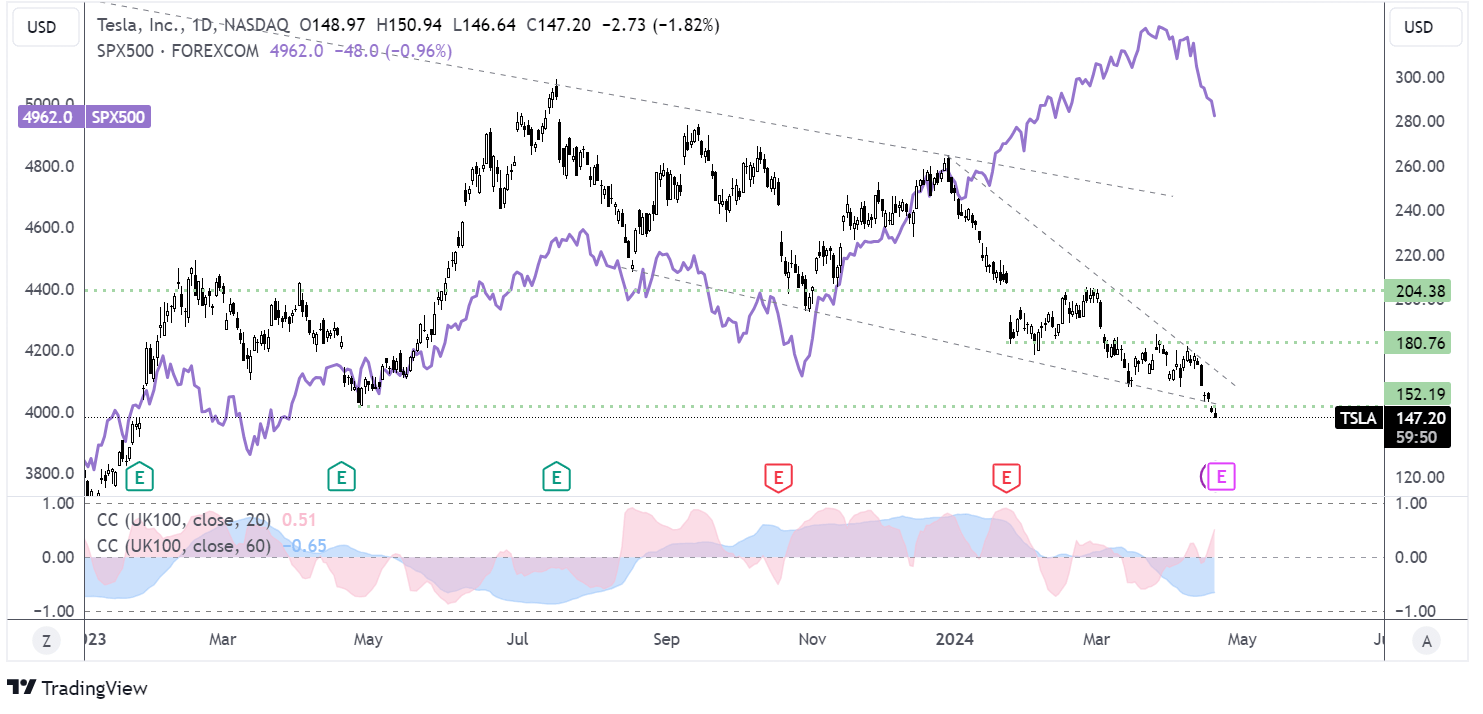
The stocks have traded down 35% this year, considerably underperforming the S&P 500.
The chart shows that while Tesla has been trading inversely to the S&P 500, this has flipped, and the correlation has turned positive over the past week.
FTSE look ahead
The FTSE fell over 1.3% last week as risk sentiment fell, hitting risk assets across financial markets. The index was also pulled lower by falling oil majors as oil prices dropped 4% and after mixed data, with inflation cooling by less than expected and retail sales stalling. The market is trying to assess when the BoE could start to cut rates. August or September could be the start of lower rates.
Looking ahead, UK bank's earnings and PMI data will be key drivers, as well as any geopolitical developments in the Middle East.
Lloyds Q1 results
Lloyds is the first of the big UK banks to report earnings. Net interest income is expected to fall compared to the same period last year, dropping to 2.93% from 3.22%. While rates were being hiked this time last year, the focus is now on when rates will be cut, which explains the fall in NII.
Loan defaults will be another focus. Bad loan charges are expected to be in the region of £280 million. With the UK recession scheduled to have been short-lived, there could be signs of resilient borrowers. Looking ahead, loan volumes could start to recover as the housing market shows tentative signs of improving.
Investors will watch out for further comments surrounding the FCA investigation into motor financing. Lloyds has set aside £450 million to deal with the charges.
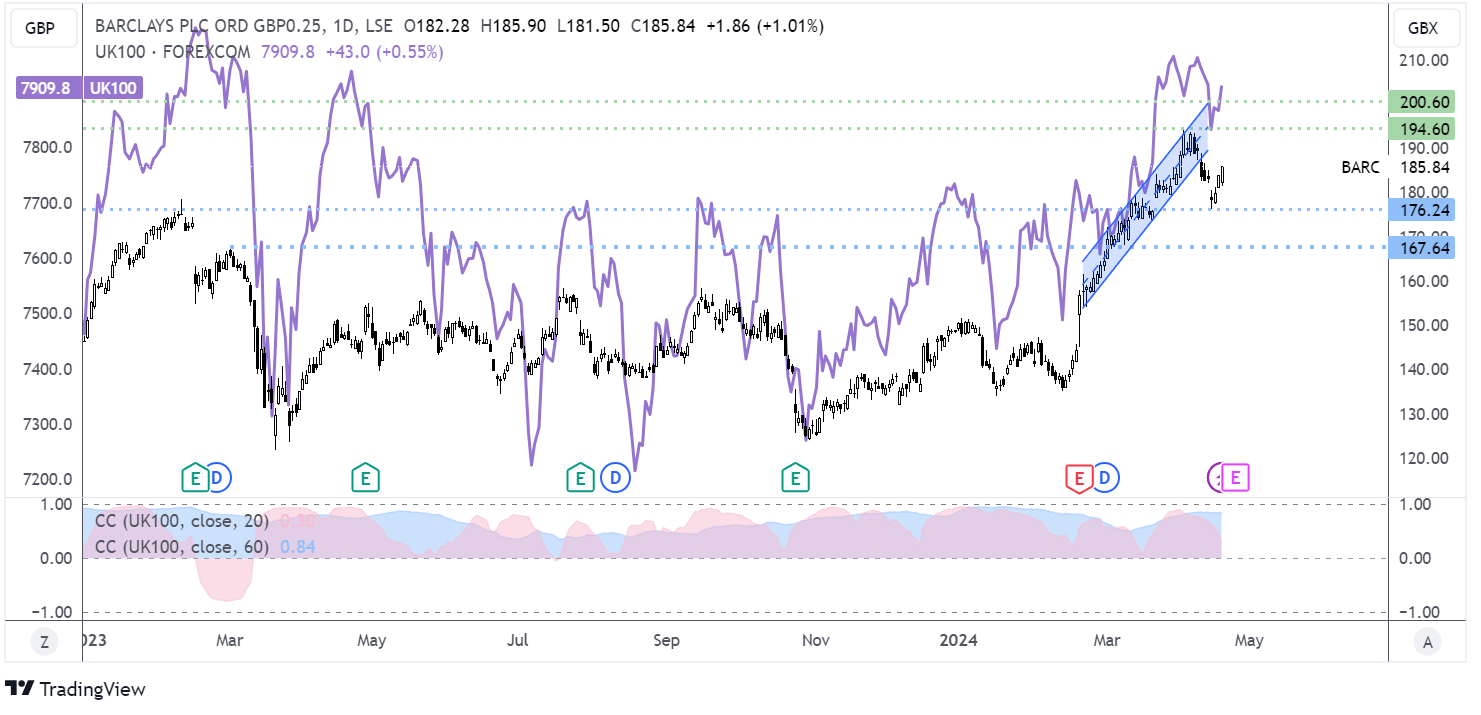
The chart highlights the strong correlation between the FTSE and Lloyd's share price.
Barclays Q1 results
Barclays and its sector peers trade near a 6-year high ahead of earnings, jumping 20% after announcing a reorganization in February, so the bar is high. Revenue estimates have been trimmed in the run-up to the release, and earnings are likely to be lower than the bumper 2023 numbers. Barclays is expected to report a pre-tax profit of £2.2 billion, down from £2.6 billion reported in Q1 2023.
In February, Barclays said it aimed to save £1 billion by making the bank more efficient. The cost-cutting comes alongside the restructuring, which plans to emphasize its investment banking arm less. However, this division could rebound if US banks' earnings are considered lead indicators.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
GBP/USD, Dow Jones Forecast: Key Technical Scenarios to Watch
GBP/USD and the Dow Jones are approaching critical technical levels amid earning optimism, Fed rate hike expectations, US-Iran developments, and persistent geopolitical risks.

The U.S. Dollar Is Rising Again and Nasdaq Is Feeling It
Nasdaq, the U.S. Dollar Index and Federal Reserve expectations are driving market sentiment ahead of a pivotal FOMC meeting. Razan Hilal, StoneX Market Analyst, explains how rising expectations for a hawkish Federal Reserve, persistent U.S.-Iran tensions and key technical levels on the U.S. Dollar Index could influence currencies, equities and precious metals in the weeks ahead.
US Dollar and Nasdaq Forecast: Fed, Microsoft, Meta, and Iran Talks in Focus
The US Dollar Index (DXY) continues to hold above the 101.00 mark, reinforcing its bullish structure, while the Nasdaq remains capped below the 29,000 resistance and its June-July consolidation range, reflecting cautious risk appetite ahead of the Federal Reserve's policy decision and major earnings releases on Wednesday.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.