




What to Expect Tesco H1 Results
Tesco is due to report H1 results on Wednesday, first under new boss Ken Murphy
Share this:
When:
October 7thExpectations:
• EPS 7.5p, a 17.2% YoY rise on revenue of £31.7 billion.
• Pre- tax profits are due to be in the region of £944 million.
Covid revenues vs costs
Sales across all supermarkets, Tesco included are expected to be strong owing to lockdown and surging demand. Online sales are expected to be particularly strong. However, rising revenues have been offset by rising costs associated with the pandemic. Tesco recently hired 16,000 more staff for its online business.
Expectations are for those additional cost headwinds to be abating now. Meanwhile second quarter like for like sales are expected to be +6.3`% higher, excluding fuel and the Bookers wholesale arm.
Competition heating up
Competition feels like it is starting to heat up. Firstly, Marks and Spencer have teamed up with Ocado giving them an online presence and making them a force to be reckoned with. Secondly, and probably more concerning for Tesco is the development of the digital offering at Aldi, which now offers click and collect. Whilst Tesco was taking market share away from Aldi earlier in the year, this is looking like it won’t be trend that continues, particularly when economic conditions become more challenging and consumers could look more to to budget supermarkets such as Aldo and Lidl
New CEO new strategy?
These will be the first results under new boss Ken Murphy, who walked into the job just days ago. Here the key for the market will be outlook. Whilst it is clearly far too early for a strategic unveiling, any hints of changes to strategy will be lapped up.
Then there is Brexit – how could we forget? The Brexit issue continues to linger. It would appear that the broad consensus in the market currently is that the UK and the EU might have a bare bones trade agreement in place by early November. But that’s most certainly not in the bag. The disruption of a no deal Brexit would be considerable, whilst a drop sterling could push up the price of imported goods. Investors remain cautious.
Special Dividend
Finally, any update on the sales of the Asian business will be listened for carefully. Whilst the £5 billion proceeds were initially being ear marked for a special dividend, given the climate maybe Tesco would prefer to re-invest the funds?
What analysts say?
Of the 21 analysts covering the stock:
• Buy 14
• Hold 6
• Sell 1
Tesco share price
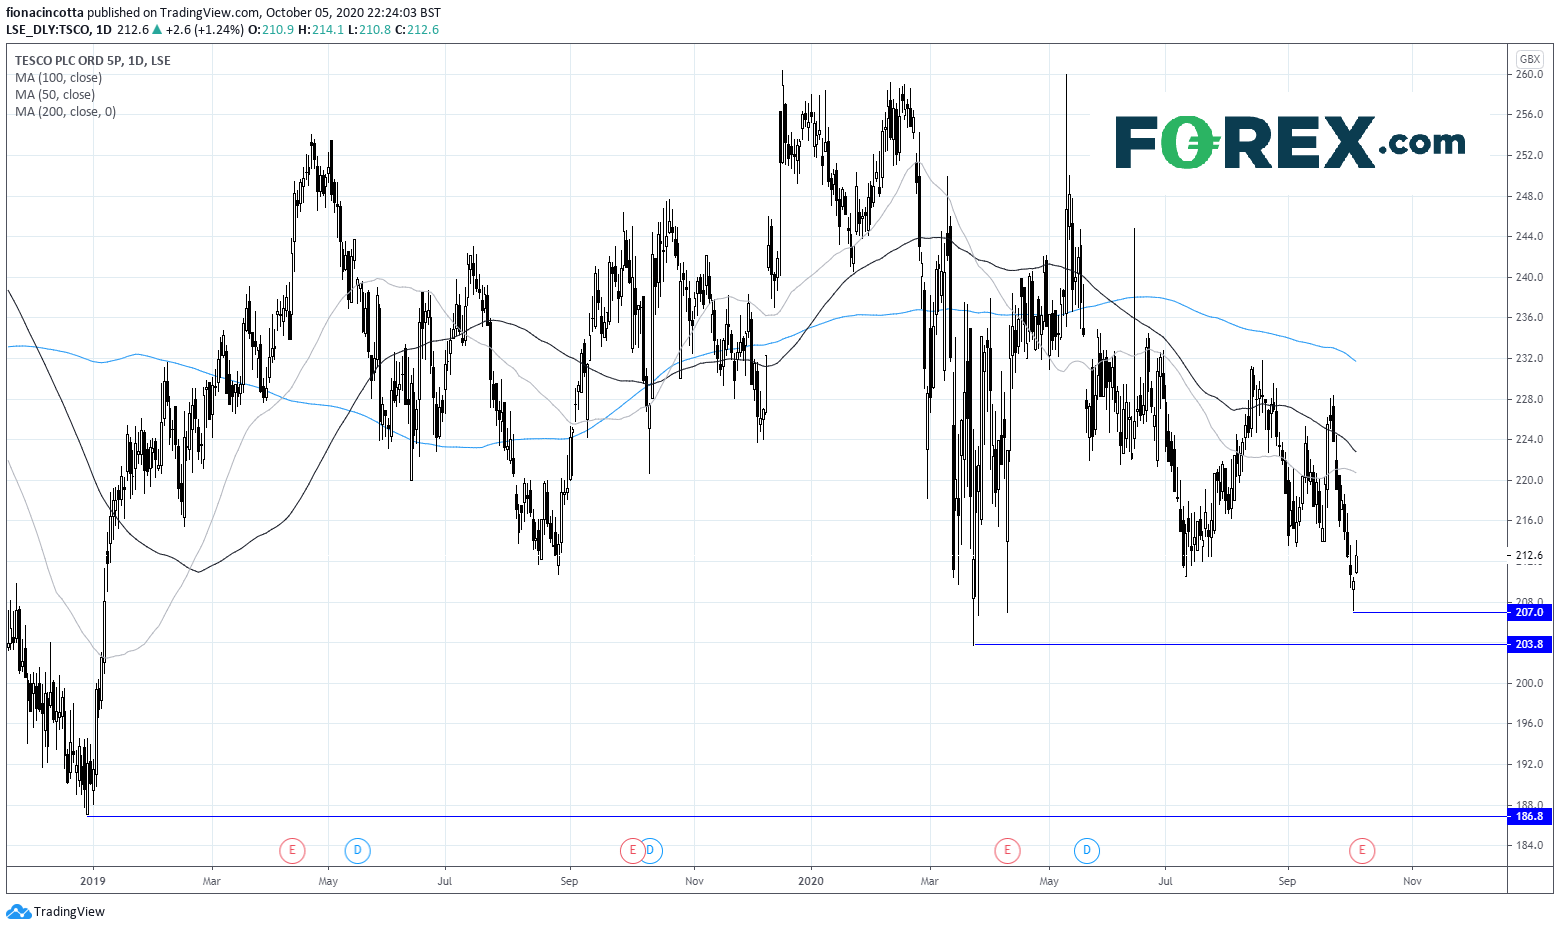
Tesco’s share price saw spectacular, if short lived recovery from its mid-March low of 203p to a 250p peak. However, the surge lacked follow through, and the stocks has been in a downtrend since mid-April.
Tesco trades firmly below its 50, 100 and 200 DMA and below its descending trendline suggesting that there could be more weakness to come.
Support can be seen at Friday’s low of 207p , prior to the mid-March 203p low A break below here could see the stock look towards Dec 2018 lows of 185p . On the upside resistance can be seen at 220/2p 50 & 100 DMA, prior to 230p 200 DMA & horizontal support.
Tesco Chart
When:
October 7thExpectations:
• EPS 7.5p, a 17.2% YoY rise on revenue of £31.7 billion.
• Pre- tax profits are due to be in the region of £944 million.
Covid revenues vs costs
Sales across all supermarkets, Tesco included are expected to be strong owing to lockdown and surging demand. Online sales are expected to be particularly strong. However, rising revenues have been offset by rising costs associated with the pandemic. Tesco recently hired 16,000 more staff for its online business.
Expectations are for those additional cost headwinds to be abating now. Meanwhile second quarter like for like sales are expected to be +6.3`% higher, excluding fuel and the Bookers wholesale arm.
Competition heating up
Competition feels like it is starting to heat up. Firstly, Marks and Spencer have teamed up with Ocado giving them an online presence and making them a force to be reckoned with. Secondly, and probably more concerning for Tesco is the development of the digital offering at Aldi, which now offers click and collect. Whilst Tesco was taking market share away from Aldi earlier in the year, this is looking like it won’t be trend that continues, particularly when economic conditions become more challenging and consumers could look more to to budget supermarkets such as Aldo and Lidl
New CEO new strategy?
These will be the first results under new boss Ken Murphy, who walked into the job just days ago. Here the key for the market will be outlook. Whilst it is clearly far too early for a strategic unveiling, any hints of changes to strategy will be lapped up.
Then there is Brexit – how could we forget? The Brexit issue continues to linger. It would appear that the broad consensus in the market currently is that the UK and the EU might have a bare bones trade agreement in place by early November. But that’s most certainly not in the bag. The disruption of a no deal Brexit would be considerable, whilst a drop sterling could push up the price of imported goods. Investors remain cautious.
Special Dividend
Finally, any update on the sales of the Asian business will be listened for carefully. Whilst the £5 billion proceeds were initially being ear marked for a special dividend, given the climate maybe Tesco would prefer to re-invest the funds?
What analysts say?
Of the 21 analysts covering the stock:
• Buy 14
• Hold 6
• Sell 1
Tesco share price
Tesco’s share price saw spectacular, if short lived recovery from its mid-March low of 203p to a 250p peak. However, the surge lacked follow through, and the stocks has been in a downtrend since mid-April.
Tesco trades firmly below its 50, 100 and 200 DMA and below its descending trendline suggesting that there could be more weakness to come.
Support can be seen at Friday’s low of 207p , prior to the mid-March 203p low A break below here could see the stock look towards Dec 2018 lows of 185p . On the upside resistance can be seen at 220/2p 50 & 100 DMA, prior to 230p 200 DMA & horizontal support.
Tesco Chart
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?

USD/JPY unwind accelerates as GPIF headlines spark yen buying
Japanese assets are rallying after the government floated the prospect of the GPIF investing more heavily at home. While the proposal could have significant implications for global capital flows, it does not yet change the broader forces driving Japanese bond yields and USD/JPY.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.