



Why the DXY break is different this time
The recent escalation in the trade war accompanied by a further deterioration in global growth has all but confirmed the Federal Reserve will cut rates by 25bps at its next meeting, Thursday, September 19 at 4.00am AEST.
Share this:

The recent escalation in the trade war accompanied by a further deterioration in global growth has all but confirmed the Federal Reserve will cut rates by 25bps at its next meeting, Thursday, September 19 at 4.00am AEST.
The market is already 100% priced for this outcome and for another 25bp cut to be delivered by the Fed before year-end. Another 65bp of cuts are priced for 2020. The temptation for the Fed must be to follow the lead of the RBNZ and to deliver a 50bp cut before year-end, thereby front-loading its stimulus.
Despite the now higher probability that the Fed commenced an extended easing cycle rather than a “mid-cycle” adjustment on August 1, the U.S. dollar index (DXY) has continued to appreciate, resulting in a correlation breakdown between the DXY and interest rates.
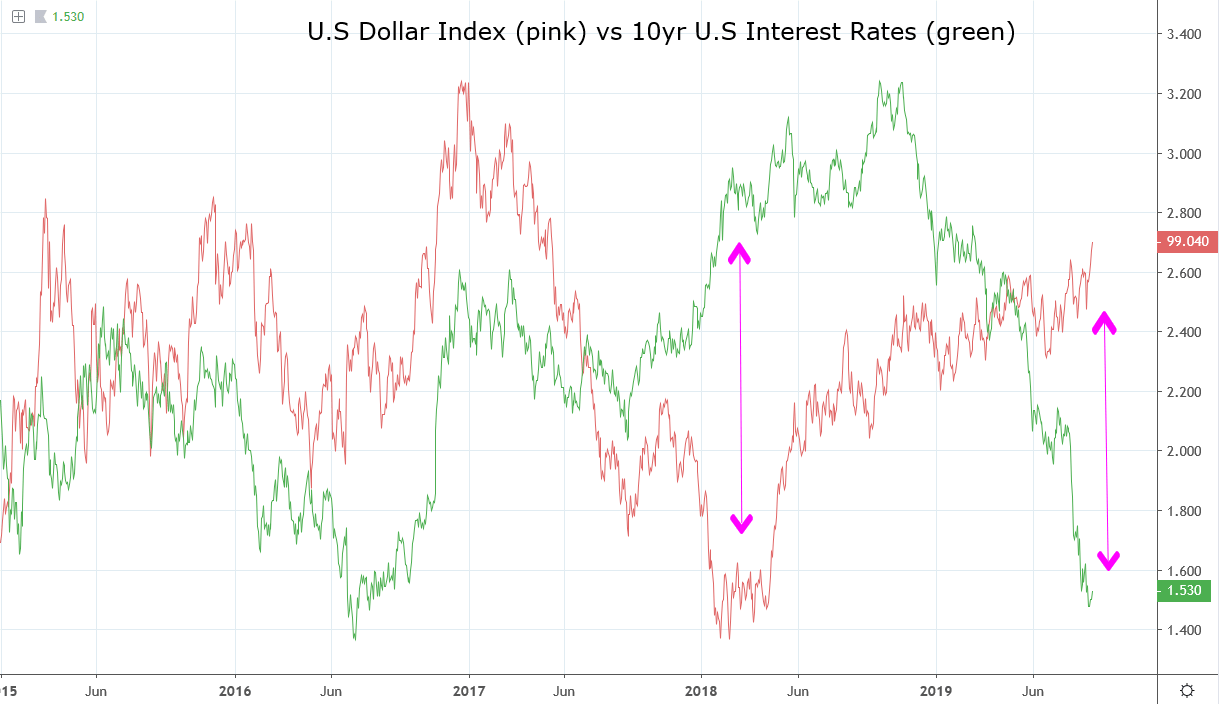
As can be viewed in the chart below, the DXY and 10-year U.S. interest rates are usually positively correlated, which means they mostly travel in the same direction. In early 2018, there was a breakdown in this relationship as investors shunned the U.S. dollar after Trump's tax cuts sparked fears of the “twin deficits” (large government deficits occurring at the same time of trade deficits).
In mid-2019, the correlation has again broken down. Interest rates have moved significantly lower, while at the same time the U.S. dollar is trading at two-year highs. In short, ongoing demand for U.S. dollars from a variety of sources, including safe-haven demand, has outweighed the effect of lower interest rates. How long this breakdown can continue is unknown and one of the reasons why the technical picture below is important.
After a handful of failed attempts in recent months, the DXY has posted its second consecutive daily close above the top of trend channel resistance. As such, providing the DXY holds above the top of the trend channel in coming sessions, the DXY can now look towards the next upside targets at 100.50 and then 103.50.
On the downside, dips towards 98.80/60 are likely to be well supported with only a break and close below 98.30 suggesting the latest breakout attempt has failed.
Source Tradingview. The figures stated are as of the 3rd of September 2019. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
Disclaimer
TECH-FX TRADING PTY LTD (ACN 617 797 645) is an Authorised Representative (001255203) of JB Alpha Ltd (ABN 76 131 376 415) which holds an Australian Financial Services Licence (AFSL no. 327075)
Trading foreign exchange, futures and CFDs on margin carries a high level of risk and may not be suitable for all investors. The high degree of leverage can work against you as well as for you. Before deciding to invest in foreign exchange, futures or CFDs you should carefully consider your investment objectives, level of experience, and risk appetite. The possibility exists that you could sustain a loss in excess of your deposited funds and therefore you should not invest money that you cannot afford to lose. You should be aware of all the risks associated with foreign exchange, futures and CFD trading, and seek advice from an independent financial advisor if you have any doubts. It is important to note that past performance is not a reliable indicator of future performance.
Any advice provided is general advice only. It is important to note that:
- The advice has been prepared without taking into account the client’s objectives, financial situation or needs.
- The client should therefore consider the appropriateness of the advice, in light of their own objectives, financial situation or needs, before following the advice.
- If the advice relates to the acquisition or possible acquisition of a particular financial product, the client should obtain a copy of, and consider, the PDS for that product before making any decision.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.