




AUD/USD mulls 64c breakout, US yields hint at swing high post Fed
With US yields lower and hinting at a swing high, the relationship between AUD/USD and the AU-US 2-year spread appear to be back on talking terms. And that could bode well for AUD/USD bulls if US yields continue to fall in line with my bias.
Share this:
View related analysis:
- AUD/USD Forecast: FOMC, AU Jobs to Wake the Aussie Up From Its Lull?
- USD/JPY Hits Speed Bump at 150 Ahead of BOJ and FOMC, ASX to Open Lower
- Gold's Surge is Leaving Traders for Dust: Matt's 2-Minute Take
View related analysis:
While the Fed downgraded growth and upgraded their inflation forecast in light of Trump’s tariffs, they opted for a ‘wait and see’ approach regarding rates by keeping them at 3.9% for 2025, unchanged from their December forecasts. If anything, I felt they may have trimmed some easing out of the equation for this year, so from that angle it could be seen as dovish for the Fed to retain 50bp of cuts on the table.
- The Fed held rates steady at 4.25% - 4.5% as widely expected
- Lowered their 2025 growth outlook to 1.7% (down from 2.1%) and 2026 GDP to 1.8% (down from %)
- Core PCE for 2025 increased to 2.7% (2.5% prior)
- PCE increased to 2.8% (2.5% prior)
- Fed Funds rate unchanged at 3.9% for 2025 and 3.4% for 2026
- Balance sheet runoff to be slowed from April
Wall Street traders took the dovish tilt as good news, with the S&P 500, Nasdaq and Dow Jones were all up on the day. Although volatility was contained. Gold continued to a new high, as it doesn’t seem to know how to do much else these days.
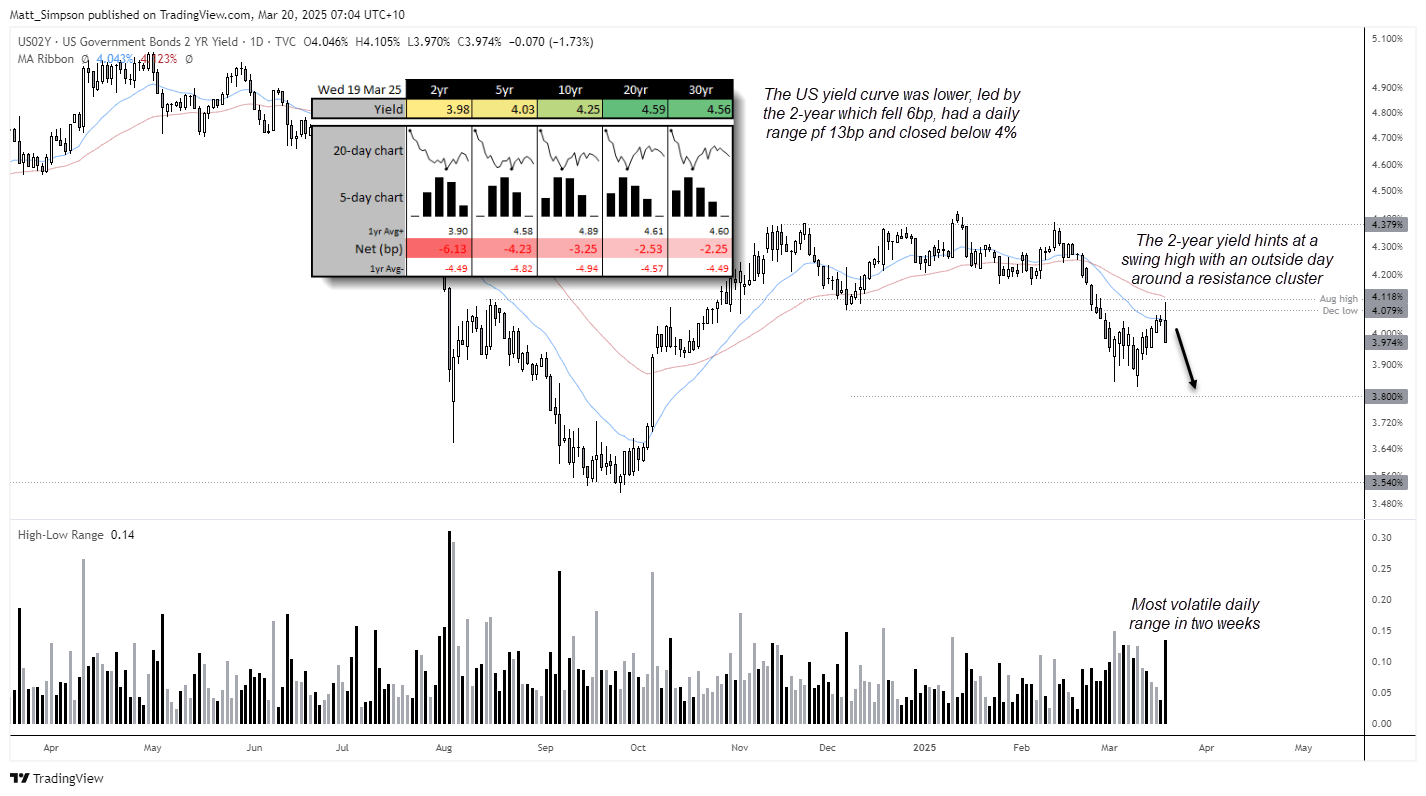
It was the most volatile day for the 2-year yield in two weeks, with its bearish outside day spanned 13bp to close -6bp lower and back beneath 4%. The recovery from 3.83% stalled around the December low, August high and 50-day EMA, further adding to the case that a swing high on yields may have been seen.
AUD/USD technical analysis
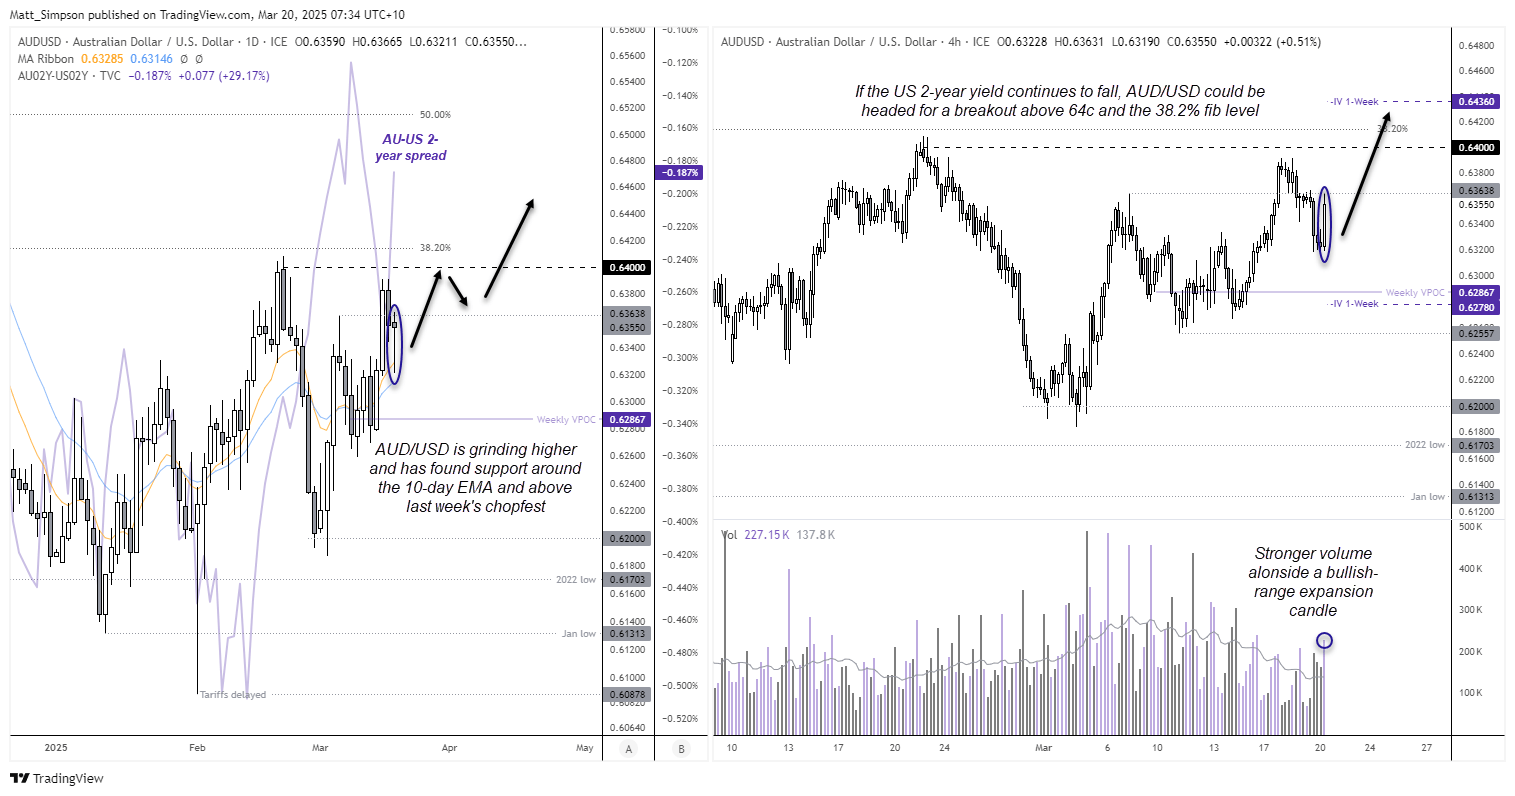
While AUD/USD closed flat following the Fed meeting, its lower wick on the day shows demand around the 10 and 20-day EMAs, around last week’s choppy range. And as messy as price action may have been, it is grinding higher since its rebound from 62c.
Yield differentials appear to be making a comeback, with the AU-US 2-year rising alongside AUD/USD this week. The relationship between the two was weak heading into last week, but they appear to now be back on talking terms again.
It should be noted that the differential is rising due to a drop in US yields as opposed to a rise in AU yields, but the bearishness of the US 2-year chart does look appealing enough to at least support AUD/USD over the near term.
The 4-hour chart shows a strong bullish bar accompanied with rising volume, which suggest a swing low around 0.6320. Bulls could seek dips within that candles range in anticipation of a move up to 64c. But for a break above it strong enough to clear the 38.2% Fibonacci level, we likely need a strong AU employment report alongside a continued selloff on the US 2-year yield.
Economic events in focus (AEDT)
The Bank of England (BOE) are likely to become the third major central bank to hold rates this week. Sticky inflation gives little room for cuts, even if there are two dissenters within the ranks – which likely leaves it 7-2 in favour of no action today. Still, some estimate that there could be as many as three cuts this year.
You can read my thoughts on Australia’s employment situation in the AUD/USD outlook article linked above, but in a nutshell it is likely to remain robust and not allow RBA doves to jeer for an imminent RAB rate cut. If it comes in strong enough, it could help AUD/USD head for 64c again.
- 00:00 – Japanese Public Holiday (Vernal Equinox)
- 08:45 – New Zealand Q4 GDP
- 11:30 – Australian Employment (Feb)
- 12:00 – PBOC Loan Prime Rate
- 18:00 – UK Earnings, Claimant Count, Employment Change
- 19:30 – SNB Interest Rate Decision (25bp cut expected)
- 23:00 – BOE Interest Rate Decision, MPC Votes (No Change Expected)
- 23:30 – BOE Governor Bailey Speaks
- 23:30 – US Jobless Claims, Philly Fed Manufacturing
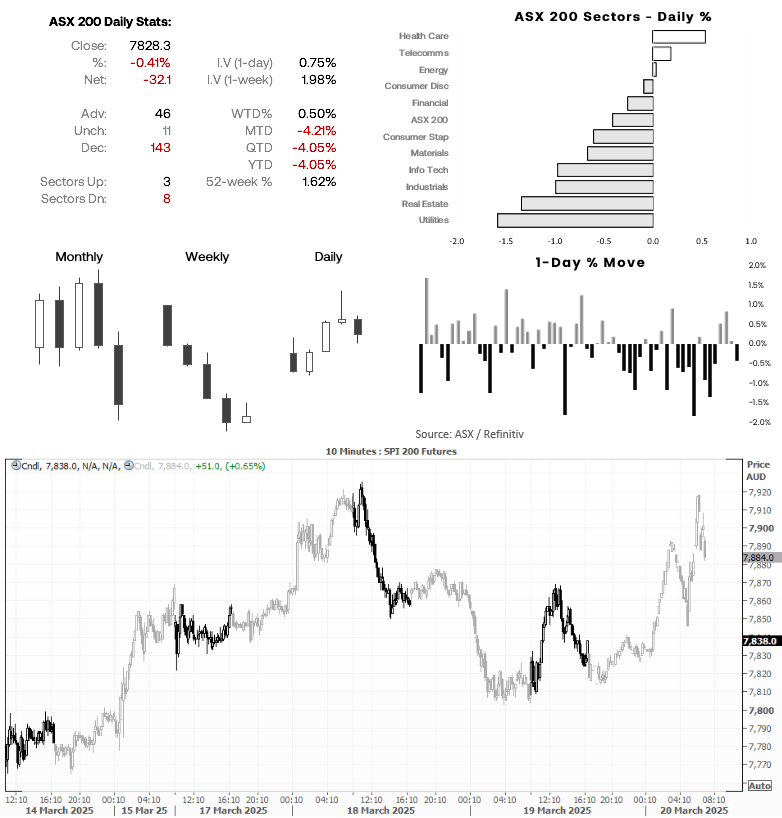
ASX 200 at a glance
- The ASX 200 snapped a 3-day winning streak,
- Info tech is the weakest the 10 ASX sectors this past four weeks, down -19.3% while utilities is the only ASX sector to gain at 4%
- The bounce on Wal Street helped ASX 200 (SPI 200) futures rise 0.5% overnight, which points to a positive open for the ASX cash index today
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/CAD Outlook: Loonie left behind as US CPI looms
USD/CAD's sharp rebound has coincided with widening US–Canada interest rate differentials. With US CPI approaching and bullish momentum building, another breakout may be on the cards.
Japanese Yen Outlook: EUR/JPY and GBP/JPY Outbid USD/JPY
The Japanese yen starts the week mixed, with EUR/JPY and GBP/JPY showing bullish potential while USD/JPY remains stuck in a rut.
USD Majors, Gold, Bitcoin, Equity Indices Weekly Technical Outlook 11 9 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

The information on this web site is not targeted at the general public of any particular country. It is not intended for distribution to residents in any country where such distribution or use would contravene any local law or regulatory requirement. The information and opinions in this report are for general information use only and are not intended as an offer or solicitation with respect to the purchase or sale of any currency or CFD contract. All opinions and information contained in this report are subject to change without notice. This report has been prepared without regard to the specific investment objectives, financial situation and needs of any particular recipient. Any references to historical price movements or levels is informational based on our analysis and we do not represent or warranty that any such movements or levels are likely to reoccur in the future. While the information contained herein was obtained from sources believed to be reliable, author does not guarantee its accuracy or completeness, nor does author assume any liability for any direct, indirect or consequential loss that may result from the reliance by any person upon any such information or opinions.
Futures, Options on Futures, Foreign Exchange and other leveraged products involves significant risk of loss and is not suitable for all investors. Losses can exceed your deposits. Increasing leverage increases risk. Spot Gold and Silver contracts are not subject to regulation under the U.S. Commodity Exchange Act. Contracts for Difference (CFDs) are not available for US residents. Before deciding to trade forex, commodity futures, or digital assets, you should carefully consider your financial objectives, level of experience and risk appetite. Any opinions, news, research, analyses, prices or other information contained herein is intended as general information about the subject matter covered and is provided with the understanding that we do not provide any investment, legal, or tax advice. You should consult with appropriate counsel or other advisors on all investment, legal, or tax matters. References to FOREX.com or GAIN Capital refer to StoneX Group Inc. and its subsidiaries. Please read Characteristics and Risks of Standardized Options.