



Can US PMI surveys and employment reports sway bonds? The Week Ahead
Last week we noted that bond yields could trump economic data this week, and for the most part they did. We can also extend that comment into next week, especially if they continue to retreat and loosen their grip on bearish sentiment and allow risk assets to rebound. Highlights in next week’s calendar include the NFP and ISM PMI reports, RBA and RBNZ monetary policy meetings, the quarterly Tankan survey for Japan and Canada’s employment report.
Share this:
Can US PMI surveys and employment reports sway bonds? The Week Ahead
Last week we noted that bond yields could trump economic data this week, and for the most part they did. We can also extend that comment into next week, especially if they continue to retreat and loosen their grip on bearish sentiment and allow risk assets to rebound. With China on holiday all next week the trading volumes may be lower than usual (and the faltering gold market may find it has fewer buyers to support it than usual). With that said, notable economic events in next week’s calendar include the monthly Nonfarm payroll and ISM PMI reports, RBA and RBNZ monetary policy meetings, the quarterly Tankan survey for Japan and Canada’s employment report.
The week that was:
- US bond yields continued to surge in the first half of the week with the long end of the curve leading the way (otherwise known as a bear steepener, as bond prices at the long end were falling the fastest)
- A multitude of concerns including higher oil prices, hawkish Fed comments, expectations of higher-for-longer Fed rates and rising risks of a US government shutdown fuelled the bond rout and sent the US dollar to YTD highs
- Kashkari hinted at a 60% chance of a soft landing for the US economy, a backing for another 25bp hike with a risk that they may need to hike further
- Global bonds followed the US and the rise of Australian yields saw the RBA’s cash rate futures imply a 96% chance of a 25bp hike by June 2024
- Yet what could have simply been profit-taking triggered a pullback on the US dollar and yields on Thursday, which allowed risk assets such as Wall Street indices and AUD/USD recoup some losses from their cycle lows
- The Swiss National Bank (SNB) reiterated their commitment to no further tightening in their quarterly bulletin, saying that their “significant tightening of monetary policy over recent quarters” is reigning in inflation
- The DAX fell to a 6-month low following another weak Ifo business sentiment report
The week ahead (calendar):
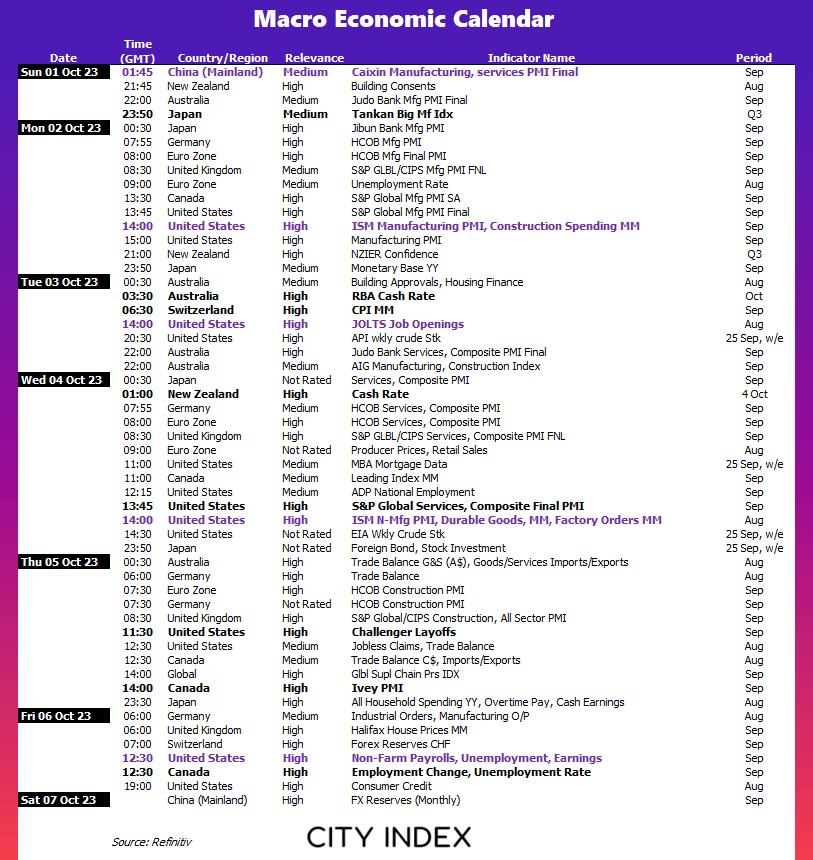
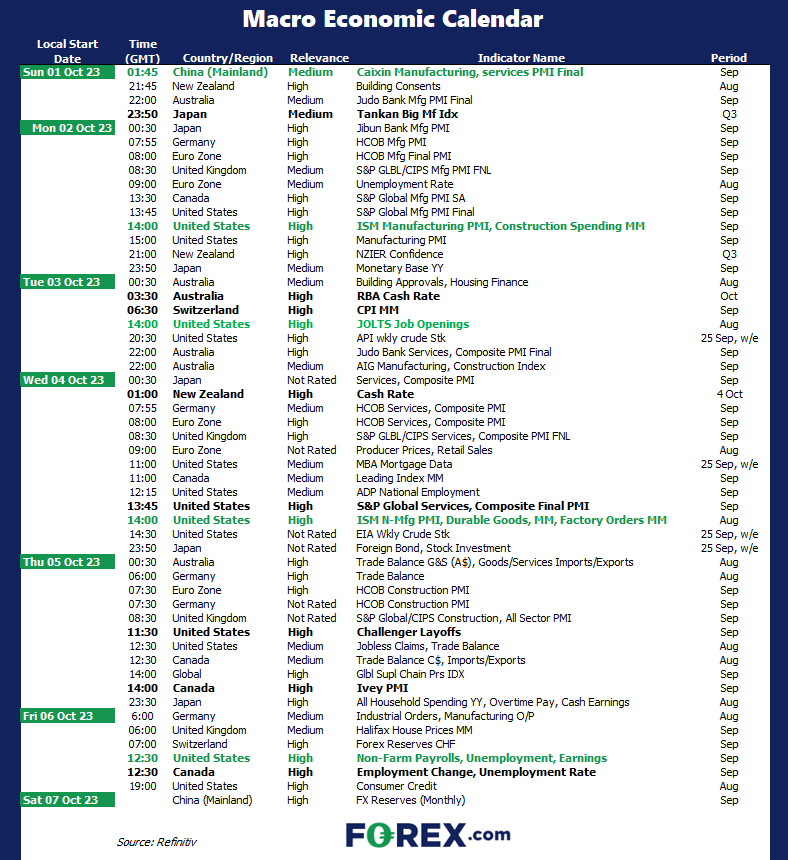
This content will only appear on City Index websites!
Earnings This Week
Look at the corporate calendar and find out what stocks will be reporting results in Earnings This Week.
The week ahead (key events and themes):
- USD strength, bond rout
- US employment (Nonfarm payroll, JOLTS job openings, jobless claims)
- ISM manufacturing, services PMI
- Canadian employment data
- Japan Tankan
- RBA and RBNZ cash rate decisions
- China PMIs (manufacturing, services, composite – Caixin)
- China public holiday (all week)
US data: (ISMs, PMIs, NFP, jobless claims, job layoffs and openings)
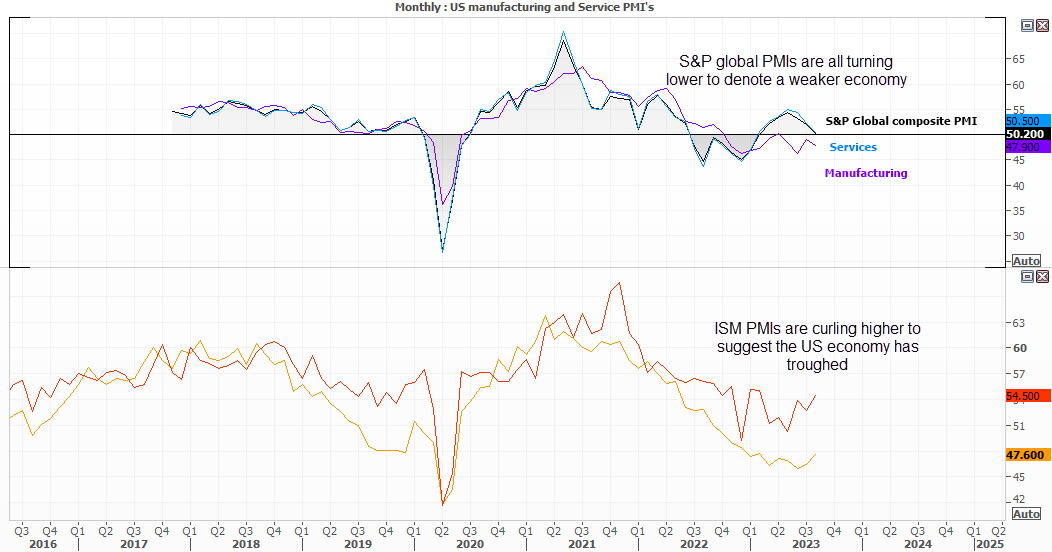
The key US data point can be split into two main groups; employment and business surveys. S&P global release their final revisions of their PMIs, all of which are pointing lower to show a soft economy. The Composite and services are on the cusp of joining manufacturing in contraction (below 50) which is at odds with the ISM surveys. The ISM services expanded at its fastest pace in six months whilst ISM manufacturing is curling higher and contracting at a slower pace. So which one is correct?
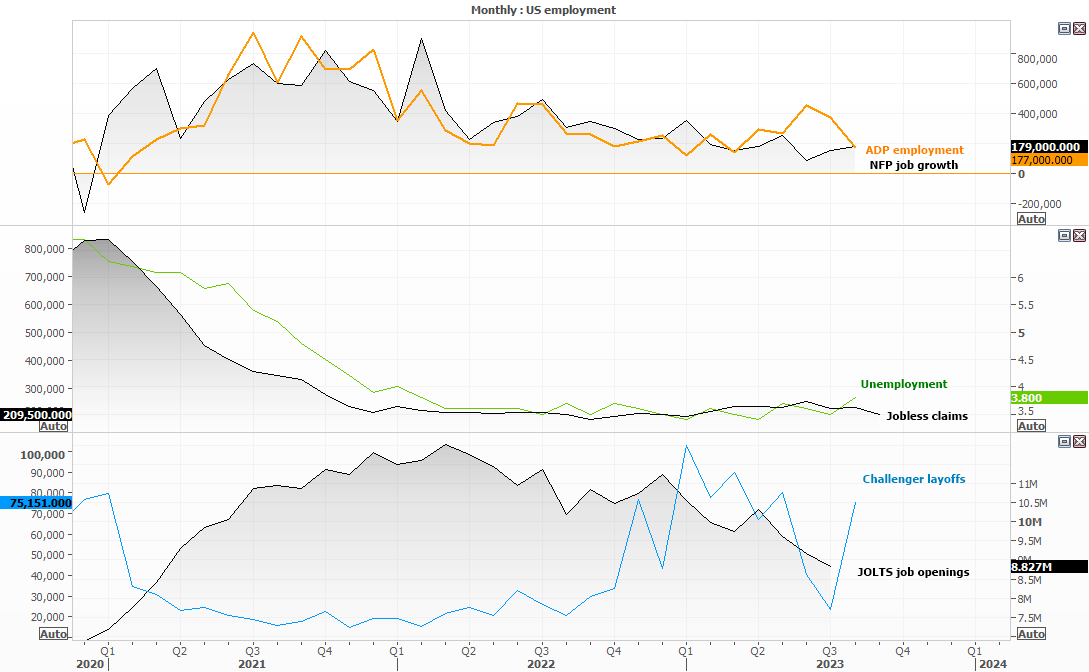
The US employment situation is also providing slightly missed signals. NFP Job growth is trending lower yet remains at healthy ‘expansive’ levels, and whilst unemployment has curled high it remains historically low at 3.8%. Job openings fell to a 48-month low, yet significantly elevated relative to its long-term average, and whilst layoffs rose over 50k last month it still pales in comparison to the times of covid. Overall, employment is remains tight but slightly softer and we’re going to have to see some surprisingly soft figures to bring the ‘higher for longer’ narrative into question. And if employment remains firm but business surveys pick up, if anything it could further fuel the bond rout and send yields and the US dollar higher.
Market to watch: EURUSD, USD/JPY, WTI Crude Oil, Gold, S&P 500, Nasdaq 100, Dow Jones
RBA and RBNZ cash rate decisions
It’s unlikely we’ll see the RBA or RBNZ change their policy next week, although it will be the first meeting for the new RBA governor Michell Bullock. It’s difficult to say whether she’ll make a mark, given there is only the joint statement of the board members to go off of. But perhaps it leaves more wriggle room for it being less of a ‘cut and paste’ job.
With markets having now prices in a 96% chance of a 25bp RBA hike by June thanks to rising bond yields, it will be interesting to see if the RBA somehow tip their hat towards it and give away another “further tightening” clue. But with household spending and retail sales pointing lower, it’s difficult to justify a hike this year.
The RBNZ are likely to change policy given their forecasts have essentially confirmed the peak rate a 5.5%.
Market to watch: AUD/USD, NZD/USD, AUD/NZD, NZD/JPY, AUD/JPY, ASX 200
China PMIs (manufacturing, services, composite – Caixin)
With China’s PMIs being released over the weekend and China on a public holiday all next week, the data really serves for sentiment outside of the region. And is the case with most data out of China this year, it likely requires an upside surprise for it to be considered a surprise at all.
Market to watch: USD/CNH, USD/JPY, S&P 500, Nasdaq 100, Dow Jones, VIX, AUD/JPY
Canadian employment data
The Bank of Canada (BOC) may have another hike up their sleeve given the return of inflation, at already elevated levels. And another hot employment report could tip them over the edge. That it is released alongside US nonfarm payrolls makes USD/CAD a candidate for unhealthy levels of volatility, but traders can also consider crosses such as CAD/JPY for a potentially cleaner move.
Market to watch: USD/CAD, CAD/JPY, NZD/CAD, AUD/CAD
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Bond yields and crude call the shots for ASX 200
The ASX 200 has rallied on 93% of occasions this year when Australian three-year bond yields have fallen at least five basis points. With crude prices also plunging, the latest breakout has history on its side.
USD/CAD Analysis: Is the Loonie Losing Momentum?
The week is just getting underway, and one of the most relevant themes driving market moves remains the growing weakness around the Canadian dollar. This can be clearly seen in recent USD/CAD price action, with the pair gaining more than 0.6% over the last two trading sessions, highlighting that the CAD has once again lost ground against the U.S. dollar.
Australian Dollar Outlook: AUD/USD Bears Eye March Low as US CPI Looms
Australian Dollar Outlook: AUD/USD Bears Eye March Low as US CPI Looms
The information on this web site is not targeted at the general public of any particular country. It is not intended for distribution to residents in any country where such distribution or use would contravene any local law or regulatory requirement. The information and opinions in this report are for general information use only and are not intended as an offer or solicitation with respect to the purchase or sale of any currency or CFD contract. All opinions and information contained in this report are subject to change without notice. This report has been prepared without regard to the specific investment objectives, financial situation and needs of any particular recipient. Any references to historical price movements or levels is informational based on our analysis and we do not represent or warranty that any such movements or levels are likely to reoccur in the future. While the information contained herein was obtained from sources believed to be reliable, author does not guarantee its accuracy or completeness, nor does author assume any liability for any direct, indirect or consequential loss that may result from the reliance by any person upon any such information or opinions.
Futures, Options on Futures, Foreign Exchange and other leveraged products involves significant risk of loss and is not suitable for all investors. Losses can exceed your deposits. Increasing leverage increases risk. Spot Gold and Silver contracts are not subject to regulation under the U.S. Commodity Exchange Act. Contracts for Difference (CFDs) are not available for US residents. Before deciding to trade forex, commodity futures, or digital assets, you should carefully consider your financial objectives, level of experience and risk appetite. Any opinions, news, research, analyses, prices or other information contained herein is intended as general information about the subject matter covered and is provided with the understanding that we do not provide any investment, legal, or tax advice. You should consult with appropriate counsel or other advisors on all investment, legal, or tax matters. References to FOREX.com or GAIN Capital refer to StoneX Group Inc. and its subsidiaries. Please read Characteristics and Risks of Standardized Options.