

Event Risk Like NFPs and the FOMC Rate Decision Lost Serious Traction in 2025
There were plenty of surprises through 2025 – like the introduction of US ‘reciprocal tariffs’, a record-breaking shutdown from the US government and military strikes on Iran without a catastrophic oil reaction. Yet, the most remarkable development may be the lost traction in traditional data.
Share this:
Talking Points:
- The dramatic announcement of Liberation Day tariffs by the United States in April seemed to shake a lot of the complacent risk built up in the market to that point
- With a market bled of excessive premium in the first half of the year, the draw of complacency accompanied by convenient justifications - like ‘AI revolution’ - kept risk appetite buoyant
- A robust complacency drive helped the markets ride over key event risk and systemic themes like a steady decline in NFPs and a controversial FOMC course
There were plenty of surprises over the past year ranging from the avoidance of official recession despite a trade war, a fast levelling out of a dovish policy regime across the developed world and riding through amplified concerns around the growing fiscal issues in the global system. However, from a trader’s perspective, the bigger surprise was the drop in responsiveness from the markets relative to major event risk such as rate decisions, employment reports and news that tapped into key themes.
The reduced influence of the larger themes in dictating systemic market trends very likely cascades down to the effectiveness of the catalysts that would provoke greed or fear through ‘surprise’ in the event risk. Further, when the focus on major thematic topics rotates regularly, it will further reduce the traction that ‘feeder’ event risk would otherwise earn through its measured adjustment to expectations along those lines. While we expect fundamentals to dictate the tempo and camber of the markets, the reverse may actually be more accurate. A market that is more resilient to provocation and supportive of the complacency speculative bid, can moreso dictate its interests in interpreting the economic calendar or deeper fundamental currents.
Chart of the S&P 500 Index with 100-Day SMA, VIX Volatility Index and 20-Day ATR (Daily)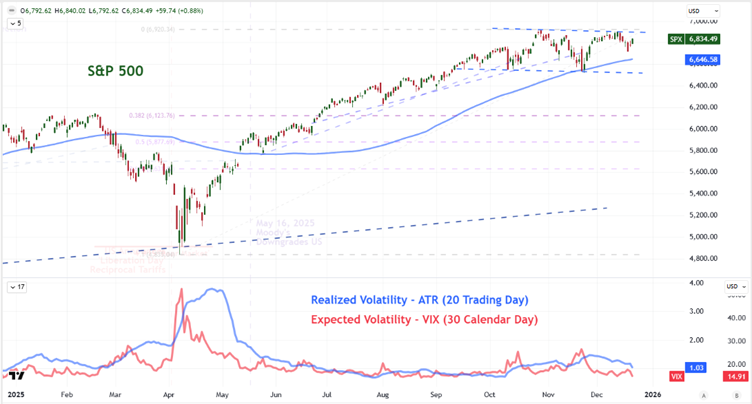
Source: TradingView, John Kicklighter
Looking to a particular venue of fundamentally-driven volatility, the US nonfarm payrolls (NFPs) have long proven among the most capable and reliable scheduled events when it comes to generating heat in the markets. For a backdrop, the heavy speculation around the economic impact of trade relations and fading consumer confidence alongside heavy debate over the Fed’s monetary policy course should have made this data release a strong candidate for volatility from the likes of the Dollar index far in excess of the daily activity norms.
However, meaningful volatility on the release day of the jobs report was the outlier. In 2025, there were a couple of instances where the volatility – measured by the daily range percentage – jumped significantly above the average with an NFPs release. That said, the April charge was in the context of Liberation Day volatility and therefore only the August release therefore stands out. This may be due to large revisions of the past payroll figures, questions over the data’s accuracy by the likes of the White House and disruptions when the theme mattered most (like with the government shutdown); but it is still very much out of the norm relative to history.
Chart of the DXY Dollar Index with Days of NFP Releases and 1-Day Range (Daily)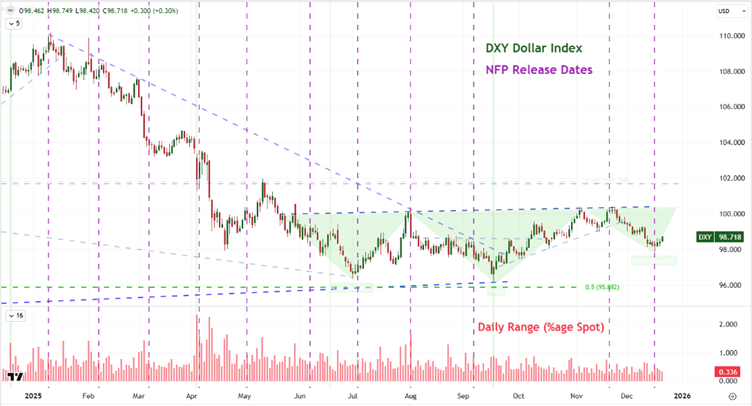
Source: TradingView, John Kicklighter
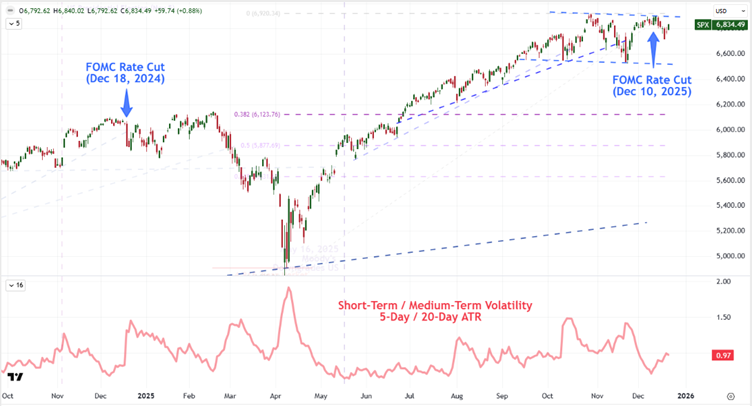
Perhaps an even more remarkable example of event risk losing its impact comes through the FOMC rate decision. Monetary policy is a deeper fundamental theme itself which makes the Fed updates as close a vehicle capable of striking a major nerve as there is through scheduled event risk. Now, the Fed - and other major central banks - endeavors to offer a reasonable outlook to the market, without guaranteeing an outcome, in order to reduce the volatility of surprises. However, the fine speculative setting and forecasting nature of the markets often overrides these efforts.
In 2025, the Fed delayed its return to a dovish policy regime despite aggressive calls from the markets, economists and the government to do so; but that didn’t curb the market’s climb with throttled implied volatility. Far more remarkable though was the lack of impact from the final FOMC rate decision of the year on December 10th. Amid heavy public debate over what course the central bank should be on and discussion around leadership change next year, the group delivered a conflicting update. They would cut rates by -25bps as expected but would also signal that it was only expecting one additional cut in 2026 (hawkish) while also announcing a restart of a smaller QE (dovish). That could have provided surprise for all in this event, yet the S&P 500 wouldn’t break its smallest running range in years.
Chart of the S&P 500 with 5-Day / 20-Day Relative ATR Volatility (Daily)
Source: TradingView, John Kicklighter
While we often focus our attention on technical patterns or the directional course of major fundamental themes or the limited impact potential of individual updates from the calendar; I believe it is far more important to look to the background of the markets themselves. If conditions are – as they have been in 2025 – such that event risk struggles to feed existing trends, forge breakouts or stand as catalyst for reversals; that can help us shape our trading approach and strategy. Given the December FOMC was a strong test of this market distortion through year’s end, it seems that we should retain a degree of skepticism over the impact potential of scheduled event risk into the start of 2026. However, this state is not the norm over a longer time frame; so it is important to keep tabs on the ‘event risk / impact’ scale to be ready to adjust when conditions swing back to normal.
-- Written by John Kicklighter, Global Head of Content
Related tags:
Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
GBP/USD approaches breaking point as US yields surge
A historic repricing of US interest rate expectations has propelled the dollar higher, leaving GBP/USD testing a crucial support level ahead of UK GDP.

EUR/USD, DXY, Silver Price Outlook: Bullish Rebounds on Hold?
EUR/USD, DXY, Silver Price Outlook: Bullish rebounds across currency markets, precious metals, and risk assets are facing renewed pressure as U.S. CPI comes in above expectations and oil-tanker attacks persist in the Strait of Hormuz.

Nasdaq 100 Outlook: Slingshot rally or false dawn?
Nasdaq 100 futures are threatening to reclaim the 200-day moving average following their largest initial breakdown in more than 26 years. History suggests getting back above it is one thing, staying there another.
The information on this web site is not targeted at the general public of any particular country. It is not intended for distribution to residents in any country where such distribution or use would contravene any local law or regulatory requirement. The information and opinions in this report are for general information use only and are not intended as an offer or solicitation with respect to the purchase or sale of any currency or CFD contract. All opinions and information contained in this report are subject to change without notice. This report has been prepared without regard to the specific investment objectives, financial situation and needs of any particular recipient. Any references to historical price movements or levels is informational based on our analysis and we do not represent or warranty that any such movements or levels are likely to reoccur in the future. While the information contained herein was obtained from sources believed to be reliable, author does not guarantee its accuracy or completeness, nor does author assume any liability for any direct, indirect or consequential loss that may result from the reliance by any person upon any such information or opinions.
Futures, Options on Futures, Foreign Exchange and other leveraged products involves significant risk of loss and is not suitable for all investors. Losses can exceed your deposits. Increasing leverage increases risk. Spot Gold and Silver contracts are not subject to regulation under the U.S. Commodity Exchange Act. Contracts for Difference (CFDs) are not available for US residents. Before deciding to trade forex, commodity futures, or digital assets, you should carefully consider your financial objectives, level of experience and risk appetite. Any opinions, news, research, analyses, prices or other information contained herein is intended as general information about the subject matter covered and is provided with the understanding that we do not provide any investment, legal, or tax advice. You should consult with appropriate counsel or other advisors on all investment, legal, or tax matters. References to FOREX.com or GAIN Capital refer to StoneX Group Inc. and its subsidiaries. Please read Characteristics and Risks of Standardized Options.