


FTSE 100 forecast: Technical Tuesday August 12, 2025
n this version of Technical Tuesday, we’re looking at the key drivers shaping global markets, UK economic data, and what technical signals are telling us about the near-term FTSE 100 forecast. Markets were quite quiet in the early parts of Tuesday’s trade, awaiting the release of key US CPI report, which later came in slightly lower than expected and that was enough to send US futures sharply higher....
Share this:
Markets were quite quiet in the early parts of Tuesday’s trade, awaiting the release of key US CPI report, which later came in slightly lower than expected and that was enough to send US futures sharply higher. Despite a weaker start to the day, sentiment was overall positive, as Trump extended the pause on China’s tariffs for another 90. In the UK, we had some mixed data earlier, which kept the FTSE and pound supported, while the weakness in German ZEW data hurt both the DAX and the euro. In this version of Technical Tuesday, we’re looking at the key drivers shaping global markets, UK economic data, and what technical signals are telling us about the near-term FTSE 100 forecast.
Chinese tariffs pause extended
The big news overnight was that Donald Trump has indeed extended the pause on higher tariffs on Chinese goods for another 90 days, until November 10. This was hardly surprising truth be told. The extension gives both sides more time to negotiate and aims to stabilise trade relations between the world’s two largest economies. Had this truce not been extended, the consequences for China and the markets would have been dire. US tariffs on Chinese goods would have jumped to at least 54% today. So, this is clearly a relief for markets. Yet, the lack of a more meaningful rally in global markets overnight suggests the move was priced in. But is the extension really good news? On the one hand, the extension does provide relief that another trade war is averted. But on the other, some would argue it prolongs uncertainty. So, markets didn’t know how to react to the news, although the lack of volatility suggests calm remains the order of the day.
What about inflation concerns?
Since April, markets worldwide, including the FTSE 100, have rallied strongly. This is partly due to easing fears around the trade war and central banks gradually cutting interest rates, which has further fuelled the rally. Inflation concerns, however, have not gone away. Many economists believe Trump’s tariffs will eventually be passed on to consumers. But this wasn’t clearly evidenced in yet another inflation report from the US, released moments ago.
US CPI came in unchanged at 2.7% on a year-over-year basis compared to 2.8% expected, while the month-over-month rate was in line at 0.2% in July. Core measure of CPI was little bit higher than expected, with a print of 0.3% m/m, which helped to push up the y/y rate to 3.1% from 3.0%.
If US and global inflation starts to accelerate again in the coming months, consumers’ purchasing power will be squeezed even more. Meanwhile, central banks might have to keep interest rates higher than they’d like to, which means borrowing costs remain high.
This combination could hit consumer spending hard, ultimately hurting company profits and their share prices.
UK wages fall more than expected
Earlier today, we had some mixed data from the UK following last week’s Bank of England rate cut, which was a very close call when policymakers were sharply divided but ultimately agreed to cut rates.
Today’s data showed average earnings increased by 4.6% in the three months to June compared to a year ago — weaker than the 5.0% rise we saw the previous month. On the jobs front, employment has now fallen eight times in the past nine months. However, the latest drop of 8,000 jobs is the smallest decline so far, suggesting the labour market may be stabilising.
A weakening jobs market could ease wage inflation pressures and open the door to further rate cuts, but whether this happens at November’s meeting remains uncertain following that hawkish cut last week, meaning the chance of another cut in November is now lower.
Meanwhile, a UK data dump is scheduled for Thursday when we will have Q2 GDP as well as monthly data on construction output, manufacturing production and a few other indicators to look forward to. The odds of a further BoE rate cut this year will continue to tumble in the event we see stronger data from the UK this week. Whether this will weigh on the FTSE 100 forecast is difficult to say, given that the index’s components are major global corporations that rely more on sales out of the UK.
FTSE 100 forecast: Key levels to watch
From a technical point of view, the FTSE 100 forecast remains positive for now. The FTSE is holding steady inside a short-term consolidation pattern near its recent record high of 9,191.
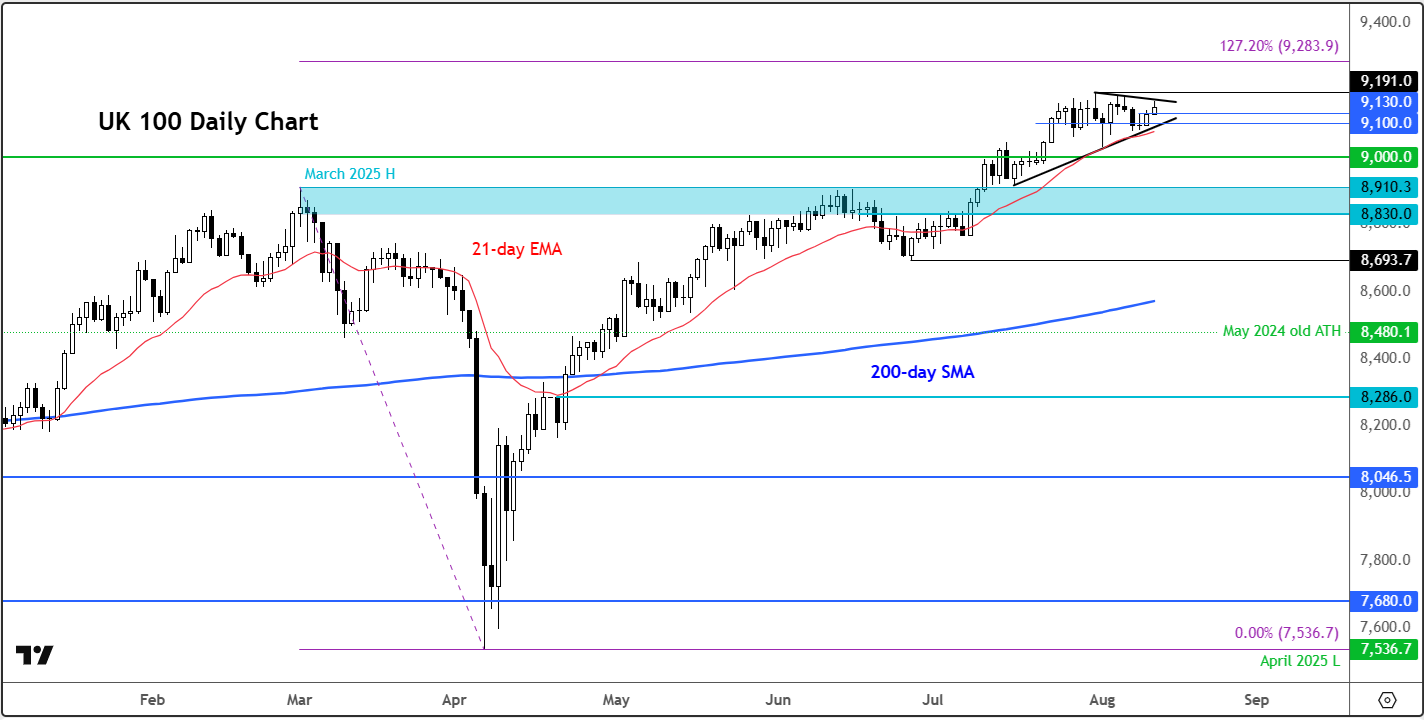
This consolidation is helping to ease overbought conditions on short-term indicators — which is generally a bullish sign.
The FTSE remains above its main moving averages and has broken through several resistance levels.
This means the path of least resistance points clearly upwards.
Until we see clear signs of a market top, the strategy remains to look for dip-buying opportunities and target new highs.
Key short-term support levels to watch are 9,135, 9,100, and 9,050. Longer-term support is seen around 9,000 and the area between 8,830 to 8,910 (shaded in blue on the chart).
On the upside, resistance comes in at 9,165/75, marking the bearish trend line of the consolidation pattern, then the all-time high of 9,191 will be in focus next.
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold coils for potential breakout as US CPI looms
Gold's ascending triangle is putting $4,140 firmly in focus ahead of US CPI. With traditional macro relationships offering few clues, the price action may prove more useful for traders.

USD/CAD Outlook: Loonie left behind as US CPI looms
USD/CAD's sharp rebound has coincided with widening US–Canada interest rate differentials. With US CPI approaching and bullish momentum building, another breakout may be on the cards.
Japanese Yen Outlook: EUR/JPY and GBP/JPY Outbid USD/JPY
The Japanese yen starts the week mixed, with EUR/JPY and GBP/JPY showing bullish potential while USD/JPY remains stuck in a rut.

The information on this web site is not targeted at the general public of any particular country. It is not intended for distribution to residents in any country where such distribution or use would contravene any local law or regulatory requirement. The information and opinions in this report are for general information use only and are not intended as an offer or solicitation with respect to the purchase or sale of any currency or CFD contract. All opinions and information contained in this report are subject to change without notice. This report has been prepared without regard to the specific investment objectives, financial situation and needs of any particular recipient. Any references to historical price movements or levels is informational based on our analysis and we do not represent or warranty that any such movements or levels are likely to reoccur in the future. While the information contained herein was obtained from sources believed to be reliable, author does not guarantee its accuracy or completeness, nor does author assume any liability for any direct, indirect or consequential loss that may result from the reliance by any person upon any such information or opinions.
Futures, Options on Futures, Foreign Exchange and other leveraged products involves significant risk of loss and is not suitable for all investors. Losses can exceed your deposits. Increasing leverage increases risk. Spot Gold and Silver contracts are not subject to regulation under the U.S. Commodity Exchange Act. Contracts for Difference (CFDs) are not available for US residents. Before deciding to trade forex, commodity futures, or digital assets, you should carefully consider your financial objectives, level of experience and risk appetite. Any opinions, news, research, analyses, prices or other information contained herein is intended as general information about the subject matter covered and is provided with the understanding that we do not provide any investment, legal, or tax advice. You should consult with appropriate counsel or other advisors on all investment, legal, or tax matters. References to FOREX.com or GAIN Capital refer to StoneX Group Inc. and its subsidiaries. Please read Characteristics and Risks of Standardized Options.