


Japanese Yen Outlook: Firmer CPI Fails to Lift JPY
Japan CPI strengthened the case for a September BOJ hike, yet the yen remains weak as traders weigh intervention, yields and higher oil prices.
Share this:
Japan’s latest CPI report strengthened the case for another BOJ rate hike in September, yet the yen weakened across the FX majors following the release. With a hike already largely priced in, traders appear more focused on whether the BOJ accelerates tightening, while intervention risk, US yields and higher oil prices add to an increasingly complicated backdrop for JPY.
View related analysis:
View related analysis:
Japanese Yen Weakens Despite Firmer CPI and BOJ Hike Bets
Japan Inflation Keeps BOJ September Hike in Play
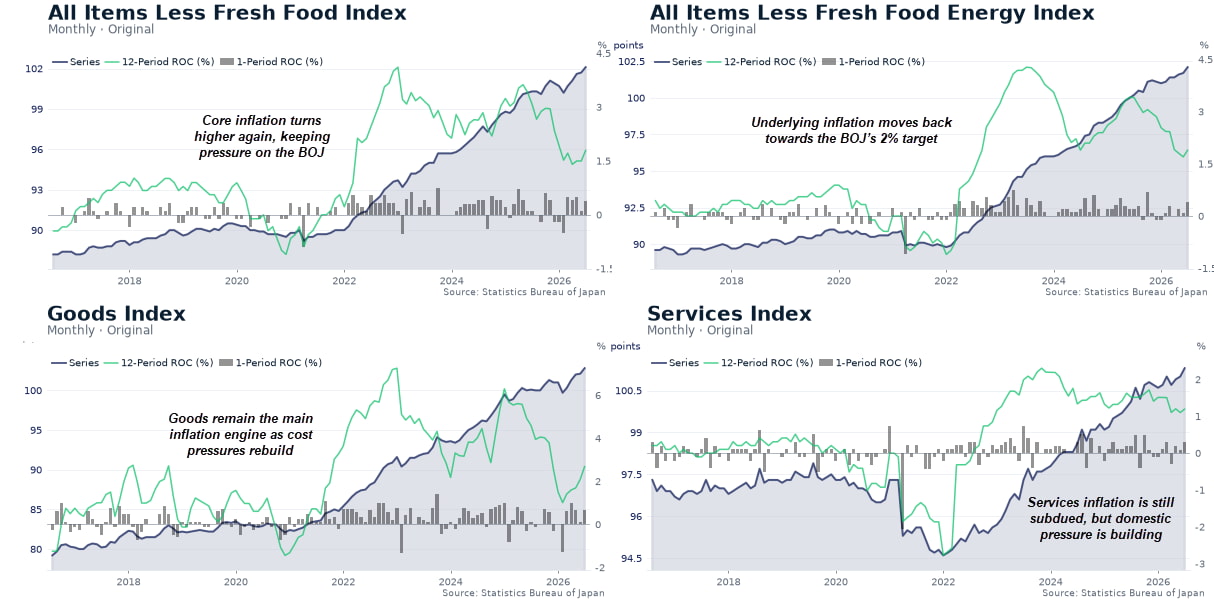
Japan’s latest inflation data strengthened the case for another Bank of Japan rate hike in September, with core CPI excluding fresh food rising 1.8% year on year in July from 1.6%, while the measure excluding both fresh food and energy accelerated to 1.9%.
The breakdown shows goods prices are still doing much of the heavy lifting, rising 2.7% as the weak yen, higher commodity prices and imported costs feed through to consumers. Services inflation also edged higher to 1.2%, which is more important for the BOJ as it points to firms gradually passing higher labour costs on to consumers.
Source: Statistics Bureau of Japan, Reuters
- Core CPI rose 1.8% YoY in July, up from 1.6% in June and in line with expectations.
- Underlying CPI excluding fresh food and energy accelerated to 1.9%, moving closer to the BOJ’s 2% target.
- Goods inflation led at 2.7%, showing imported costs, the weak yen and higher commodity prices are still doing much of the work.
- Services inflation edged up to 1.2%, a modest but important sign that domestic wage pressures are gradually feeding into prices.
BOJ September Hike Becomes the Base Case
A September hike to 1.25% is increasingly becoming the base case, while the bigger question for yen traders is whether persistent inflation and yen weakness force the BOJ to accelerate its tightening cycle beyond September.
While a September hike may seem like a bullish cue for the yen, the BOJ’s gradual tightening alone may not be enough to back a stronger currency. Besides, the bigger shift has already come from joint US-Japan intervention, which has made it considerably more dangerous for traders to aggressively rebuild yen shorts. With Washington signalling it could support Japan again, further BOJ tightening would add another layer of support rather than carry the burden alone.
Yen Shrugs Off Firmer CPI as BOJ Hike Bets Build
The Japanese yen was a touch lower across the board after the latest CPI figures were released, suggesting the data did little to materially change a policy outlook where a September hike is already largely priced in.
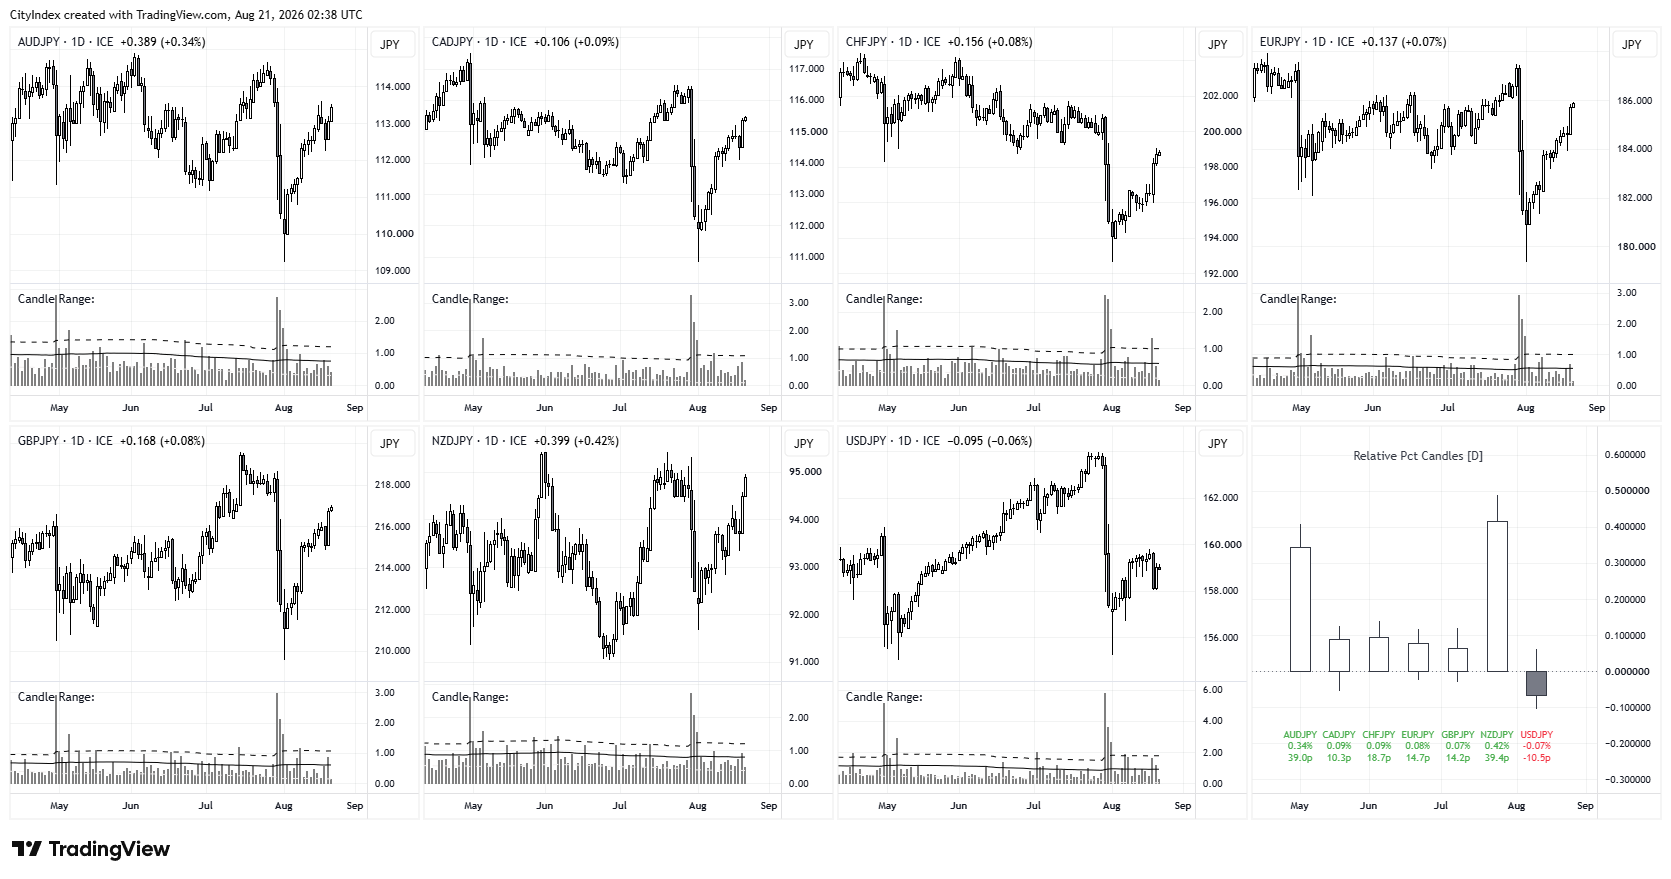
But the fact that the yen continues to weaken despite the US and Japan joining forces on intervention suggests yen bears may be rolling the dice — or goading the powers that be back into action. GBP/JPY, EUR/JPY, CHF/JPY, CAD/JPY and NZD/JPY sit at three-week highs, while AUD/JPY remains beneath Monday’s shooting star high.
USD/JPY fell sharply on Wednesday after the US Treasury stepped in to support the bond market as the 30-year yield broke above 5.3%. Yet bond traders are putting up a bit of a fight, with renewed selling sending the 30-year yield back above 5.2% on Thursday and helping USD/JPY recoup around two-thirds of Wednesday’s losses.
Source: ICE, TradingView
Higher Oil and JGB Yields Complicate the Yen Outlook
Higher oil prices are adding another complication for yen traders. Crude jumped around $2 overnight as Middle East tensions intensified, helping push Japanese bond yields higher as inflation concerns resurfaced. The 10-year JGB yield rose 3bp to 2.875%, while the 30-year climbed 5.5bp to 4.06%. Higher Japanese yields should theoretically lend the yen some support, but rising energy costs are also a headwind for an economy heavily reliant on imported fuel, leaving the currency caught between tighter BOJ expectations and a deteriorating terms-of-trade backdrop.
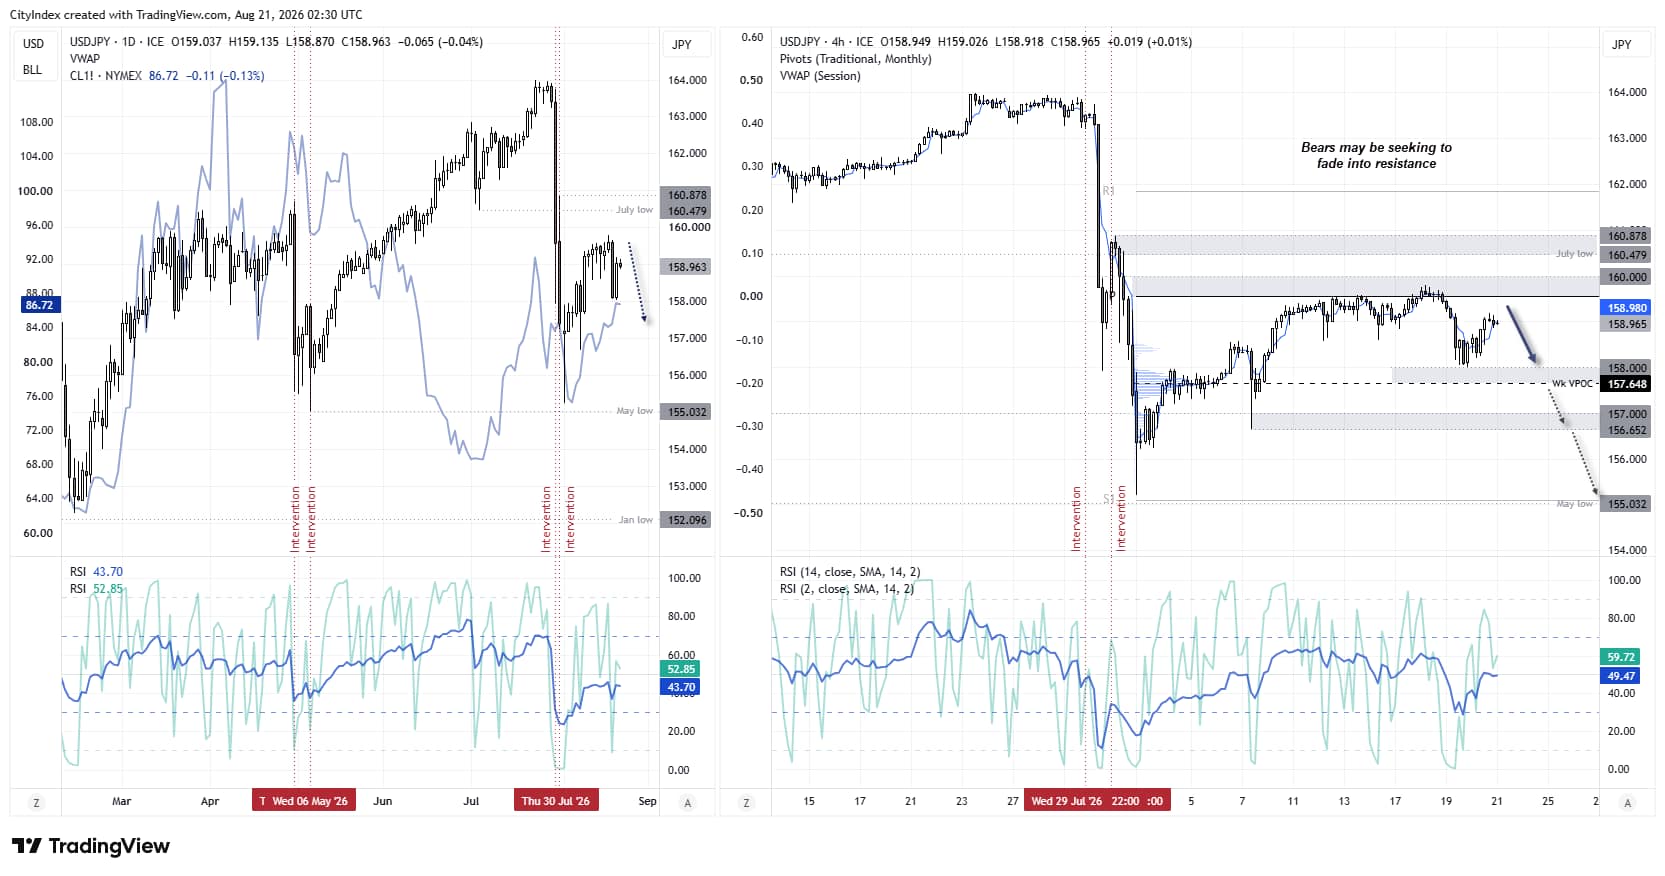
Source: ICE, TradingView
USD/JPY Outlook: Summary
- Japan CPI strengthened the case for a September BOJ hike, but much of that move is already priced in.
- The yen remains weak despite firmer inflation and joint US-Japan intervention, suggesting traders are still willing to test policymakers.
- Higher US yields continue to support USD/JPY, while rising JGB yields provide only limited offset.
- Higher oil prices complicate the picture by lifting Japanese inflation expectations while worsening the terms-of-trade backdrop for the yen.
View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold outlook: haven demand fades as hot US CPI adds to the pressure
A day after falling more than 2.5%, gold edged higher in early trade on Wednesday, along with global indices and US index futures. The US dollar remained supported, however, although gold or silver showed little concern.
USD/JPY, DAX Forecast: Two trades to watch
Will USD/JPY break out of its 2-month range? DAX nears record highs as oil prices fall to 2-month lows.

Nasdaq 100 Outlook: Slingshot rally or false dawn?
Nasdaq 100 futures are threatening to reclaim the 200-day moving average following their largest initial breakdown in more than 26 years. History suggests getting back above it is one thing, staying there another.

The information on this web site is not targeted at the general public of any particular country. It is not intended for distribution to residents in any country where such distribution or use would contravene any local law or regulatory requirement. The information and opinions in this report are for general information use only and are not intended as an offer or solicitation with respect to the purchase or sale of any currency or CFD contract. All opinions and information contained in this report are subject to change without notice. This report has been prepared without regard to the specific investment objectives, financial situation and needs of any particular recipient. Any references to historical price movements or levels is informational based on our analysis and we do not represent or warranty that any such movements or levels are likely to reoccur in the future. While the information contained herein was obtained from sources believed to be reliable, author does not guarantee its accuracy or completeness, nor does author assume any liability for any direct, indirect or consequential loss that may result from the reliance by any person upon any such information or opinions.
Futures, Options on Futures, Foreign Exchange and other leveraged products involves significant risk of loss and is not suitable for all investors. Losses can exceed your deposits. Increasing leverage increases risk. Spot Gold and Silver contracts are not subject to regulation under the U.S. Commodity Exchange Act. Contracts for Difference (CFDs) are not available for US residents. Before deciding to trade forex, commodity futures, or digital assets, you should carefully consider your financial objectives, level of experience and risk appetite. Any opinions, news, research, analyses, prices or other information contained herein is intended as general information about the subject matter covered and is provided with the understanding that we do not provide any investment, legal, or tax advice. You should consult with appropriate counsel or other advisors on all investment, legal, or tax matters. References to FOREX.com or GAIN Capital refer to StoneX Group Inc. and its subsidiaries. Please read Characteristics and Risks of Standardized Options.