



Nasdaq 100 Forecast: “Magnificent Seven” Q2 2025 Earnings Preview
The Nasdaq 100 remains in a bullish channel and could target 24,000 or 25,000 if Big Tech stocks can deliver on earnings expectations.
Share this:
Nasdaq 100 Key Points
- With over $400B in AI and datacenter investments projected this year, the Magnificent Seven continue to drive the digital infrastructure boom…though any cap-ex slowdown could spark a sharp rerating.
- Despite pockets of consumer weakness, especially for Apple and Tesla, enterprise tech spending and digital advertising remain robust, setting the stage for another bifurcated earnings season.
- The Nasdaq 100 remains in a bullish channel and could target 24,000 or 25,000 if Big Tech stocks can deliver on earnings expectations.
Magnificent Seven Earnings Preview – MSFT, AAPL, GOOG, AMZN, NVDA, META, TSLA
Throughout most of the last few years, the “Magnificent Seven” big technology stocks (Microsoft, Apple, Nvidia, Alphabet/Google, Meta/Facebook, and Tesla) broadly moved as a monolithic unit, rising and falling in unison with the (mostly) ups and (fewer) downs of the broader market, albeit to differing extents
Since flipping the calendar to 2025, the individual differences between these massive entities have become more stark, with growth laggards like Apple and Tesla falling despite generally bullish conditions and standouts like Nvidia and Microsoft gaining more than 20% year-to-date:
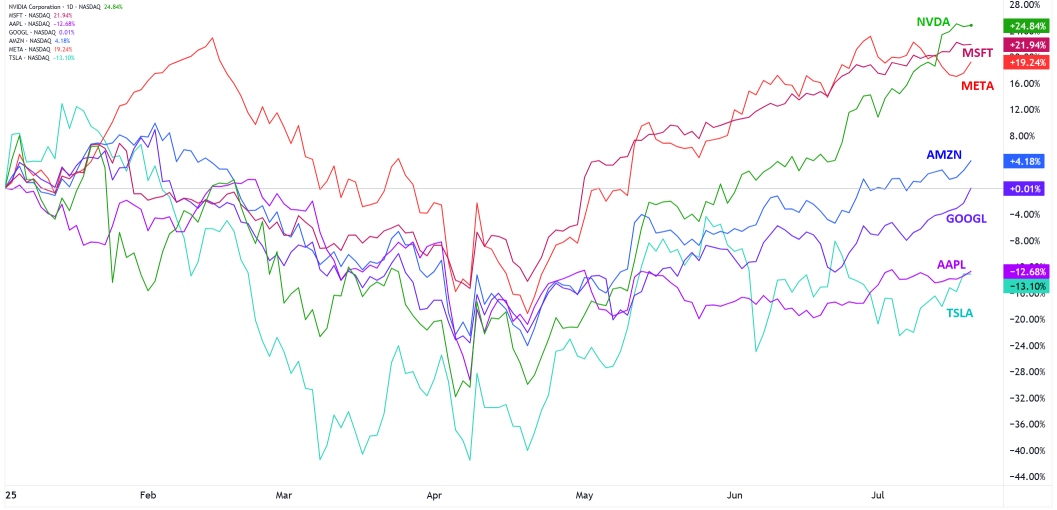 Source: StoneX, TradingView
Each of the Magnificent Seven stocks faces its own set of opportunities and challenges, but some common themes to monitor are the health of the consumer and timing of any interest rate cuts from the Federal Reserve, as well as the impact of AI and growth of augmented/virtual reality devices.
Magnificent 7 Earnings “Cheat Sheet”
|
COMPANY |
Report date / time |
CONSENSUS EPS ESTIMATE* |
Y/Y REVENUE DRIVERS |
TOP ISSUES |
|
Tesla (TSLA) |
Wed 23 Jul after - close |
$0.44 |
-13% unit vols, weaker price/mix |
Auto-gross-margin trough? ˑ Robo-taxi roadmap ˑ China demand & tariffs |
|
Alphabet (GOOGL) |
Wed 23 Jul after - close |
$2.17 |
Search & YouTube ads + low-teens Cloud |
Gen-AI search monetisation ˑ TAC inflation ˑ EU DMA impact |
|
Microsoft (MSFT) |
Wed 30 Jul after - close |
$3.38 |
Azure +13% cc, O365 +11% |
AI-attached Azure growth, Copilot seat uptake, Activision synergies |
|
Meta (META) |
Wed 30 Jul after - close |
$5.84 |
Re-accelerating ad spend (retail & gaming) |
AI-inference cap-ex ($35-40 bn run-rate) ˑ Reels monetisation |
|
Amazon (AMZN) |
Thu 31 Jul after - close |
$1.31 |
AWS +23%, Retail +8% |
Gen-AI services attach, ad-net high-teens growth, fulfilment cost leverage |
|
Apple (AAPL) |
Thu 31 Jul after - close |
$1.42 |
iPhone rebound in China, Services +12% |
Gross-margin slip from discounting, visionOS / “Apple Intelligence” clues |
|
NVIDIA (NVDA) |
Wed 27 Aug after - close |
$1.00 (post-split†) |
Data-centre +80%, gaming normalises |
Supply vs. Blackwell demand; China export licences; buy-back cadence |
*EPS consensus = current Zacks/FactSet or equivalent public-source average unless otherwise noted.
†10-for-1 split effective 9 Jun 2025.
Key Magnificent Seven Themes to Watch This Earnings Season
- AI Infrastructure Tidal Wave
Wall Street’s biggest storyline remains the sheer scale-up in datacenter spending. Bank of America now projects the four “hyperscalers” (Amazon Web Services (AWS), Microsoft Azure, Google Cloud Platform (under Alphabet/Google) and Meta Platforms) will plough about $414 billion into AI and general datacenter cap-ex in 2025, rising to roughly $432 billion in 2026—double the 2023 run-rate. Gartner’s fresh IT-budget survey corroborates the trend, flagging a 42% jump in datacenter outlays next year, far outpacing every other line-item in corporate tech budgets.
With Nvidia still effectively sold-out through its Blackwell cycle and AMD, Broadcom and TSMC signalling back-end bottlenecks well into 2026, any management hints of a “pause” in rack installs could ricochet across the entire Mag-7 narrative.
- Ad Market Resilience Amidst Macroeconomic Wobbles
Advertising demand continues to shrug off the stop-start economy. GroupM estimates that global ad revenue will surpass the $1 trillion mark this year and grow another 7.7% in 2025, with digital formats capturing nearly three-quarters of the total.
The combination of AI-driven targeting tools, retail-media momentum and Shorts/Reels video inventory is letting the platforms raise impressions even as some brands edge budgets lower. Investors will therefore focus less on Q2 prints and more on color around Q4 holiday bookings, where any abrupt pull-back could force the first material guidance resets in six quarters.
- Consumer Wallets vs. Enterprise War Chests
The gap between household and corporate spending power is becoming glaring. In China, a bellwether for discretionary tech demand, iPhone shipments fell 9% year-on-year in Q1 2025, making Apple the only top five vendor to shrink in the world’s second-largest smartphone market.
On the auto side, Tesla’s automotive gross margin has already slid from 16% in early 2024 to about 13.6% in Q4, with UBS warning it could sink near 10% in Q1 2025 as price cuts persist. By contrast, CIOs keep the checkbook open: Gartner forecasts overall IT spending to climb by 7.9% in 2025, propelled largely by AI-optimized infrastructure budgets.
Expect earnings calls to paint a bifurcated picture—consumer-facing names defending volumes and discounting, while enterprise-exposed cloud providers boast healthy double-digit growth.
- Policy & Regulation Watch
The legal and political backdrop is as busy as the P&L sheets. The Department of Justice has moved into the remedies phase of its search-antitrust win against Google, signaling possible structural changes to how the company bundles advertising and search services. In Europe, Apple is appealing a €500 million fine under the Digital Markets Act even as it tweaks App-Store commission rules—investors will parse any further concession language.
Across the Atlantic, a federal judge last week postponed Texas’s $100 billion ad-tech case against Google until a related Virginia verdict is final, potentially pushing headline risk into 2026.
On the trade front, Nvidia is rolling out export-compliant H20 and RTX 6000D GPUs to keep Chinese revenues flowing amid shifting US licensing rules, underscoring how supply-chain workarounds are now part of the earnings script.
Finally, Washington’s 100% tariff on Chinese EV imports remains a wildcard for Tesla and, indirectly, Apple’s China-centric supply chain if retaliatory measures materialize later this year.
Nasdaq 100 Technical Analysis – NDX Daily Chart
Source: TradingView, StoneX
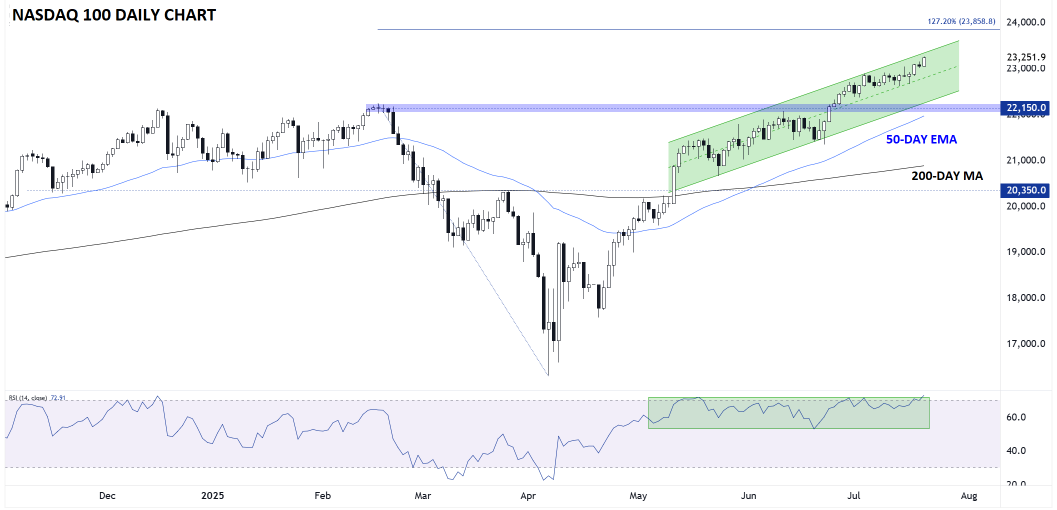
As the chart above shows, the Nasdaq 100 has more than recovered from its Q1 swoon to trade at fresh record highs, despite the mixed performance of the technology behemoths so far this year.
More immediately, the index is trending consistently higher within a bullish channel, keeping the technical bias tilted toward the topside as long as this season’s earnings results at least meet analyst expectations. To the topside, the next level of resistance to watch is the 127% Fibonacci extension of the Q1 drop near 24,000, followed by the round 25,000 handle after that.
However, if weak earnings reports start to accumulate and the index breaks down from its channel to fall below the 50-day EMA, a deeper retracement toward the 200-day MA near 21,000 could be in the cards.
-- Written by Matt Weller, Global Head of Research
Follow Matt on Twitter: @MWellerFX


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Australian Dollar Forecast: AUD/USD Breaks Multi-Month Range, Hits 10-Month Low 11 14 2026
Aussie bears are closing in on major technical support, with next week's Australian employment data raising the stakes for a pivotal reaction.

USD/JPY Weekly Outlook: Bulls Eye Higher Range After Historic Rate Shock
A historic US rate shock has sent USD/JPY above 160, but with intervention risks rising and few major economic catalysts ahead, AI sentiment could hold the key to the next move.


Nvidia Earnings Preview: NVDA’s First Test of the Post Jenson Huang Era
Nvidia is expected to report $2.47 in EPS on $108.8B in revenue this quarter, but investors will be more interested in the company's guidance after the unexpected departure of founder and CEO Jenson Huang.
The information on this web site is not targeted at the general public of any particular country. It is not intended for distribution to residents in any country where such distribution or use would contravene any local law or regulatory requirement. The information and opinions in this report are for general information use only and are not intended as an offer or solicitation with respect to the purchase or sale of any currency or CFD contract. All opinions and information contained in this report are subject to change without notice. This report has been prepared without regard to the specific investment objectives, financial situation and needs of any particular recipient. Any references to historical price movements or levels is informational based on our analysis and we do not represent or warranty that any such movements or levels are likely to reoccur in the future. While the information contained herein was obtained from sources believed to be reliable, author does not guarantee its accuracy or completeness, nor does author assume any liability for any direct, indirect or consequential loss that may result from the reliance by any person upon any such information or opinions.
Futures, Options on Futures, Foreign Exchange and other leveraged products involves significant risk of loss and is not suitable for all investors. Losses can exceed your deposits. Increasing leverage increases risk. Spot Gold and Silver contracts are not subject to regulation under the U.S. Commodity Exchange Act. Contracts for Difference (CFDs) are not available for US residents. Before deciding to trade forex, commodity futures, or digital assets, you should carefully consider your financial objectives, level of experience and risk appetite. Any opinions, news, research, analyses, prices or other information contained herein is intended as general information about the subject matter covered and is provided with the understanding that we do not provide any investment, legal, or tax advice. You should consult with appropriate counsel or other advisors on all investment, legal, or tax matters. References to FOREX.com or GAIN Capital refer to StoneX Group Inc. and its subsidiaries. Please read Characteristics and Risks of Standardized Options.