

US futures
Dow futures -0.51%, S&P futures -0.29% & Nasdaq futures -0.23%
In Europe
FTSE 0.25% & DAX 0.48%
- U.S stocks pause around record highs
- US-Iran continue to negotiate, treasury yields fall
- AI optimism continues as Anthropic files for IPO
- Oil eases back after yesterday’s spike
Middle East concerns ease as AI enthusiasm continues
U.S. stocks are set to open modestly lower around record highs as oil prices and bond yields fall on renewed hopes for a U.S.-Iran deal. AI optimism also remains supportive following Anthropic's move towards a U.S. IPO.
Oil prices have eased, bringing Treasury yields lower, after President Trump said talks with Iran are continuing. His comments come despite Tehran yesterday indicating it had suspended direct negotiations. These mixed messages highlight just how fragile the peace process remains. However, there is a growing sense that time may be running out. Moody's chief economist warned that the White House has roughly a week to secure a peace deal before the economic fallout from the conflict materially increases the risk of a U.S. recession.
Meanwhile, enthusiasm surrounding AI continues to support equities. The rally across AI-related stocks, particularly chipmakers, has helped drive extraordinary gains in U.S. markets despite lingering geopolitical uncertainty.
Underlining this trend was news that Anthropic had confidentially filed for a U.S. IPO, edging ahead of rival OpenAI. The company could be valued at close to $1 trillion and may debut as soon as the autumn.
The filing is significant not just because of Anthropic's valuation, but because it signals that some of the largest private AI companies are preparing to test public-market demand. With Anthropic, OpenAI and SpaceX all potentially heading to market within a relatively short period, investors may soon be asked to absorb some of the largest IPOs in history.
With stock valuations already looking stretched, comparisons with the dot-com era are becoming increasingly common. A growing share of market gains is being driven by a relatively small number of AI-linked companies, making the broader market increasingly dependent on the sector's continued success.
On the economic front, attention is turning to Friday's non-farm payroll report, which could provide further clues over the health of the U.S. labour market and the outlook for Federal Reserve policy. Strong job creation alongside persistent inflation could strengthen the case for rates remaining higher for longer.
Before then, JOLTS job openings data are due shortly and are expected to show vacancies remained broadly unchanged at 6.8 million.
Data released yesterday showed that the ISM Services PMI rose to 54 in May from 52.7 previously, marking the strongest reading in four years as firms front-loaded orders amid rising prices and supply concerns linked to the Iran conflict. The resilience in the services sector suggests the U.S. economy continues to hold up despite elevated borrowing costs, which could make it harder for the Fed to justify rate cuts in the near term.
Corporate movers
Alphabet is falling 2.8% after the Google parent announced plans to raise $80 billion through a stock sale to fund its AI infrastructure build-out. It is unusual for a company of Alphabet's size to raise this much equity capital, highlighting the enormous investment requirements associated with the AI race.
Capital expenditure in 2027 is expected to be significantly higher than the $190 billion budgeted for 2026, a level that was already more than double last year's spending. The move could also intensify competition for investor capital ahead of several high-profile AI-related IPOs, including Anthropic, OpenAI and SpaceX. With many investors already heavily exposed to AI, the market's ability to absorb both fresh equity issuance and major IPOs will be closely watched.
The timing is also favourable for Alphabet, which is taking advantage of a strong share price and is now the world's second-most valuable listed company.
Marvell has jumped 22% after Nvidia CEO Jensen Huang said the company could become the next trillion-dollar business.
Hewlett Packard Enterprise has gained 25% after issuing current-quarter earnings and revenue guidance above expectations. The company also raised its full-year outlook, reinforcing the view that AI-related spending remains strong.
NASDAQ – technical analysis
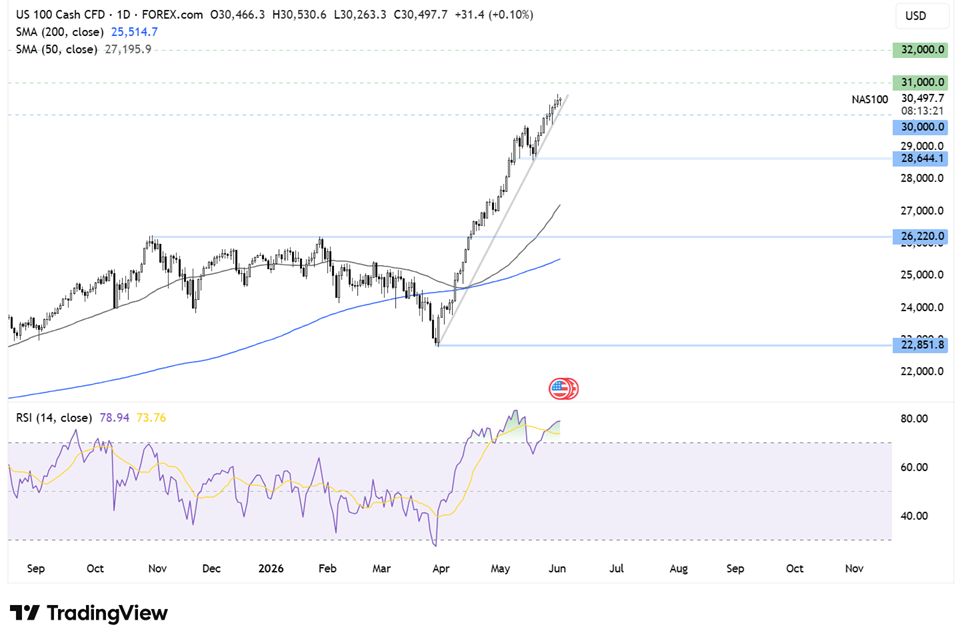
The NASDAQ has extended its rally from the 22,800 low to a fresh record high of 30,630. The price remains above its rising trendline and key moving averages, highlighting the strength of the uptrend.
However, the RSI remains deeply in overbought territory, suggesting some consolidation or a pullback may be needed before the next leg higher. While momentum remains firmly with buyers, stretched positioning leaves the index vulnerable to profit-taking should sentiment deteriorate.
Buyers will look to extend gains towards 31,000 and then 32,000.
Support can be seen at 30,000, the psychological level, ahead of 28,500, the May 19 swing low. Below here, 28,000 comes into focus. It would take a move below 26,250 to negate the longer-term uptrend.
FX markets – USD eases, EUR/USD rises
The U.S. dollar is easing back and remains within a narrow trading range as improving sentiment surrounding Middle East diplomacy offsets demand for safe-haven assets.Markets continue to price around a 70% probability of a 25-basis-point Fed rate hike this year, helping to limit downside pressure on the dollar.
EUR/USD is rising after stronger-than-expected Eurozone inflation data. CPI rose to 3.2% annually in May from 3.0% in April, driven by a 10% rise in energy costs and an unexpected acceleration in services inflation to 3.5%. The data reinforce expectations that the ECB will raise rates by 25 basis points next week.
GBP/USD is rising for a fourth straight day, moving towards 1.35. Improving risk sentiment is supporting the pound, even after Bank of England Governor Andrew Bailey signalled there was no rush to raise rates given weak domestic growth.
Oil eases after yesterday's spike
Oil prices are falling after sharp gains in the previous session as traders weigh mixed signals from U.S.-Iran negotiations aimed at ending the Middle East conflict.
WTI and Brent are both trading around 1% lower, with Brent slipping back towards $91 a barrel after surging more than 4% on Monday.
Oil continues to trade almost entirely on geopolitical headlines, suggesting traders remain far more focused on supply risks than demand fundamentals.
Comments from President Trump that talks with Iran are continuing helped ease concerns after reports that Tehran had suspended negotiations triggered a sharp rally in crude prices yesterday. The reaction highlights how sensitive oil remains to developments in the Middle East, with traders quick to reprice supply risks whenever tensions escalate.




