





Crude Oil Week Ahead: Oversupply vs. Supply Disruption Risks
Crude Oil Week Ahead: Oil prices remain range-bound, caught between rising Middle East tensions and potential Russia–Ukraine peace deals. While peace deals could amplify oversupply and weak demand concerns, escalating conflict may lift risk premiums and temporarily support prices.
Share this:
Key Events to Watch
- Eurozone & UK Flash Manufacturing PMIs remain mixed amid ongoing trade war volatility; U.S. PMIs due next
- April tariff adjustments underway: reciprocal measures and additional 20% tariffs on China stabilize gold above $3,000 and pressure oil’s rebound below the $70 mark
- Geopolitical flashpoints: Russia, Ukraine, Yemen, Israel, and Palestine
- Weekly Technical Forecast
Renewed Tariffs & Economic Consequences
Trump’s policies are increasingly facing public and market resistance, with many viewing them as detrimental to both the U.S. and global economies. The threat of additional 20% tariffs on Chinese exports adds further strain on China’s economic recovery and weakens global oil demand outlook.
Globally, reciprocal tariffs—such as the 25% duties on steel and aluminum—could drive inflationary pressures while simultaneously dampening growth, leaving markets cautious despite last week’s rebound. Although major currency pairs and equity indices reversed course following the recent Fed meeting, the sustainability of this move remains uncertain amid a turbulent political and geopolitical backdrop.
Flash manufacturing PMIs released today reflect a mixed picture:
- Eurozone: Manufacturing PMI rose slightly from 47.6 to 48.7, while Services PMI dipped from 50.6 to 50.4.
- UK: Manufacturing PMI dropped further into contraction territory from 46.9 to 44.6, whereas Services PMI rose from 51.0 to 53.2, reinforcing an overall mixed economic outlook—and by extension, mixed implications for oil demand.
U.S. PMI data will be released later today and is likely to further shape market sentiment.
Geopolitical Tensions and Sanction Risks
Geopolitical tensions continue to make headlines, with key flashpoints involving the U.S., Iran, Yemen, Russia, Ukraine, Israel, and Palestine—all significantly impacting oil prices.
- U.S.–Yemen: Tensions center around securing the Red Sea and protecting Israel from Iran-backed Houthi forces in Yemen. Given the Red Sea’s strategic role in global oil transportation, any escalation poses serious supply concerns and increases upside hedging risks.
- U.S.–Iran: Strained relations over Iran’s nuclear program have led the U.S. to impose sanctions targeting all Iranian oil exports. Further escalation could drive oil prices higher due to reduced global supply.
- Israel–Gaza Conflict: The recent collapse of a ceasefire deal has reignited fears of broader regional escalation, renewing upward pressure on oil prices through increased geopolitical risk premiums.
- Russia–Ukraine War: While diplomatic efforts continue, the prolonged conflict—especially attacks on critical energy infrastructure—remains a key factor in maintaining upside hedging demand in the oil market.
Although current price pressures are driven by geopolitical risk, the emergence of peace agreements or de-escalation in any of these regions could reverse sentiment and apply bearish pressure by reducing the need for risk hedging in oil.
Technical Analysis: Quantifying Uncertainties
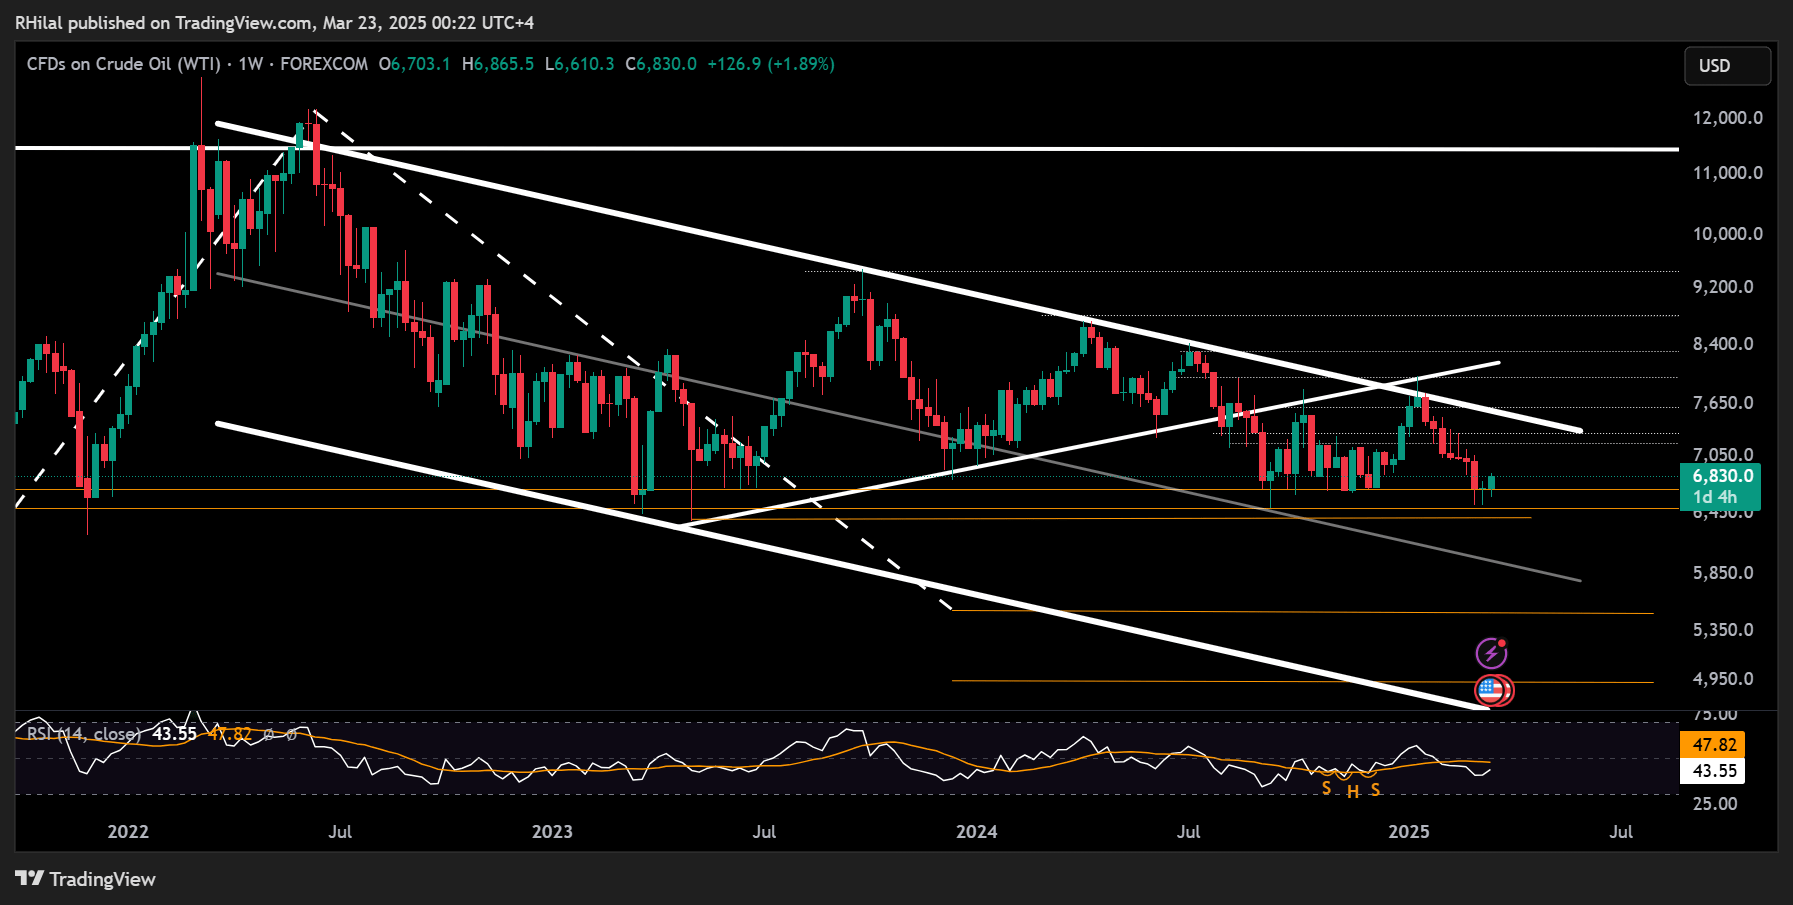
Crude Oil Week Ahead: Weekly Time Frame - Log Scale
Source: Trading view
From a weekly time frame perspective, oil prices have continued to respect the boundaries of a declining channel since the 2022 highs, reaching three-year lows in 2025, in alignment with the long-standing support zone between $64 and $66 that has held since 2021.
After recently rebounding from the $65 level, a decisive close below $63.80 would confirm further downside potential, opening the way toward key support levels at $60, $55, and, in more extreme scenarios, $49.
If the support zone holds, resistance levels within the declining channel may come into play at $72, $73, and $76. A breakout above the channel’s upper boundary and a sustained hold above $78 could shift the outlook to bullish, with potential resistance at $80, $84, $89, and the $93–$95 range.
Written by Razan Hilal, CMT
Follow on X: @Rh_waves
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Outlook: XAU/USD hit hard as US yields, dollar resume ascent
A stronger dollar, surging front-end yields and renewed geopolitical tension have combined to push gold back towards key technical support.
S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.


USD/JPY Weekly Outlook: Payrolls loom as US rates remain the dominant driver
Strong US growth and hawkish Fed pricing continue to support USD/JPY, while intervention risk appears to be kicking in at lower levels
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.