



GBP/USD forecast, FTSE forecast: Two trades to watch
GBP/USD rises ahead of US GDP. FTSE struggles for direction, Barclays jumps.
Share this:
GBP/USD rises ahead of US GDP
- No UK data, focus on USD
- US GDP forecast to slow to 2% QoQ annualized
- GBPUSD rises towards 1.25
GBP/USD is rising for a second straight day as it grinds higher towards 1.25. There is no high-impacting UK economic data due to be released today, and there are no Bank of England speakers scheduled. As a result, the focus is expected to be on the USD and US GDP data.
The US dollar traded under pressure in recent sessions amid concerns over recession in the US. While US durable goods orders jumped, the underlying trend showed weakness in demand for US-made goods, pointing to a softer manufacturing sector. Earlier in the week USD consumer confidence fell to a nine-month low.
Attention now tends to US GDP data for further clues over a possible slowdown in the world's largest economy expectations are for GDP to rise 2% QoQ annualized, a slowdown from 2.4%. Weak growth could fuel downturn concerns.
The data comes ahead of core PCE inflation figures tomorrow and the FOMC rate decision next week.
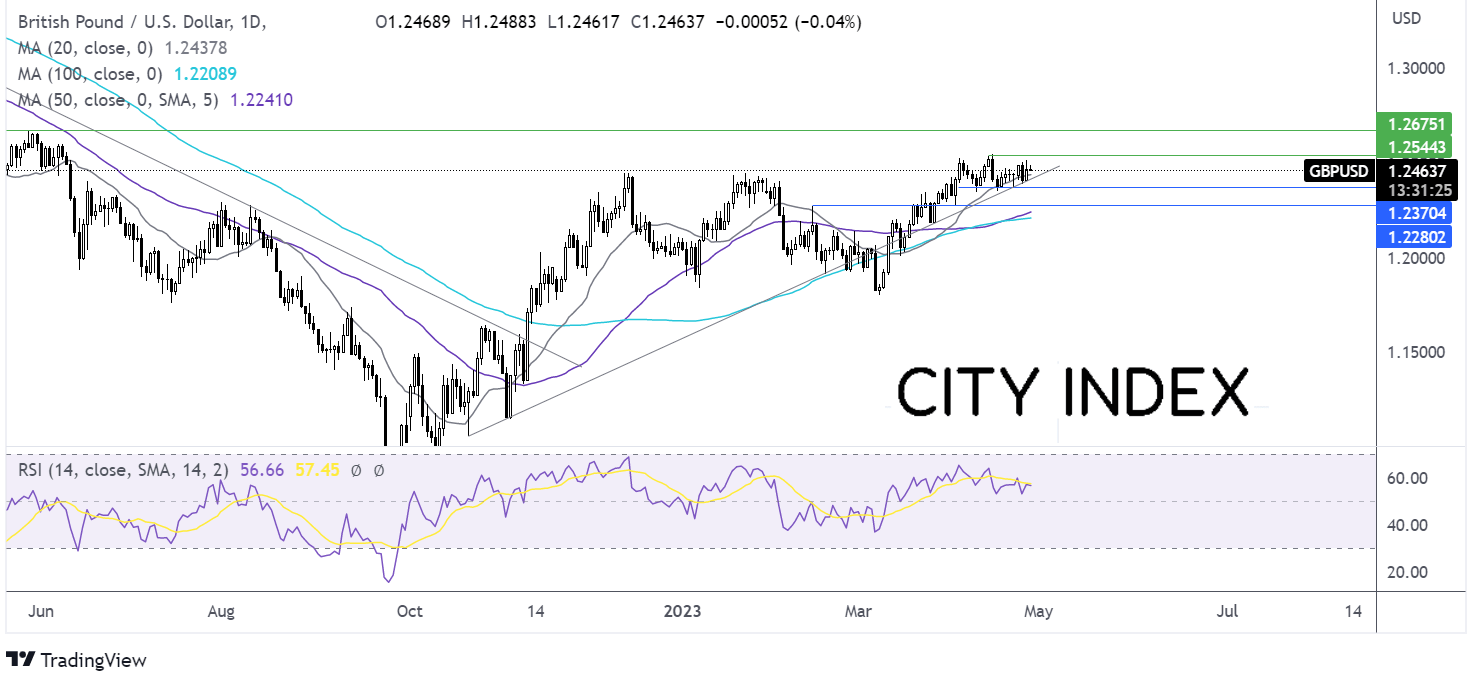
Where next for GDPUSD?
GBPUSD has risen off the rising trendline support at 1.24, rising back above the 20 sma. This, combined with the RSI above 50 keeps buyers hopeful of gains. Buyers will look for a rise above 1.2515, yesterday’s high, to attack 1.2545, the 2023 high, signalling a breakout. Above here, 1.26 comes into play.
On the flip side. Sellers could look for a fall below 1.24 yesterday’s low and 1.2385 the weekly low negate the near-term uptrend and open the door to 1.2275 the April low.
FTSE struggles for direction, Barclays jumps
- Barclays rises 3% as profits jump 27%
- NIM rises to 3.2%
- FTSE finds support at 7818
The FTSE is set to open lower with earnings in focus as investors digest the latest figures from Barclays.
The bank posted a 27% rise in profits as rising interest rates offset weakness in the investment banking arm.
Net profits rose to £1.8 billion up from £1.4 billion in the same period in 2022, beating forecasts by around £400 million. Meanwhile, revenue jumped 11% to £7.2 billion, ahead of the £6.8 billion forecast.
UK interest rates at a 15-year high in the UK resulted in a solid rise in net interest margin. At the same time, bad loan reserves are not accelerating as dramatically as feared. Barclays set aside £524 million for bad loans and said that there was a limited deterioration, with impairments still at a historically low level.
With the cost of living crisis ongoing, inflation still in double digits and the BoE set to hike rates further, there is still a potential for bad loan charges to increase further in coming quarters.
The investment banking arm was the weak link, with profits falling. Equity trading profits tumbled 33%, while fixed-income trading rose 9%. Advisory fees were also harder to come by, dropping 7%.
The results come as jitters surrounding the banking sector remain, particularly stateside, where regional banks are showing heavy deposit outflows.
Looking ahead, there is no high impacting UK economic data US earnings and GDP data could drive sentiment.
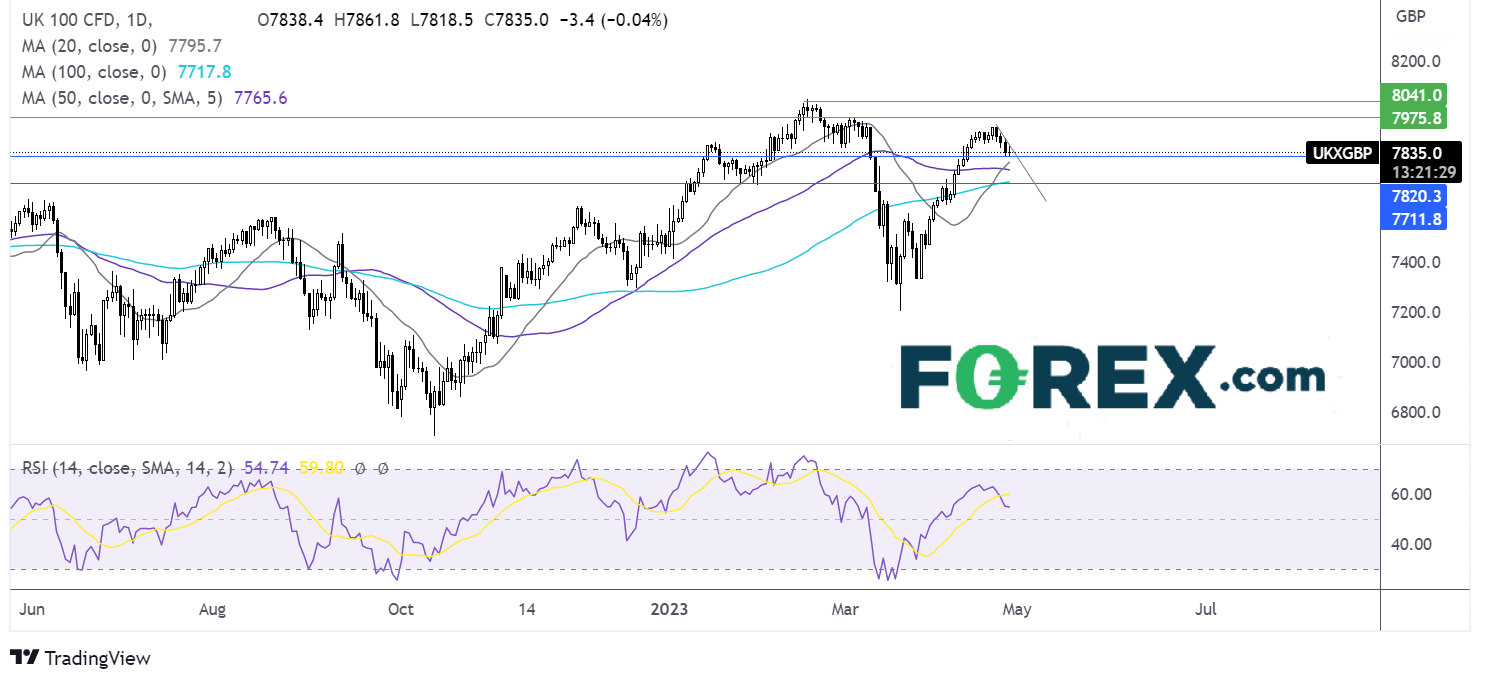
Where next for the FTSE100?
The FTSE has been trending lower across the week but closed off the low yesterday, and the doji candle today highlight the indecision.
Sellers will look for a fall below 7818 to create a lower low and expose the 20 sma at 7795 and 7700 the late January low, and the 100 sma.
On the flipside, buyers could be encouraged by the 20 sma rising above the 50 sma and the RSI above 50. A break above the falling trendline at 7860 could signal a breakout and brings 7940 the April high.

Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.