




Sterling unconvinced by Johnsons certainty
Boris Johnson won a court case in Scotland…not that he needed to; according to him
Share this:

Boris Johnson won a court case in Scotland…not that he needed to; according to him
Brexit is on course for 31st October, the only independent variable being whether or not the EU will agree a deal beforehand, says the prime minister. If only market participants could be as certain. The government has won a case in a Scottish court that could have tied Boris Johnson’s hands even more tightly to the Benn Act—the law that aims to prevent Britain from crashing out of the EU. The Judge noted “unequivocal assurances” that the government would comply with the law. The QC for campaigners who brought the case said there would be an appeal. So another possible avenue of clarity, however tenuous, stays befuddled.
Johnson himself is a source of abundant uncertainty, continuing to contradict the government and—to an extent—himself. The government has repeatedly said it will obey the law requiring the request of a Brexit delay if no deal is agreed as the 31st October deadline nears. On Friday, government lawyers confirmed that any request letter would be sent by 19th October. But the latest in a string of anonymous briefings said Johnson’s determination to leave on that date, deal or no deal, cannot be thwarted.
These numerous—apparently concerted—government echoes of Johnson’s stance come alongside a growing tide of litigation including the hearing Downing Street won today. Another case that could force the government to send the letter seeking an extension even if Johnson refuses to, is due to be heard on Tuesday. Meanwhile, the prime minister is reportedly continuing a round robin of phone calls to persuade EU leaders whilst Britain’s lead negotiator pushes the case in Brussels.
The message from there is now that the government has till Friday to move towards a deal that the EU can accept. Pragmatic politics thereby look to be among the government’s last remaining gambits, particularly as opposition parties continue to block an early general election ‘escape route’.
Against this backdrop, options trades expiring around the time of the EU’s forthcoming summit suggest speculators and hedgers see heightened risks rising further. Some complex trades covering 17th-18th October are now seeing the highest demand since after the 2016 referendum. Despite this, irresolute sterling trends are keeping the pound well above September lows. With 24 days to go, this may turn out to be madness, in hindsight.
Key Brexit dates ahead

Chart thoughts
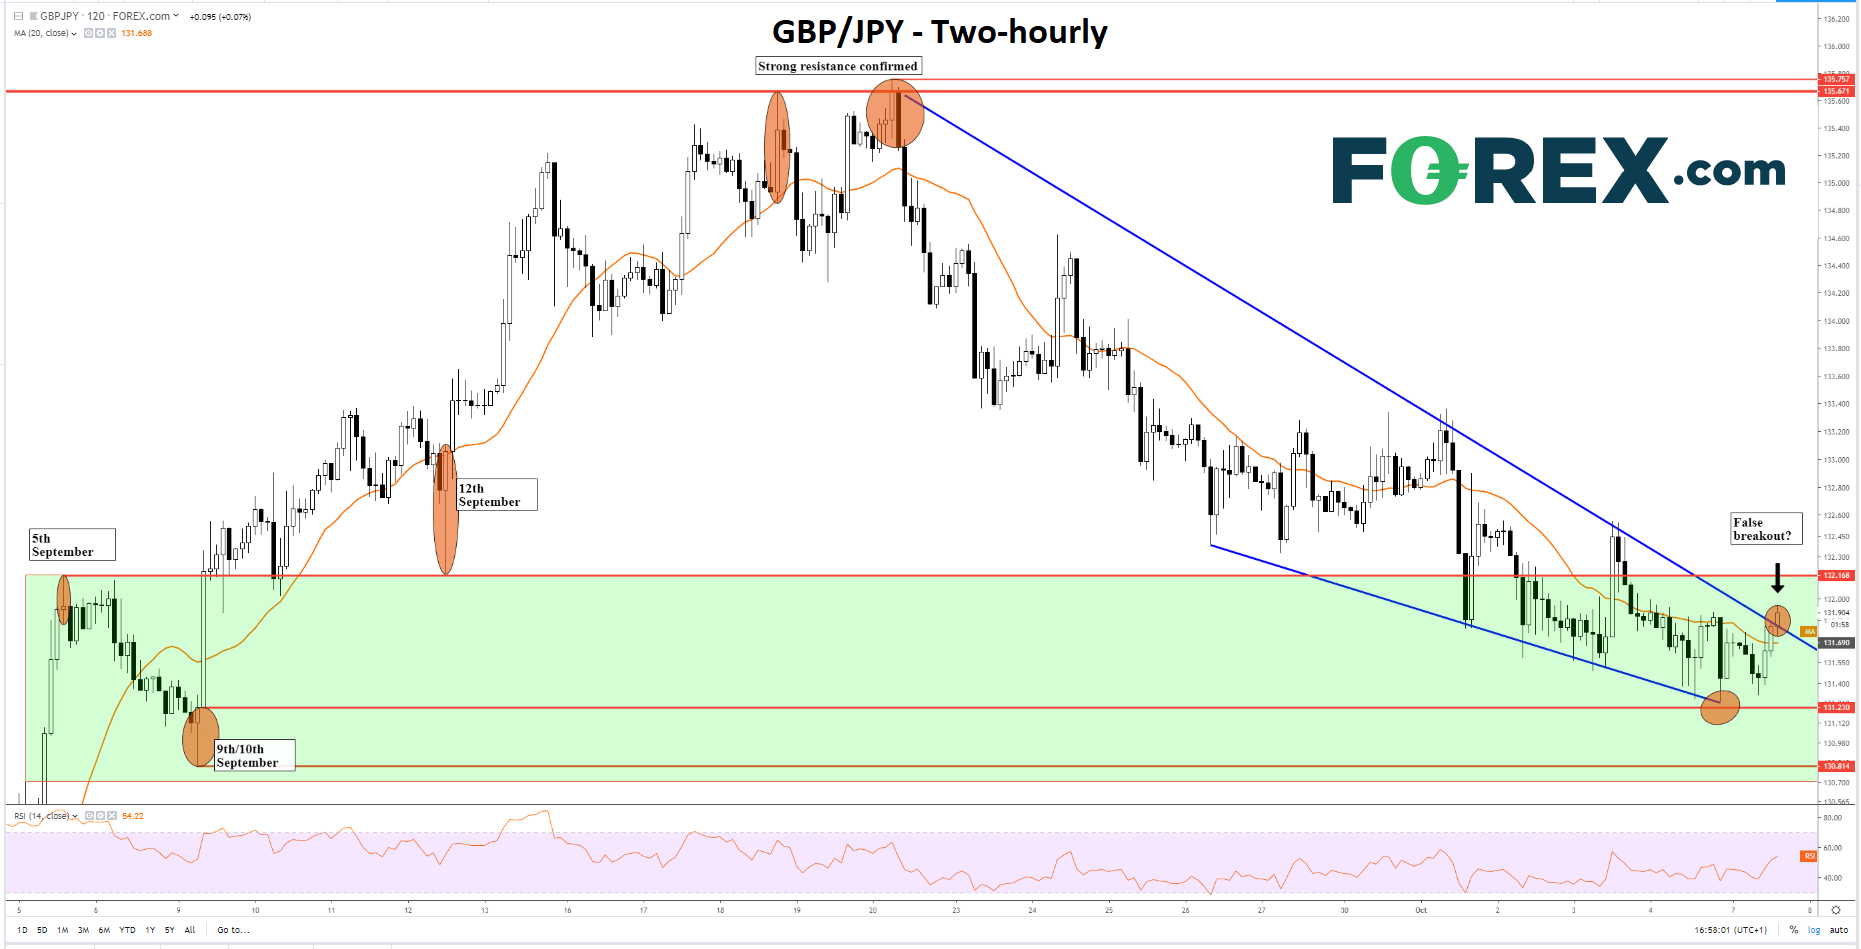
Sterling strength ought to be magnified within the risk-sensitive GBP/JPY pair, but even here, evidence that buyers are anywhere near in control is lacking. Yes, the pair shows signs of completing the consolidation of the up leg that peaked in the high ¥135s (confirming 24th July’s whipsaw high as the region of strong resistance). But better confirmation is required than what is beginning to look like a false break out of the wedge that developed since 18th, 20th and 21st September tops. Sterling can pull away here, though would need to surpass ¥132 and thereabouts, as tagged twice last month as support. That level could now pose resistance. Short-term trends aren’t supportive. They’re pointing lower, including the 20-interval moving average in the chart below. The pound trades above it, but can be expected to revert below, per recent pattern. All the above said, there’s little doubt that GBP/JPY has established decent support in the current region, chiefly from aggressive defence of ¥130/131 last month, with corroboration just south of ¥131 at Sunday’s open. But this month’s base from the definitive February to August downtrend lies around ¥126.6-¥126.7. It make sense to think of a failure to withstand downward pressures on current levels as pointing to a move down to last month’s base.
GBP/JPY – Two-hourly [07/10/2019 17:01:00]
Source: FOREX.com
Boris Johnson won a court case in Scotland…not that he needed to; according to him
Brexit is on course for 31st October, the only independent variable being whether or not the EU will agree a deal beforehand, says the prime minister. If only market participants could be as certain. The government has won a case in a Scottish court that could have tied Boris Johnson’s hands even more tightly to the Benn Act—the law that aims to prevent Britain from crashing out of the EU. The Judge noted “unequivocal assurances” that the government would comply with the law. The QC for campaigners who brought the case said there would be an appeal. So another possible avenue of clarity, however tenuous, stays befuddled.
Johnson himself is a source of abundant uncertainty, continuing to contradict the government and—to an extent—himself. The government has repeatedly said it will obey the law requiring the request of a Brexit delay if no deal is agreed as the 31st October deadline nears. On Friday, government lawyers confirmed that any request letter would be sent by 19th October. But the latest in a string of anonymous briefings said Johnson’s determination to leave on that date, deal or no deal, cannot be thwarted.
These numerous—apparently concerted—government echoes of Johnson’s stance come alongside a growing tide of litigation including the hearing Downing Street won today. Another case that could force the government to send the letter seeking an extension even if Johnson refuses to, is due to be heard on Tuesday. Meanwhile, the prime minister is reportedly continuing a round robin of phone calls to persuade EU leaders whilst Britain’s lead negotiator pushes the case in Brussels.
The message from there is now that the government has till Friday to move towards a deal that the EU can accept. Pragmatic politics thereby look to be among the government’s last remaining gambits, particularly as opposition parties continue to block an early general election ‘escape route’.
Against this backdrop, options trades expiring around the time of the EU’s forthcoming summit suggest speculators and hedgers see heightened risks rising further. Some complex trades covering 17th-18th October are now seeing the highest demand since after the 2016 referendum. Despite this, irresolute sterling trends are keeping the pound well above September lows. With 24 days to go, this may turn out to be madness, in hindsight.
Key Brexit dates ahead
Chart thoughts
Sterling strength ought to be magnified within the risk-sensitive GBP/JPY pair, but even here, evidence that buyers are anywhere near in control is lacking. Yes, the pair shows signs of completing the consolidation of the up leg that peaked in the high ¥135s (confirming 24th July’s whipsaw high as the region of strong resistance). But better confirmation is required than what is beginning to look like a false break out of the wedge that developed since 18th, 20th and 21st September tops. Sterling can pull away here, though would need to surpass ¥132 and thereabouts, as tagged twice last month as support. That level could now pose resistance. Short-term trends aren’t supportive. They’re pointing lower, including the 20-interval moving average in the chart below. The pound trades above it, but can be expected to revert below, per recent pattern. All the above said, there’s little doubt that GBP/JPY has established decent support in the current region, chiefly from aggressive defence of ¥130/131 last month, with corroboration just south of ¥131 at Sunday’s open. But this month’s base from the definitive February to August downtrend lies around ¥126.6-¥126.7. It make sense to think of a failure to withstand downward pressures on current levels as pointing to a move down to last month’s base.
GBP/JPY – Two-hourly [07/10/2019 17:01:00]
Source: City Index
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

AUD/USD Q4 Outlook: RBA and Fed Hikes Set the Tone
AUD/USD enters Q4 with RBA and Fed hikes in focus as sticky inflation, rising unemployment and US dollar strength shape the Australian dollar.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.