



Two trades to watch: GBP/USD, Oil
GBP/USD awaits the US non-farm payroll around 1.1550. Oil rises ahead of the OPEC+ meeting next week.
Share this:

GBP/USD awaits the NFP
GBP/USD fell 0.6% in the previous session, falling to a new 2.5-year low as recession fears ramped up. UK manufacturing activity contracted at the slowest pace since the mid-pandemic.
Today the pair has steadied around 1.1550 as attention turns to the US non-farm payroll report. Expectations are for 298k jobs to be added in August, a solid reading but down slightly from July’s impressive 528k. Average wages are expected to rise to 5.3% YoY and unemployment to hold steady at 3.5%.
The jobs data this week has been mixed with jobless claims unexpectedly falling and vacancies unexpectedly rising. However, the ADP private payrolls were softer than forecast. Even so, it’s worth noting that the NFP report has beaten estimates over the past three months, showing few signs of high inflation and economic weakness seeping into the jobs market. At some point, this will start to show through.
The CME fed watch tool shows the market is pricing in a 74% likelihood of a 0.75% rate hike this month. A strong jobs report could well cement expectations for a jumbo-sized hike. This could see the USD climb higher.
A stronger or weaker jobs report may not deter the USD from its purposeful rise higher. Given the economic backdrop in Europe, the UK, and China, there are few better alternatives.
Where next for GBP/USD?
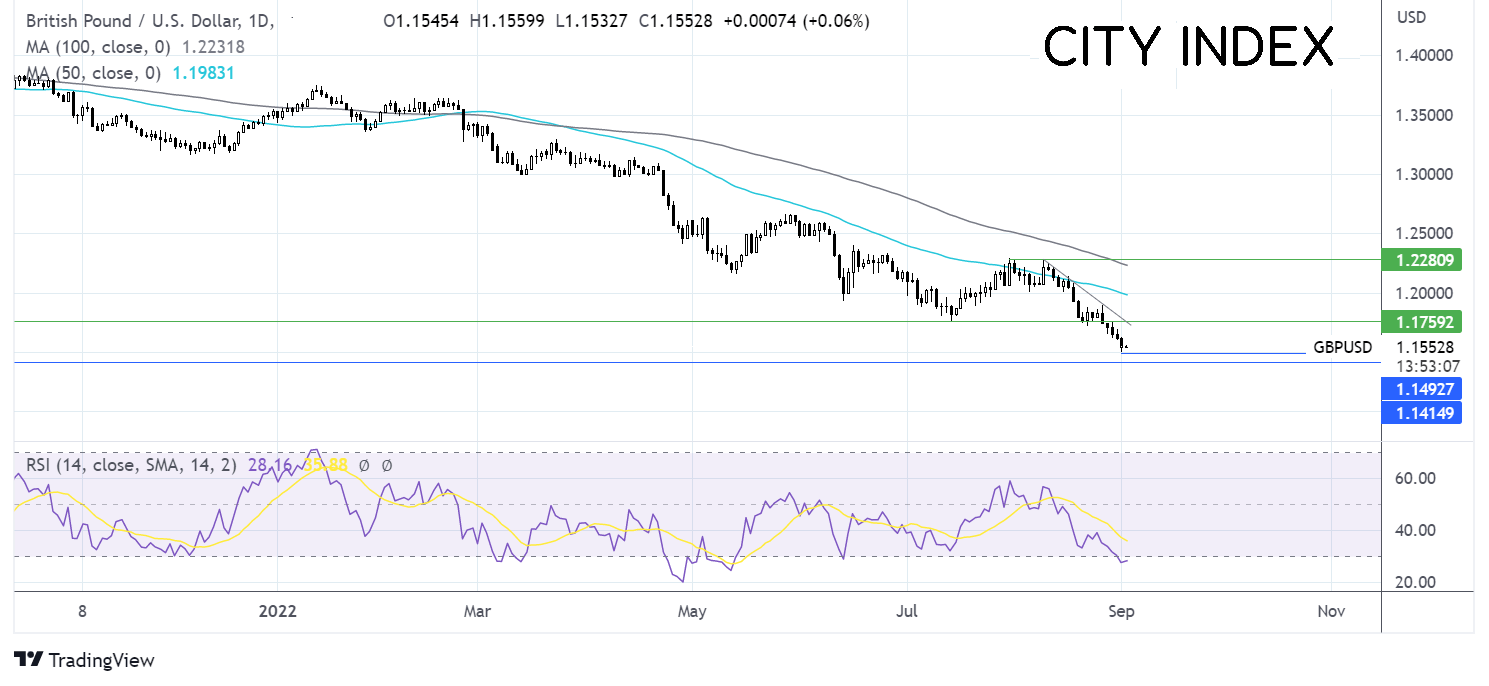
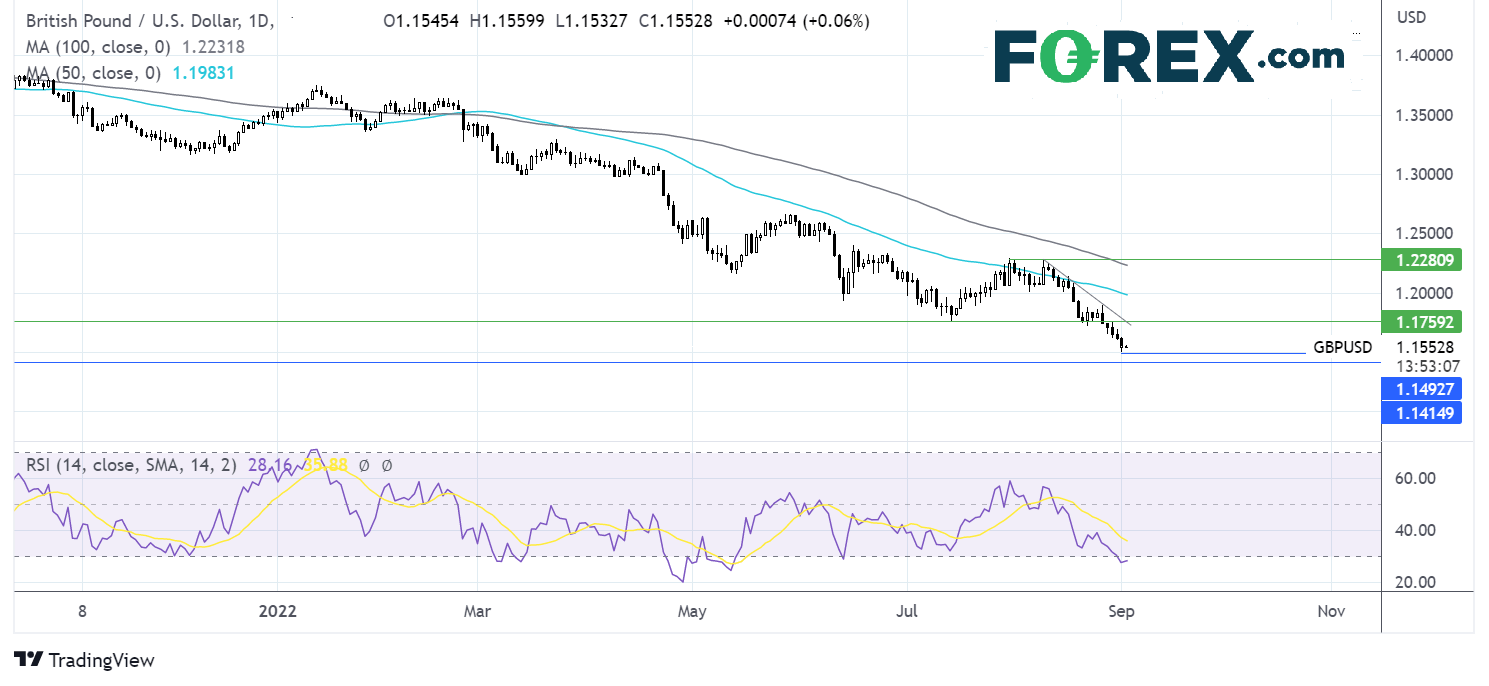
GBP/USD has fallen for the past six sessions, pulling the pair to 1.15, a level which is now acting as an immediate support. If the bulls fail to defend this level, the pair could extend its selloff to 1.1412, the May pandemic low.
It’s worth noting that the RSI is tipping into oversold territory so that we could see some consolidation. If buyers resurface, resistance can be seen at 1.1870, the July low. A rise above here exposes the 50 sma at 1.1950
Oil rises ahead of OPEC+ meeting next week
After three days of losses, oil prices are heading cautiously higher, helped by the more upbeat mood in the market and as investors look to next week’s OPEC+ meeting.
The oil cartel is expected to discuss its output plans at the meeting and will do so as China lockdown more cities as COVID spreads and fears of a global economic slowdown intensify.
While worries over China and weaker global demand have dragged oil prices over 5% lower this week, they could give OPEC+ reason to cut oil output.
Saudi Arabia has already floated the idea of an output cut to tame volatile prices and a disconnect between the futures market and the physical market. Crude oil now trades 30% off the June highs.
Where next for oil prices?
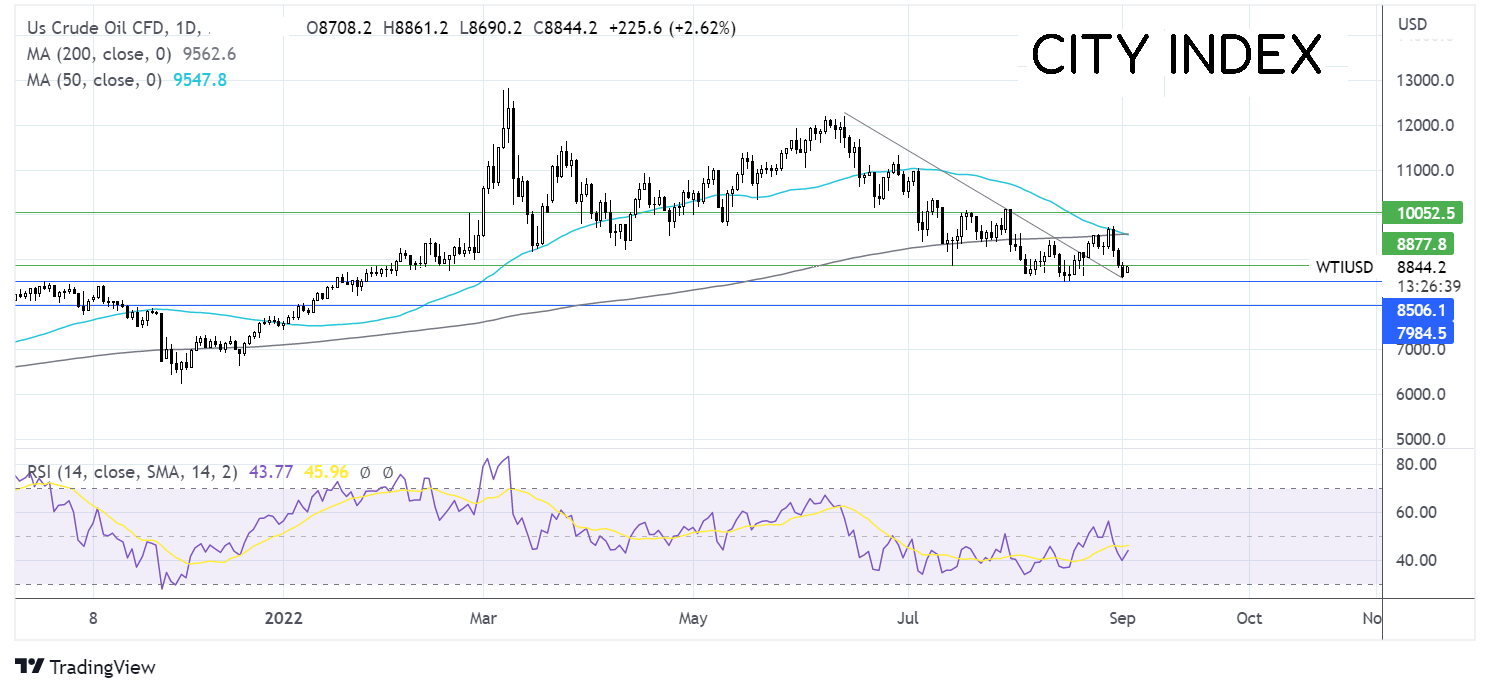
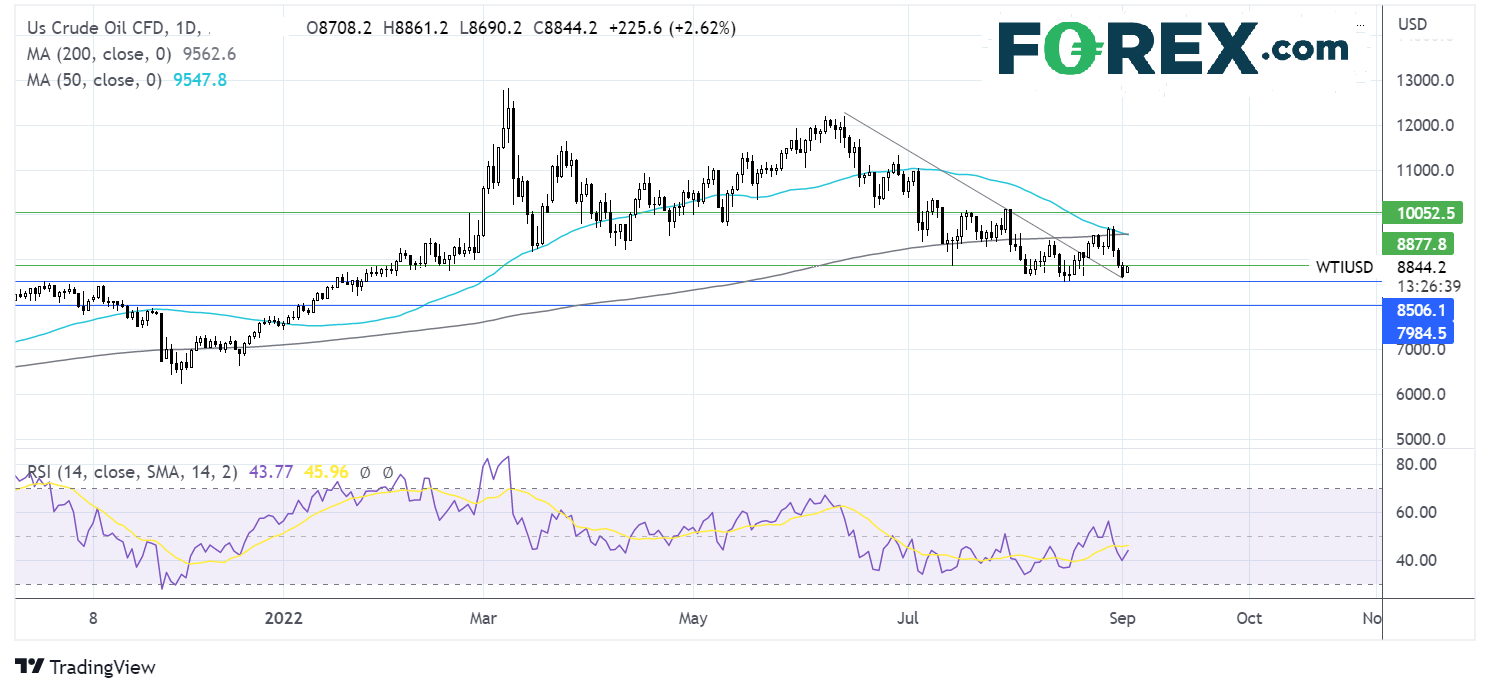
Crude oil found support on the multi-month falling trendline at 85.80 and has rebounded higher, testing resistance at 88.50, the July 14 low.
While the RSI remains below 50 and the 50 sma appears to be crossing below the 200 sma in a death cross formation, the broader outlook is still bearish. Sellers need to break below 85.00, the August low, to extend the bearish trend towards 80.00.
Meanwhile, if bears fail to defend 88.50, buyers could push the price towards 95.30 the 50 and 200 sma, negating the near-term downtrend.
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.


EUR/USD forecast: Dollar strength puts 1.1000 support in the spotlight | Currency Pair of the Week
The dollar extended its recent advance at the start of the week, with weakness across risk-sensitive assets reinforcing demand for the US currency. US equity futures slipped ahead of Nvidia’s earnings on Tuesday and an expected stock market debut by Anthropic later this week. Both events represent important tests for an AI trade that has become increasingly vulnerable to shifts in sentiment. In FX, EUR/USD nearly tested the psychologically important 1.1000 level, before bouncing modestly off its lows.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.