



US open: Stocks edge higher as Biden arrives at NATO, EU Summits
Stocks advance cautiously with all eyes on Biden's meetings in Europe. Oil prices steady and US data comes in mixed.
Share this:

US futures
Dow futures +0.3% at 34470
S&P futures +0.4% at 4474
Nasdaq futures +0.5% at 14523
In Europe
FTSE +0.1% at 7460
Dax -0.1% at 14350
Euro Stoxx -0.2% at 3864
Learn more about trading indices
Are more sanctions coming?
US stocks are set to rise cautiously higher on the open as President Biden meets with European leaders to discuss further measures to put economic pressure on Russia.
President Biden will be meeting with NATO, the G7, and European leaders later in the day, which could result in more sanctions being imposed on Russia.
The oil market is holding steady, suggesting that the general expectation is that Russian oil will be left out of any news restrictions.
The meeting comes a month after the war started and soaring commodity prices. Inflation, which was already a problem at the start of the year, has become a massive headache for central banks amid fears of slowing growth. Fed speakers this week have been banging the hawkish drum, which is expected to continue.
Data was a mixed bag; durable goods fell a much larger than expected 2.3% YoY in February, after rising 1.6% in January.
Meanwhile, jobless claims showed that the labour market recovery was on track, dropping below 200k to 187k.
In corporate news:
GameGroup trades lower before the bell after Boston Consulting Group sued it in an attempt to reclaim $30 million in unpaid fees.
Where next for the Dow Jones?
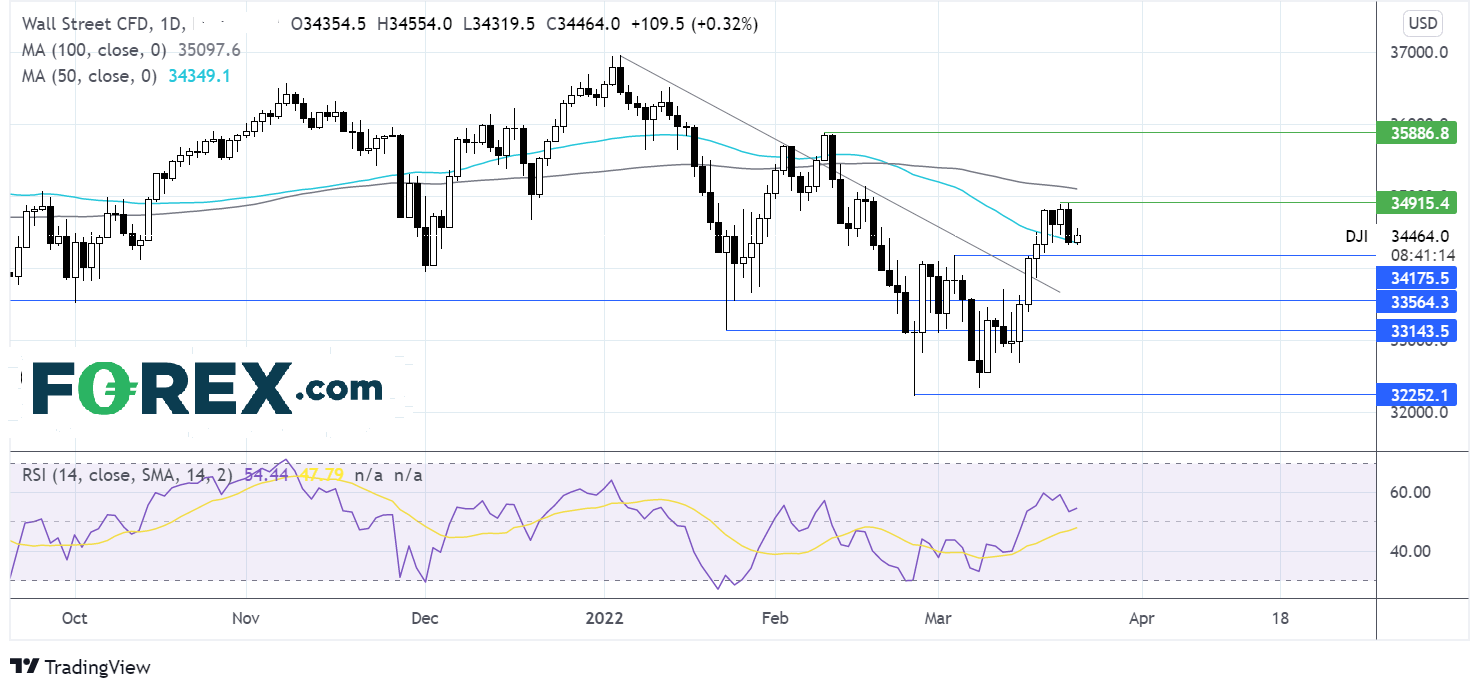
The Dow Jones rebounded lower from resistance at 34900 yesterday before finding support at 34350 the 50 SMA, which continues to hold today. The RSI suggests that there is still more upside to come. However, buyers will need to break above resistance at 34900 to expose the 100 sma at 35100, also the February 16 high. Sellers will look for a move below the 50 SMA to test 34200, with a move below here negating the near-term uptrend.

FX markets USD rises, GBP holds steady.
USD is heading higher, boosted by growing hawkish expectations. This week, Fed speakers have been out in force, speaking of the need to hike interest rates more aggressively. The CME FedWatch tool now prices in a 68.3% probability of a 50-basis point rate hike in May. There are plenty more Fed speakers due today who could keep the price buoyed.
GBPUSD is holding steady versus the strong USD after the service sector PMI unexpectedly rose to 61, up from 60.5. Expectations had been for a decline to 59. However, the manufacturing PMI came in below forecasts at 55.5, down from 58.
GBP/USD +0.01% at 1.3213
EUR/USD -0.08% at 1.0995
Oil steadies as more sanctions on oil are unlikely for now
Oil prices are holding steady after posting gains of over 4% yesterday and as investors await news from President Biden’s meeting with European leaders.
Oil prices are steady as any news sanctions are unlikely to include Europe banning Russian oil imports, given the high dependency.
Data from the EIA showed that US crude oil reserves unexpectedly fell last week when analysts had been forecasting a rise.
Separately, progress on the Iran nuclear deal appears to have stalled. Without a substantial supply of oil into the market, the oil price will remain at these levels or continue to rise.
WTI crude trades -0.5% at $114.14
Brent trades -0.58% at $118.65
Learn more about trading oil here.
Looking ahead
15:00 Fed Bostic speaks
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit level.
- Place the trade.
US futures
Dow futures +0.3% at 34470
S&P futures +0.4% at 4474
Nasdaq futures +0.5% at 14523
In Europe
FTSE +0.1% at 7460
Dax -0.1% at 14350
Euro Stoxx -0.2% at 3864
Are more sanctions coming?
US stocks are set to rise cautiously higher on the open as President Biden meets with European leaders to discuss further measures to put economic pressure on Russia.
President Biden will be meeting with NATO, the G7, and European leaders later in the day, which could result in more sanctions being imposed on Russia.
The oil market is holding steady, suggesting that the general expectation is that Russian oil will be left out of any news restrictions.
The meeting comes a month after the war started and soaring commodity prices. Inflation, which was already a problem at the start of the year, has become a massive headache for central banks amid fears of slowing growth. Fed speakers this week have been banging the hawkish drum, which is expected to continue.
Data was a mixed bag; durable goods fell a much larger than expected 2.3% YoY in February, after rising 1.6% in January.
Meanwhile, jobless claims showed that the labour market recovery was on track, dropping below 200k to 187k.
In corporate news:
GameGroup trades lower before the bell after Boston Consulting Group sued it in an attempt to reclaim $30 million in unpaid fees.
Where next for the Dow Jones?
The Dow Jones rebounded lower from resistance at 34900 yesterday before finding support at 34350 the 50 SMA, which continues to hold today. The RSI suggests that there is still more upside to come. However, buyers will need to break above resistance at 34900 to expose the 100 sma at 35100, also the February 16 high. Sellers will look for a move below the 50 SMA to test 34200, with a move below here negating the near-term uptrend.
FX markets USD rises, GBP holds steady.
USD is heading higher, boosted by growing hawkish expectations. This week, Fed speakers have been out in force, speaking of the need to hike interest rates more aggressively. The CME FedWatch tool now prices in a 68.3% probability of a 50-basis point rate hike in May. There are plenty more Fed speakers due today who could keep the price buoyed.
GBPUSD is holding steady versus the strong USD after the service sector PMI unexpectedly rose to 61, up from 60.5. Expectations had been for a decline to 59. However, the manufacturing PMI came in below forecasts at 55.5, down from 58.
GBP/USD +0.01% at 1.3213
EUR/USD -0.08% at 1.0995
Oil steadies as more sanctions on oil are unlikely for now
Oil prices are holding steady after posting gains of over 4% yesterday and as investors await news from President Biden’s meeting with European leaders.
Oil prices are steady as any news sanctions are unlikely to include Europe banning Russian oil imports, given the high dependency.
Data from the EIA showed that US crude oil reserves unexpectedly fell last week when analysts had been forecasting a rise.
Separately, progress on the Iran nuclear deal appears to have stalled. Without a substantial supply of oil into the market, the oil price will remain at these levels or continue to rise.
WTI crude trades -0.5% at $114.14
Brent trades -0.58% at $118.65
Looking ahead
15:00 Fed Bostic speaks
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.