




Weekly COT Report: Sterling extends short-covering rally
The British pound was the only major to close higher against the greenback last week, and speculative positioning suggests short covering remains the main driver.
Share this:
As of Tuesday 4th January 2022
- Traders trimmed their net-long exposure to the US dollar by -$0.27 billion, taking bullish exposure down slightly to +$19.5 billion
- Long exposure to the US dollar rose to its highest level since October 2019 (although it is just at a 5-week high if adjusted for open interest)
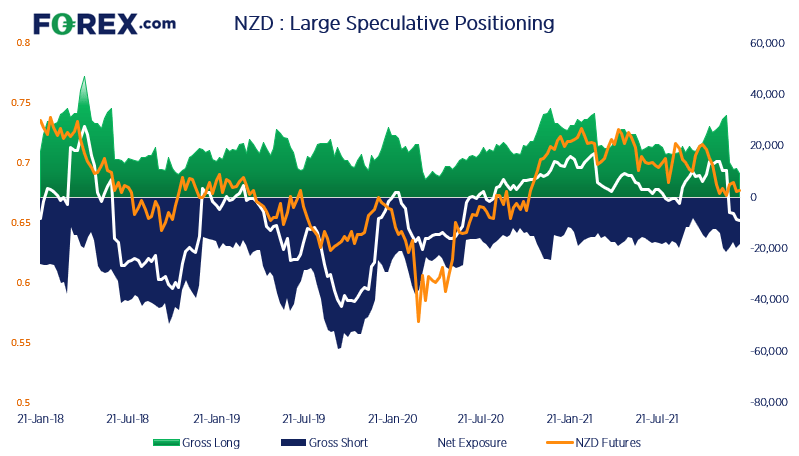
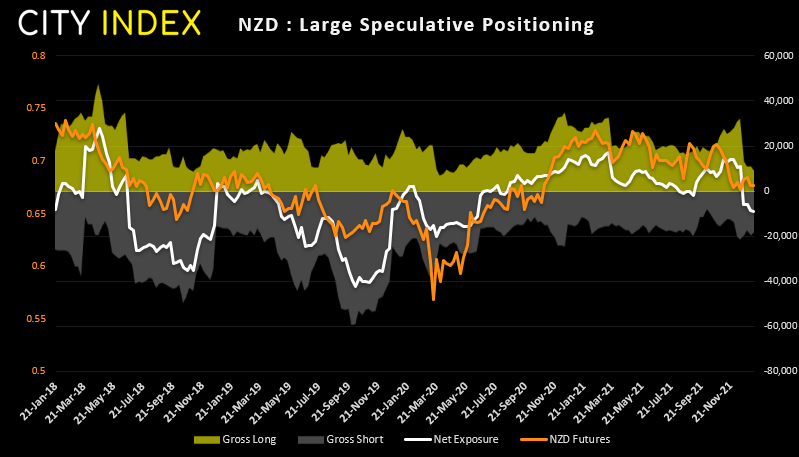
- NZD futures were net short for a fourth week and traders were their most bearish on the Kiwi dollar since June 2020
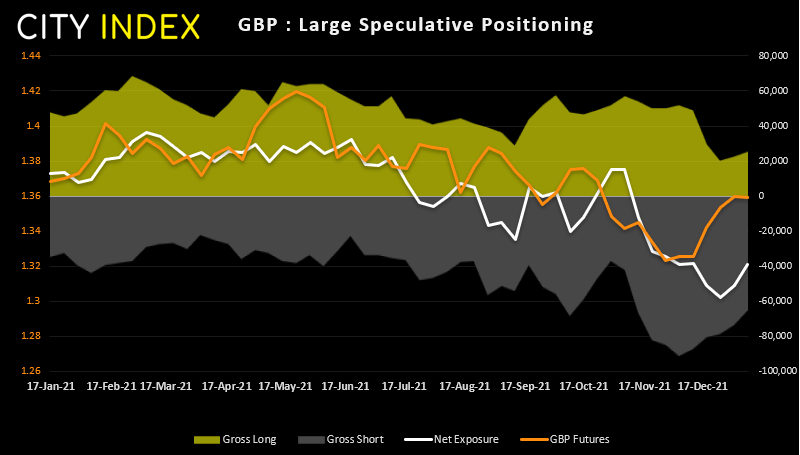
- Short exposure to GBP futures fell for a second consecutive week as its short-covering rally resumed
Sterling extends short-covering rally for a second week
Traders remain net-short GBP futures, as they have done for over 9-weeks now. Yet more may be gleaned from looking at the inflection point of gross short exposure, as bearish positioning appeared to hit a sentiment extreme back in early December. Gross shorts have been trimmed for five consecutive weeks, and gross longs have been increased the past two as prices have rallied. So GBP now appears to be in a corrective phase on the weekly chart as traders reconsider their grim view of the Omicron variant, as it may not turn out to be as dire as originally feared one month ago.
Traders remain pessimistic on the Kiwi dollar
Considering RBNZ remain a relatively hawkish central bank it’s a little surprising to see NZD at net-short exposure with large speculators. But then we do have a hawkish Fed to contend with over the coming months, at which point we suspect yield differentials will matter again and favour NZD over USD. Over the near-term we note that gross shorts sit around 20k contract, and this is a level which has held fairly steady since November, so we have an initial clue that bears could being to lose momentum. That said, gross longs are also at their lowest level since April 2020 (and trending lower) so we’d want to see a pickup of long interest before calling a reversal on the weekly charts, but this is something to consider over the coming weeks or months.
As of Tuesday 4th January 2022
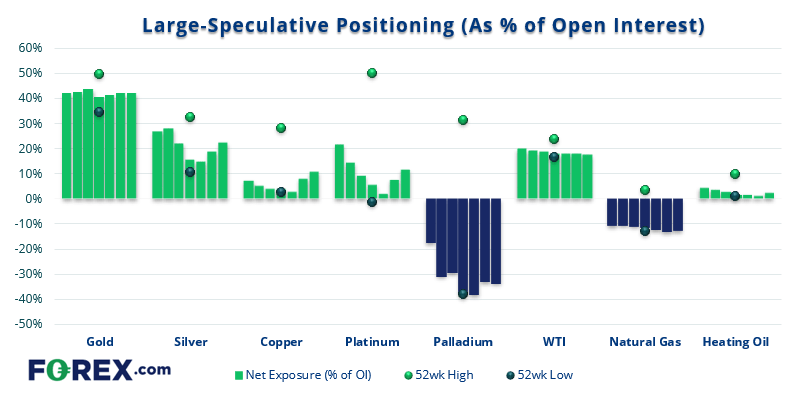
- Net-long exposure to copper futures rose for a second consecutive week
- Traders increased net-long exposure to silver futures to a 5-week high, although bearish price action since the report was compiled suggests many (if not all of these new longs) have been closed out
- Bullish interest also rose on platinum futures, with net-long exposure rising to a 6-week high
Copper bulls return to the table?
As noted above, net-long exposure to copper futures rose for a second consecutive week. Whilst it is still early days, we like how gross shorts have remained steady (lack of fresh bearish interest), and how the renewed bullish interest backs up our longer-term view that a base has been built around $4 in August and e we anticipate a breakout from its multi-month sideways range. What we would like to see in the weeks ahead to reaffirm this view is for bearish interest to decline whilst new longs continue to be initiated.
As of Tuesday 4th January 2022
- Traders trimmed their net-long exposure to the US dollar by -$0.27 billion, taking bullish exposure down slightly to +$19.5 billion
- Long exposure to the US dollar rose to its highest level since October 2019 (although it is just at a 5-week high if adjusted for open interest)
- NZD futures were net short for a fourth week and traders were their most bearish on the Kiwi dollar since June 2020
- Short exposure to GBP futures fell for a second consecutive week as its short-covering rally resumed
This content will only appear on Forex websites! Read our guide on how to interpret the weekly COT report
Sterling extends short-covering rally for a second week
Traders remain net-short GBP futures, as they have done for over 9-weeks now. Yet more may be gleaned from looking at the inflection point of gross short exposure, as bearish positioning appeared to hit a sentiment extreme back in early December. Gross shorts have been trimmed for five consecutive weeks, and gross longs have been increased the past two as prices have rallied. So GBP now appears to be in a corrective phase on the weekly chart as traders reconsider their grim view of the Omicron variant, as it may not turn out to be as dire as originally feared one month ago.
Traders remain pessimistic on the Kiwi dollar
Considering RBNZ remain a relatively hawkish central bank it’s a little surprising to see NZD at net-short exposure with large speculators. But then we do have a hawkish Fed to contend with over the coming months, at which point we suspect yield differentials will matter again and favour NZD over USD. Over the near-term we note that gross shorts sit around 20k contract, and this is a level which has held fairly steady since November, so we have an initial clue that bears could being to lose momentum. That said, gross longs are also at their lowest level since April 2020 (and trending lower) so we’d want to see a pickup of long interest before calling a reversal on the weekly charts, but this is something to consider over the coming weeks or months.
As of Tuesday 4th January 2022
- Net-long exposure to copper futures rose for a second consecutive week
- Traders increased net-long exposure to silver futures to a 5-week high, although bearish price action since the report was compiled suggests many (if not all of these new longs) have been closed out
- Bullish interest also rose on platinum futures, with net-long exposure rising to a 6-week high
Copper bulls return to the table?
As noted above, net-long exposure to copper futures rose for a second consecutive week. Whilst it is still early days, we like how gross shorts have remained steady (lack of fresh bearish interest), and how the renewed bullish interest backs up our longer-term view that a base has been built around $4 in August and e we anticipate a breakout from its multi-month sideways range. What we would like to see in the weeks ahead to reaffirm this view is for bearish interest to decline whilst new longs continue to be initiated.

How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.
USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.