Gold managed to bounce off its lows after initially extending its decline for the 4th day, though there wasn’t too much enthusiasm from the bulls to push the metal decisively higher, when this report was written just after the US cash market open. Once again, price held above key support in the $4070ish to $4110ish area, which has held on several occasions in recent weeks. While this support zone holds, the bulls have some hope that the metal may be able to revive its prior bullish trend, after spending much of the year in long term consolidation or short term bear trend. The metal has fallen around 26% from its January highs, so it may be due for a rally soon, particularly as the selling momentum has clearly eased in recent weeks. But a decisive trigger still remains elusive to turn the gold forecast bullish. Can that change in the coming days?
What is preventing gold from making a more decisive move?
Gold is being pulled in two directions by the same macro force: inflation. Persistent price pressures should, in theory, strengthen demand for the metal as a store of value. But if inflation proves sticky enough to keep central banks hawkish, the resulting rise in real and nominal yields makes gold less attractive at the margin.
That tension is becoming increasingly important. Recent inflation readings in the US and UK, together with elevated oil prices, have revived concerns that interest rates may need to remain restrictive for longer than markets had hoped. Bond yields have responded accordingly. The US 10-year yield remains above 5%, and while yields have eased somewhat in recent sessions, they are still high enough to act as a meaningful constraint on gold.
This helps explain why the metal has struggled to sustain rallies despite the longer-term inflation and debasement arguments. Gold does not pay a yield, so when investors can earn relatively attractive returns from government bonds, the opportunity cost of holding the metal becomes harder to ignore.
Central bank buying provides long-term support
There is, however, another source of demand that is less sensitive to short-term movements in yields. Central-bank buying, particularly from the People’s Bank of China, continues to provide an important structural underpinning for the market. There is little evidence that official-sector demand is about to disappear as we approach the final months of the year.
Sustained central-bank accumulation can change the dynamics of a correction. If investors expect official-sector demand to remain strong, they may be more willing to buy weakness through ETFs, spot and futures markets. In other words, central-bank buying could help put a floor under gold even if the near-term macro backdrop remains difficult.
Gold still needs to prove the sellers are losing control
For now, though, the technical evidence remains bearish. Gold last week extended a correction that has now seen the metal post just two weekly gains over the past eight weeks.
That is not the sort of momentum against which I would want to anticipate a bottom, but the fact that a key support around $4,075-$4,100 area is continuing to hold makes me wonder if we are close to a bottom.
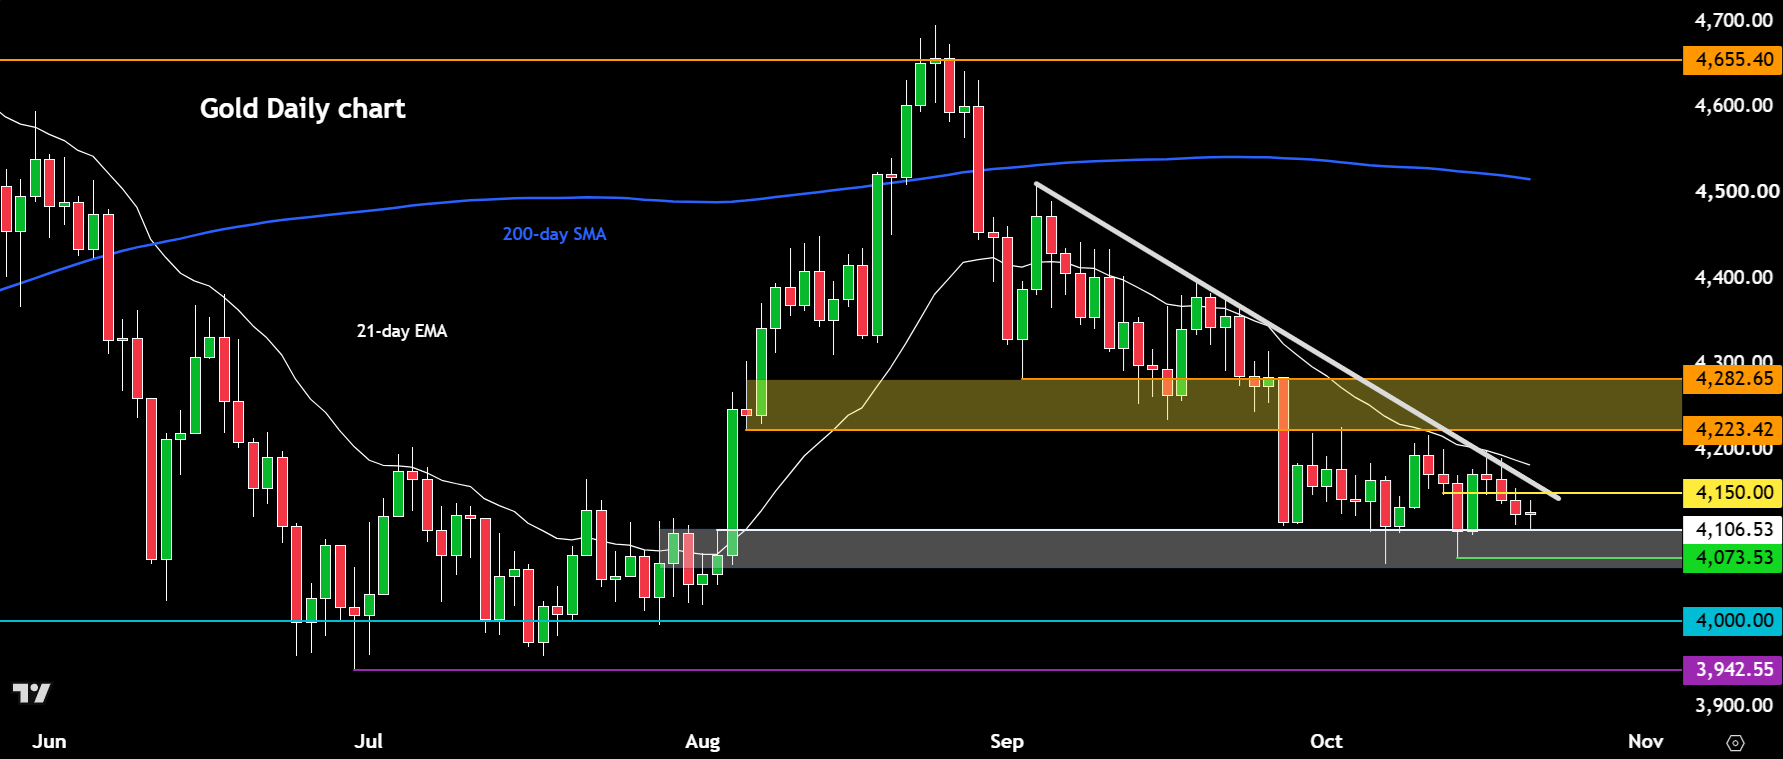
This area represents the base of the rally that began in early August. But the rebound has yet to alter the broader technical structure. There is a trend line connecting recent highs. A decisive break above it would suggest that downside momentum is beginning to fade. But I would not regard that alone as confirmation of a durable bottom.
Gold would still need to reclaim the $4,223-$4,260 region. A sustained move through that resistance zone would provide much stronger evidence that the correction is running its course and that buyers are beginning to regain control.
Gold forecast: Short-term downside risks persist but long-term is supportive
Until and unless the above scenario plays out, I would remain cautious and wouldn’t rule out a move lower instead, which remains a realistic scenario, particularly if oil prices stay elevated and Treasury yields resume their climb.
That said, the longer-term picture remains more constructive for gold forecast. Central-bank demand, concerns over currency debasement and the broader diversification case for holding gold have not disappeared simply because the metal is going through a correction.