- USD/JPY correlation with front-end U.S. yields remains strong
- Fed speeches and Treasury auctions in focus as data blackout continues
- Japan’s bond market could provide volatility
Summary
The relationship between USD/JPY and U.S. interest rates continues to strengthen, especially at the front end of the curve which is heavily influenced by shifts in monetary policy expectations. With no top-tier economic data on the calendar due to the ongoing U.S. government shutdown, that puts greater emphasis on Treasury auctions and speeches from Federal Reserve officials to drive direction in the week ahead.
Fed Pricing Key Market Driver
USD/JPY and Fed rate cut pricing have been essentially tied at the hip over the past month, signalling it should be the primary focus of anyone trading the pair in the week ahead.
You only need to look at the left-hand pane in the chart below, overlaying USD/JPY (black line) against the shape of the Fed funds futures curve (grey line, scale inverted) between November 2025 and December 2026. The latter indicates how many rate cuts in basis points are being priced by the end of next year, and it’s obvious there’s been a tight relationship between the two recently. The rolling 20-day correlation coefficient in the right-hand pane backs this up with a score of -0.88, hitting levels seen since early 2025. As Fed rate cut pricing has lifted, USD/JPY has typically fallen, and vice versa when it has decreased.

Source: TradingView
While there has also been a strengthening in the correlation with other parts of the U.S. curve and yield differentials between the U.S. and Japan over the same period, it’s really been the immediate front of the curve that's dominated. Risk appetite, as proxied by S&P 500 and VIX futures not shown on the chart, has also shown a relatively loose relationship with USD/JPY, hinting the yen’s role as a funding currency for carry trades may be starting to pick up again.
Should those trends extend, it puts emphasis on news and events that can shift market pricing for U.S. rate cuts and influence risk appetite in the week ahead.

Waiting for a Catalyst
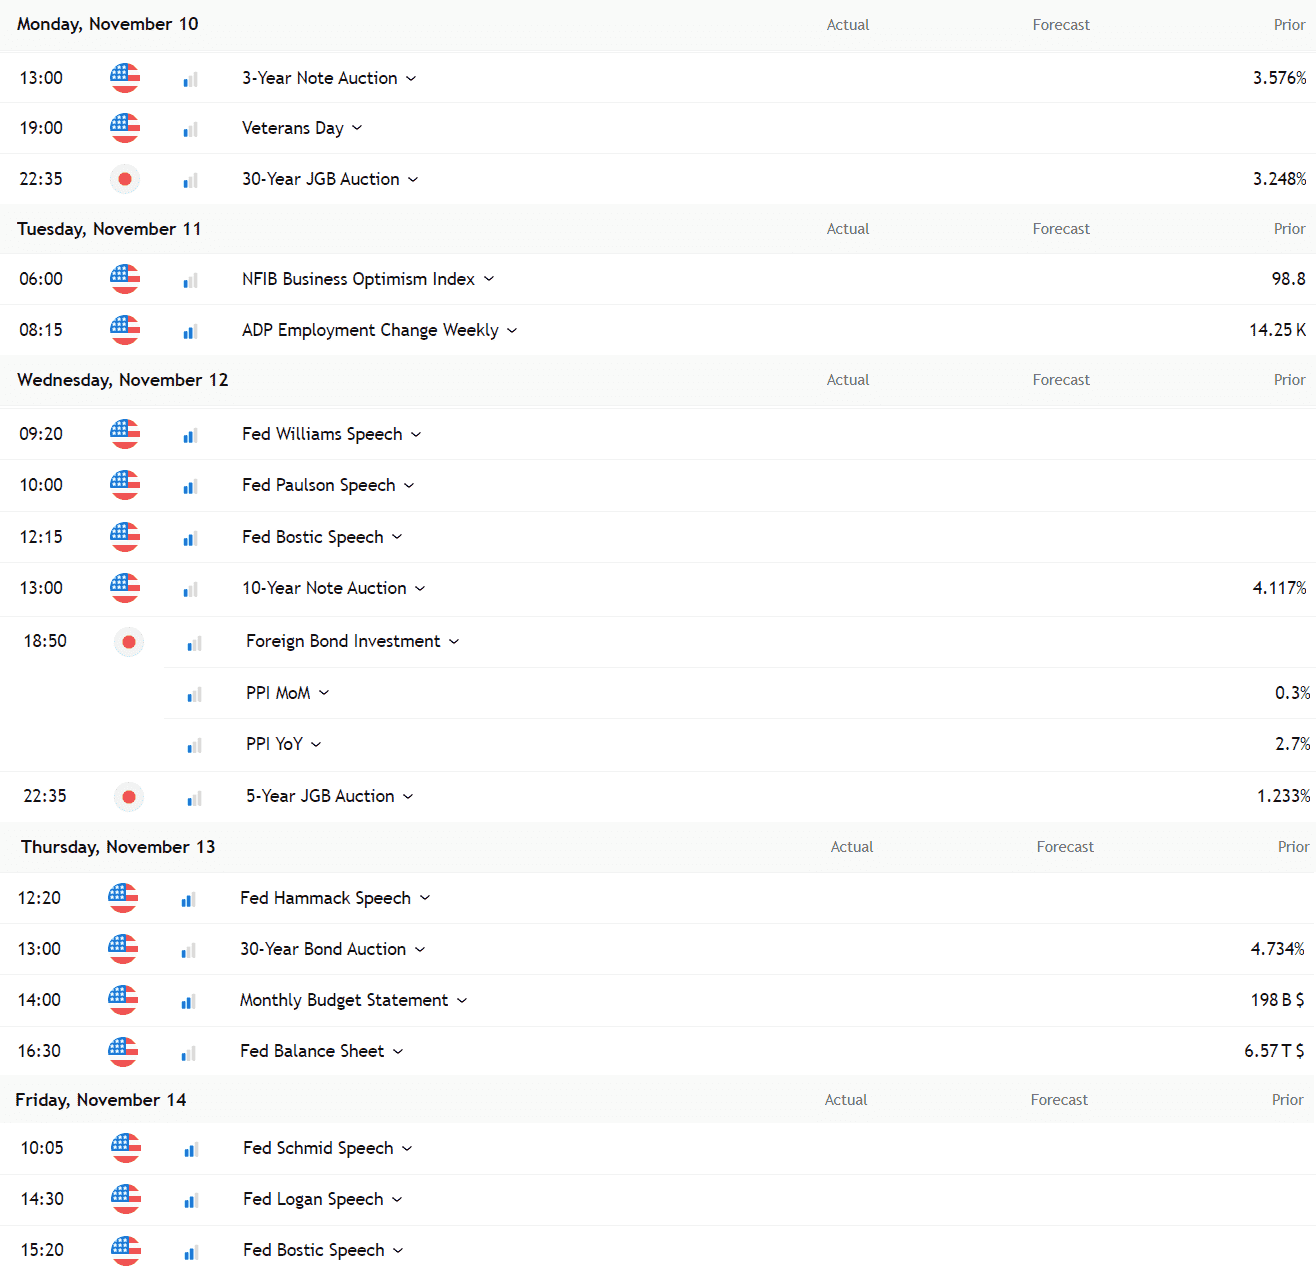
Looking at the calendar, speeches from Fed officials loom as the most likely source of volatility given a dearth of top-tier data thanks to the government shutdown. However, without information to judge whether the policy outlook is appropriate, you have to question whether they’ll deliver sizeable and sustained market moves, especially given the recent trend where there’s been a split among the FOMC into two separate camps: those worried about downside risks to the labour market and those who are concerned about the potential for inflation to reaccelerate. With no top-tier data to change individual views, the stalemate appears likely to persist, limiting volatility.
Source: TradingView (U.S. ET)
As for events that may generate movement, the weekly ADP employment change report will attract plenty of attention given the focus on the U.S. labour market, even though the signal it provides remains highly questionable. Fresh auctions of U.S. 3, 10 and 30-year Treasuries on Monday, Wednesday and Thursday respectively should also be watched given USD/JPY has been increasingly correlated with U.S. yields lately. Tuesday will bring Veterans Day, which will see trading in U.S. Treasuries halted, potentially limiting activity in other markets as a result.
On the Japanese side of the ledger, Tuesday’s 30-year government bond auction looms as a key event, especially with Japanese Prime Minister Sanae Takaichi signalling a desire to run looser fiscal policy than her predecessor. If demand is weak, it may derail plans to adopt more reflationary policies, likely leading to softness in longer-dated bonds and the yen. PPI data out Thursday is another event of note, providing a guide on upstream price pressures that may eventually flow through to consumers, influencing the Bank of Japan outlook. It’s not on the calendar, but BOJ board member Junko Nakagawa is scheduled to deliver a speech at Monday lunchtime in Japan. She hasn’t made public remarks since August, so it may contain surprises.
USD/JPY Heavy but still Rangebound

Source: TradingView
USD/JPY was rangebound last week, likely reflecting a lack of fresh catalysts to drive direction from either the United States or Japan. Friday’s break of minor uptrend support failed to stick, with buyers emerging on a dip beneath 153.00, eventually driving the price back above the trendline. Despite the rebound, the continued inability to break resistance at 154.50, combined with signals from momentum indicators like RSI (14) and MACD, which have rolled over and point to weakening upside pressure, leaves the pair looking heavy with directional risks marginally skewed lower.
Beneath 153.00, 151.50 and 151.00 are support levels to watch, especially the latter. Above 154.50, a break would put resistance at 156.50 on the menu for bulls. Any levels either side of those are unlikely to be reached in the absence of some form of unexpected positive or negative event.