




04 08 EU PRE OPEN
European stocks report | BP | Bayer | Novartis | FLSmidth & Co ...
Share this:

INDICES
Yesterday, European stocks rebounded. The Stoxx Europe 600 Index jumped 2.05%, Germany's DAX 30 surged 2.71%, France's CAC 40 rose 1.93%, and the U.K.'s FTSE 100 climbed 2.29%.
EUROPE ADVANCE/DECLINE
86% of STOXX 600 constituents traded higher yesterday.
43% of the shares trade above their 20D MA vs 28% Friday (below the 20D moving average).
48% of the shares trade above their 200D MA vs 44% Friday (below the 20D moving average).
The Euro Stoxx 50 Volatility index eased 0.91pt to 25.76, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Financial Services, Industrial
3mths relative low: Telecom.
Europe Best 3 sectors
automobiles & parts, media, construction & materials
Europe worst 3 sectors
real estate, food & beverage, telecommunications
INTEREST RATE
The 10yr Bund yield rose 2bps to -0.52% (below its 20D MA). The 2yr-10yr yield spread rose 1bp to -17bps (above its 20D MA).
ECONOMIC DATA
FR 07:45: Jun Budget Balance, exp.: E-117.9B
EC 10:00: Jun PPI YoY, exp.: -5%
EC 10:00: Jun PPI MoM, exp.: -0.6%
MORNING TRADING
In Asian trading hours, major currencies rebounded against the U.S. dollar. EUR/USD climbed higher nearing 1.1770, GBP/USD was at elevated levels around 1.3075. USD/JPY managed to stay above 106.00. AUD/USD advanced to levels above 0.7130. As expected, Australia's central bank kept its key interest rate unchanged at 0.25%. Official data showed that Australia's June Retail Sales grew 2.7% on month (+2.4% expected) and Exports increased 3% (+4% expected).
Spot gold was little changed at $1,973 an ounce.
#UK - IRELAND#
BP, oil major, announced 2Q results: "Underlying replacement cost loss for the quarter was 6.7 billion dollars, compared with a profit of 2.8 billion dollars for the same period a year earlier. The result was driven primarily by non-cash Upstream exploration write-offs - 6.5 billion dollars after tax (...) combined with the impact of lower oil and gas prices and very weak refining margins, reduced oil and gas production and much lower demand for fuels and lubricants. Oil trading delivered an exceptionally strong result. (...) A dividend of 5.25 cents per share was announced for the quarter, compared to 10.5 cents per share for the previous quarter."
#GERMANY#
Bayer, a German healthcare giant, said it swung to a 2Q net loss of 9.55 billion euros from a net income of 404 million euros in the prior-year period, citing net special charges of 12.51 billion euros. 2Q EBITDA before special items increased 5.6% on year to 2.88 billion euros on sales of 10.05 billion euros, up 2.5% on a currency- and portfolio-adjusted basis. The Company lowered its forecast on full-year EBITDA before special items to 12.1 billion euros from 12.3-12.6 billion euros previously and that on Core earnings per share to 6.70-6.90 euros from 7.00-7.20 euros.
Hugo Boss, a German premium-apparel company, announced that it swung to a 2Q net loss of 186 million euros from a net income of 52 million euros in the prior-year period on sales of 275 million euros, down 59% on year. The Company said: "Retail sales trends during the second quarter have shown a sequential improvement month by month. This positive trend has also continued so far in Q3, as HUGO BOSS has recorded further improvements in its global retail operations during the month of July."
Fraport, the operator of Frankfurt airport, posted a 1H net loss of 231 million euros, compared with a net income of 165 million euros in the prior-year period on revenue of 911 million euros, down 49% on year. The Company pointed out: "Frankfurt Airport's passenger traffic plummeted by 94.4% year-on-year in the April-to-June 2020 period, while falling by a total of 63.8% during the entire first half."
Infineon Technologies, a semiconductors maker, reported that it swung to a 3Q net loss of 128 million euros from a net income of 224 million euros in the prior-year period.
#BENELUX#
DSM, a Dutch nutrition and health company, reported that 1H net income fell to 270 million euros from 401 million euros in the prior-year period. 1H Adjusted EBITDA eased 4.3% on year to 825 million euros on sales of 4.53 billion euros, slightly lower than 4.57 billion euros a year earlier.
#SWITZERLAND#
Novartis, a Swiss maker of pharmaceutical products, reported positive results from a Phase 2 trial of Kymriah (tisagenlecleucel) in patients with relapsed or refractory follicular lymphoma.
#DENMARK#
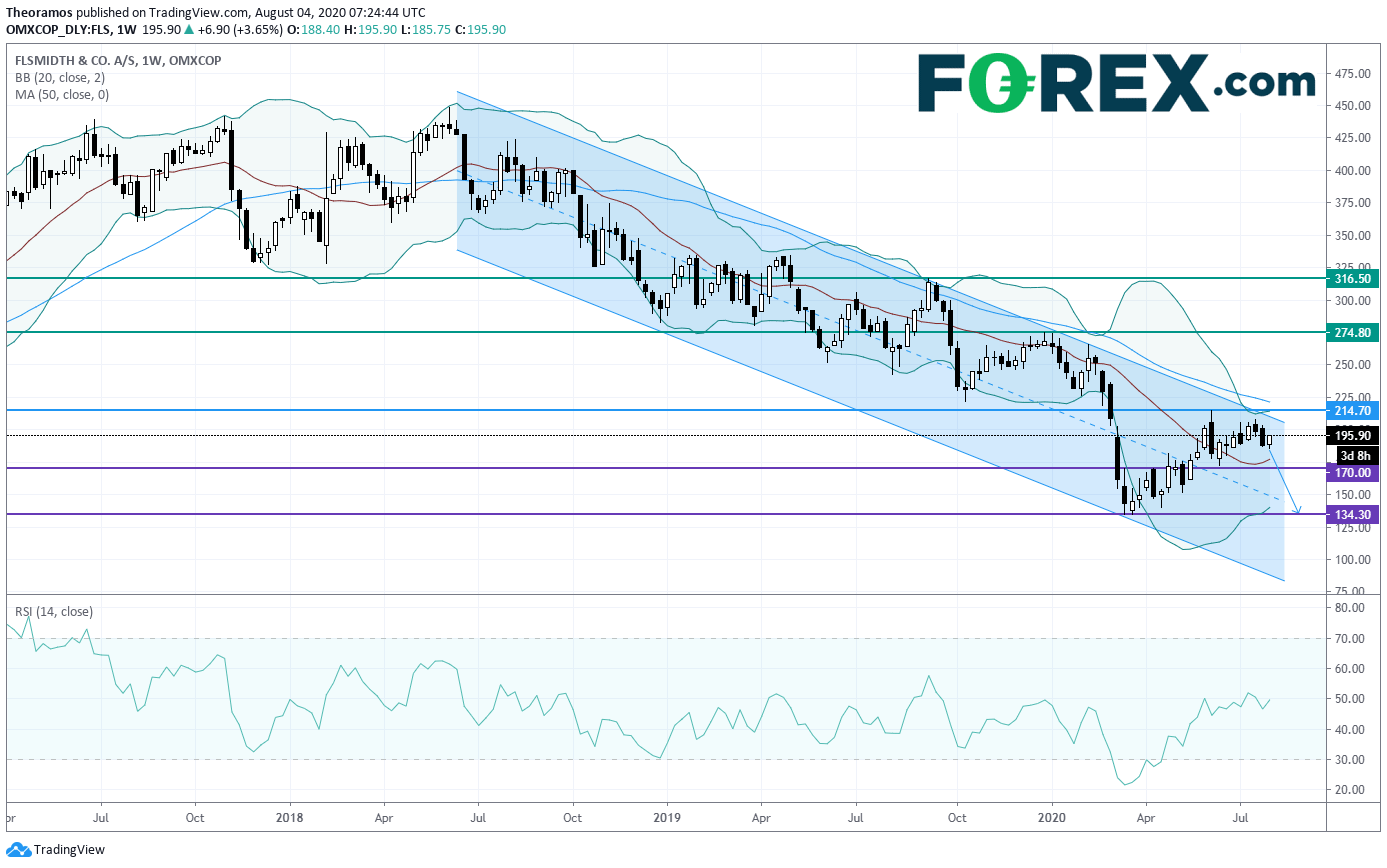
FLSmidth & Co, a machinery firm, reported that 2Q EBITA decreased 73% on year to 131 million Danish Krone on revenue of 3.85 billion Danish Krone, down 30%. The Company said: "The clear majority of the revenue decline was attributable to COVID-19, but the change was also a result of a lower backlog entering the year."
From a weekly point of view, the stock remains within a bearish channel since June 2018. Below 214.7 krone, targets are set at 170 Krone and 134.30 krone in extension.
Source: GAIN Capital, TradingView
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


USD/JPY Weekly Outlook: Payrolls loom as US rates remain the dominant driver
Strong US growth and hawkish Fed pricing continue to support USD/JPY, while intervention risk appears to be kicking in at lower levels

EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.