



07 09 EU PRE OPEN
European stocks report | Associated British Foods | Dechra Pharmaceuticals | Volkswagen | Ageas...
Share this:

INDICES
Friday, European stocks were broadly lower. The Stoxx Europe 600 Index slid 1.3%, Germany's DAX 30 sank 1.7%, France's CAC 40 and U.K.'s FTSE 100 were down 0.9%.
EUROPE ADVANCE/DECLINE
70% of STOXX 600 constituents traded lower or unchanged Friday.
29% of the shares trade above their 20D MA vs 41% Thursday (below the 20D moving average).
50% of the shares trade above their 200D MA vs 52% Thursday (below the 20D moving average).
The Euro Stoxx 50 Volatility index added 2.7pts to 31.71, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Chemicals, Autos
3mths relative low: none
Europe Best 3 sectors
banks, basic resources, automobiles & parts
Europe worst 3 sectors
real estate, technology, utilities
INTEREST RATE
The 10yr Bund yield fell 2bps to -0.49% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -23bps (below its 20D MA).
ECONOMIC DATA
GE 07:00: Jul Industrial Production MoM, exp.: 8.9%
UK 08:30: Aug Halifax House Price Idx YoY, exp.: 3.8%
UK 08:30: Aug Halifax House Price Idx MoM, exp.: 1.6%
FR 14:00: 12-Mth BTF auction, exp.: -0.57%
FR 14:00: 6-Mth BTF auction, exp.: -0.58%
FR 14:00: 3-Mth BTF auction, exp.: -0.57%
MORNING TRADING
In Asian trading hours, EUR/USD was little changed at 1.1835 while GBP/USD slipped to 1.3239. USD/JPY was steady at 106.28.
Spot gold climbed to $1,938 an ounce.
#UK - IRELAND#
Associated British Foods, a food processing and retailing company, posted a 4Q trading update: "Trading in the fourth quarter in both our food businesses and Primark exceeded our expectations. (...) All Primark stores reopened in May, June and July. Since reopening we have traded strongly, attracting customers with our value-for-money offering and a welcoming and safe store environment. Cumulative sales since reopening to the year-end are expected to be £2bn and our adjusted operating profit on an IFRS16 basis for the year, before exceptional items, is now expected to be at least at the top end of the previously advised £300-350m range."
Dechra Pharmaceuticals, a veterinary pharmaceuticals company, released full-year results: "Dechra delivered consolidated revenue of £515.1 million, representing an increase of 6.8% on the prior year. (...) Consolidated underlying operating profit of £128.3 million represents a 0.4% increase on the prior year. (...) Underlying diluted EPS grew by 1.7% to 92.19 pence. (...) The Board is proposing a final dividend of 24.00 pence per share (2019: 22.10 pence per share). Added to the interim dividend of 10.29 pence per share (2019: 9.50 pence per share), this brings the total dividend for the financial year ended 30 June 2020 to 34.29 pence per share (2019: 31.60 pence per share), representing 8.5% growth over the previous year."
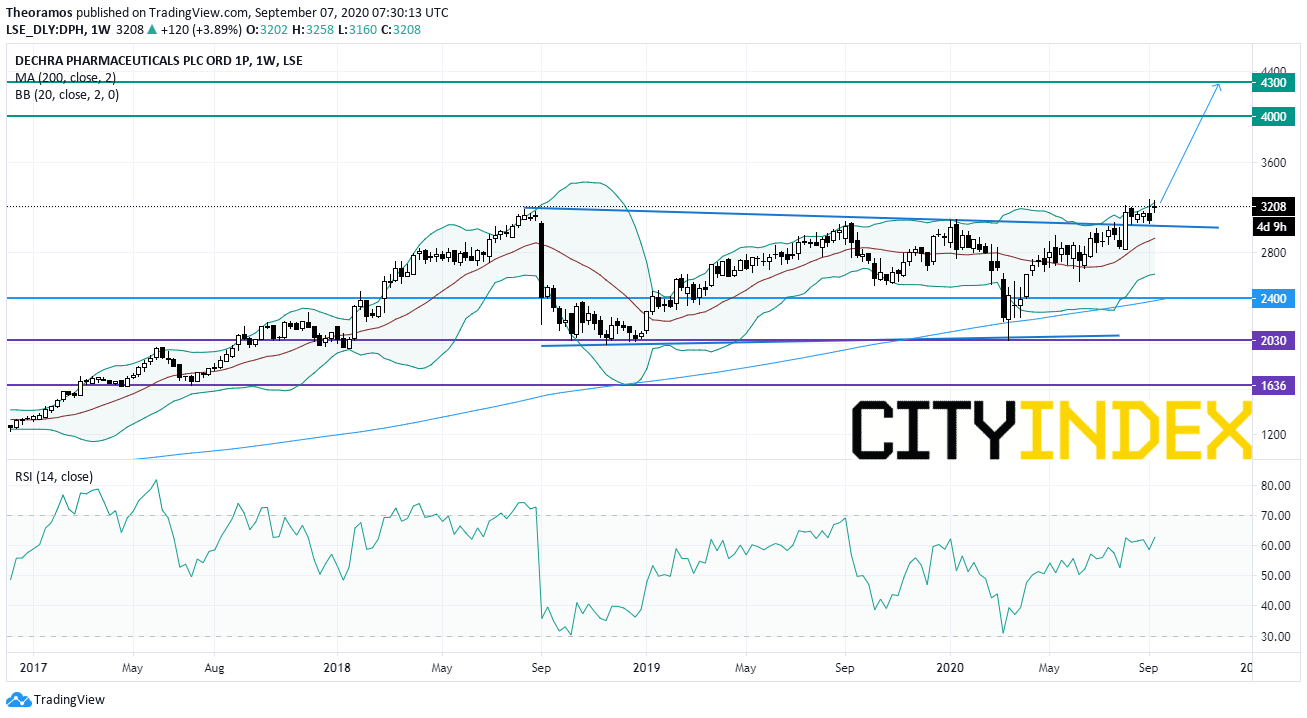
From a weekly point of view, the share has broken above a symmetrical triangle following a consolidation area of 2 years. Furthermore, the 200WMA plays a support role. Above the 200WMA at 2400p look for 4000p and 4300p in extension.
Source: GAIN Capital, TradingView
Informa, a business intelligence group, was downgraded to "neutral" from "buy" at Goldman Sachs.
#GERMANY#
Volkswagen's, an automobile group, Traton is planning to make a fresh bid for U.S. heavy-truck company Navistar International, which it previously offered 2.9 billion dollars, reported Bloomberg citing people familiar with the matter.
Continental, automotive parts manufacturer, was upgraded to "neutral" from "underweight" at JPMorgan.
Hannover Re, a reinsurance group, was upgraded to "overweight" from "underweight" at JPMorgan.
Hapag-Lloyd, a shipping and container transportation company, was upgraded to "hold" from "reduce" at HSBC.
#FRANCE#
Suez's, an utility company, CEO Bertrand Camus in an interview with French newspaper Le Figaro that "the proposed deal by Veolia is an aberration and destructive for France". He added that the company's share price has been hurt by the coronavirus pandemic, the offer undervalues Suez's assets and is opportunistic.
Sanofi, a pharmaceutical group, will launch an IPO for its drug-ingredients division in the coming months, according to the company's chief in France Olivier Bogillot cited by France Inter radio.
Scor, a reinsurance company, was downgraded to "neutral" from "overweight" at JPMorgan.
#SPAIN#
Mapfre, a Spanish insurance company, was downgraded to "underweight" from "neutral" at JPMorgan.
#BENELUX#
Ageas, a Belgian insurance company, confirmed that it was approached recently by BE Group with "an indicative and highly conditional offer" on the company. The company added that "the Ageas Board of Directors assessed the indicative proposal but considered it not realistic and has decided not to engage".
#SWITZERLAND#
Swiss Life, an insurance group, was upgraded to "neutral" from "underweight" at JPMorgan.
Friday, European stocks were broadly lower. The Stoxx Europe 600 Index slid 1.3%, Germany's DAX 30 sank 1.7%, France's CAC 40 and U.K.'s FTSE 100 were down 0.9%.
EUROPE ADVANCE/DECLINE
70% of STOXX 600 constituents traded lower or unchanged Friday.
29% of the shares trade above their 20D MA vs 41% Thursday (below the 20D moving average).
50% of the shares trade above their 200D MA vs 52% Thursday (below the 20D moving average).
The Euro Stoxx 50 Volatility index added 2.7pts to 31.71, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Chemicals, Autos
3mths relative low: none
Europe Best 3 sectors
banks, basic resources, automobiles & parts
Europe worst 3 sectors
real estate, technology, utilities
INTEREST RATE
The 10yr Bund yield fell 2bps to -0.49% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -23bps (below its 20D MA).
ECONOMIC DATA
GE 07:00: Jul Industrial Production MoM, exp.: 8.9%
UK 08:30: Aug Halifax House Price Idx YoY, exp.: 3.8%
UK 08:30: Aug Halifax House Price Idx MoM, exp.: 1.6%
FR 14:00: 12-Mth BTF auction, exp.: -0.57%
FR 14:00: 6-Mth BTF auction, exp.: -0.58%
FR 14:00: 3-Mth BTF auction, exp.: -0.57%
MORNING TRADING
In Asian trading hours, EUR/USD was little changed at 1.1835 while GBP/USD slipped to 1.3239. USD/JPY was steady at 106.28.
Spot gold climbed to $1,938 an ounce.
#UK - IRELAND#
Associated British Foods, a food processing and retailing company, posted a 4Q trading update: "Trading in the fourth quarter in both our food businesses and Primark exceeded our expectations. (...) All Primark stores reopened in May, June and July. Since reopening we have traded strongly, attracting customers with our value-for-money offering and a welcoming and safe store environment. Cumulative sales since reopening to the year-end are expected to be £2bn and our adjusted operating profit on an IFRS16 basis for the year, before exceptional items, is now expected to be at least at the top end of the previously advised £300-350m range."
Dechra Pharmaceuticals, a veterinary pharmaceuticals company, released full-year results: "Dechra delivered consolidated revenue of £515.1 million, representing an increase of 6.8% on the prior year. (...) Consolidated underlying operating profit of £128.3 million represents a 0.4% increase on the prior year. (...) Underlying diluted EPS grew by 1.7% to 92.19 pence. (...) The Board is proposing a final dividend of 24.00 pence per share (2019: 22.10 pence per share). Added to the interim dividend of 10.29 pence per share (2019: 9.50 pence per share), this brings the total dividend for the financial year ended 30 June 2020 to 34.29 pence per share (2019: 31.60 pence per share), representing 8.5% growth over the previous year."
From a weekly point of view, the share has broken above a symmetrical triangle following a consolidation area of 2 years. Furthermore, the 200WMA plays a support role. Above the 200WMA at 2400p look for 4000p and 4300p in extension.
Source: GAIN Capital, TradingView
Informa, a business intelligence group, was downgraded to "neutral" from "buy" at Goldman Sachs.
#GERMANY#
Volkswagen's, an automobile group, Traton is planning to make a fresh bid for U.S. heavy-truck company Navistar International, which it previously offered 2.9 billion dollars, reported Bloomberg citing people familiar with the matter.
Continental, automotive parts manufacturer, was upgraded to "neutral" from "underweight" at JPMorgan.
Hannover Re, a reinsurance group, was upgraded to "overweight" from "underweight" at JPMorgan.
Hapag-Lloyd, a shipping and container transportation company, was upgraded to "hold" from "reduce" at HSBC.
#FRANCE#
Suez's, an utility company, CEO Bertrand Camus in an interview with French newspaper Le Figaro that "the proposed deal by Veolia is an aberration and destructive for France". He added that the company's share price has been hurt by the coronavirus pandemic, the offer undervalues Suez's assets and is opportunistic.
Sanofi, a pharmaceutical group, will launch an IPO for its drug-ingredients division in the coming months, according to the company's chief in France Olivier Bogillot cited by France Inter radio.
Scor, a reinsurance company, was downgraded to "neutral" from "overweight" at JPMorgan.
#SPAIN#
Mapfre, a Spanish insurance company, was downgraded to "underweight" from "neutral" at JPMorgan.
#BENELUX#
Ageas, a Belgian insurance company, confirmed that it was approached recently by BE Group with "an indicative and highly conditional offer" on the company. The company added that "the Ageas Board of Directors assessed the indicative proposal but considered it not realistic and has decided not to engage".
#SWITZERLAND#
Swiss Life, an insurance group, was upgraded to "neutral" from "underweight" at JPMorgan.
INDICES
Friday, European stocks were broadly lower. The Stoxx Europe 600 Index slid 1.3%, Germany's DAX 30 sank 1.7%, France's CAC 40 and U.K.'s FTSE 100 were down 0.9%.
EUROPE ADVANCE/DECLINE
70% of STOXX 600 constituents traded lower or unchanged Friday.
29% of the shares trade above their 20D MA vs 41% Thursday (below the 20D moving average).
50% of the shares trade above their 200D MA vs 52% Thursday (below the 20D moving average).
The Euro Stoxx 50 Volatility index added 2.7pts to 31.71, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Chemicals, Autos
3mths relative low: none
Europe Best 3 sectors
banks, basic resources, automobiles & parts
Europe worst 3 sectors
real estate, technology, utilities
INTEREST RATE
The 10yr Bund yield fell 2bps to -0.49% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -23bps (below its 20D MA).
ECONOMIC DATA
GE 07:00: Jul Industrial Production MoM, exp.: 8.9%
UK 08:30: Aug Halifax House Price Idx YoY, exp.: 3.8%
UK 08:30: Aug Halifax House Price Idx MoM, exp.: 1.6%
FR 14:00: 12-Mth BTF auction, exp.: -0.57%
FR 14:00: 6-Mth BTF auction, exp.: -0.58%
FR 14:00: 3-Mth BTF auction, exp.: -0.57%
MORNING TRADING
In Asian trading hours, EUR/USD was little changed at 1.1835 while GBP/USD slipped to 1.3239. USD/JPY was steady at 106.28.
Spot gold climbed to $1,938 an ounce.
#UK - IRELAND#
Associated British Foods, a food processing and retailing company, posted a 4Q trading update: "Trading in the fourth quarter in both our food businesses and Primark exceeded our expectations. (...) All Primark stores reopened in May, June and July. Since reopening we have traded strongly, attracting customers with our value-for-money offering and a welcoming and safe store environment. Cumulative sales since reopening to the year-end are expected to be £2bn and our adjusted operating profit on an IFRS16 basis for the year, before exceptional items, is now expected to be at least at the top end of the previously advised £300-350m range."
Dechra Pharmaceuticals, a veterinary pharmaceuticals company, released full-year results: "Dechra delivered consolidated revenue of £515.1 million, representing an increase of 6.8% on the prior year. (...) Consolidated underlying operating profit of £128.3 million represents a 0.4% increase on the prior year. (...) Underlying diluted EPS grew by 1.7% to 92.19 pence. (...) The Board is proposing a final dividend of 24.00 pence per share (2019: 22.10 pence per share). Added to the interim dividend of 10.29 pence per share (2019: 9.50 pence per share), this brings the total dividend for the financial year ended 30 June 2020 to 34.29 pence per share (2019: 31.60 pence per share), representing 8.5% growth over the previous year."
From a weekly point of view, the share has broken above a symmetrical triangle following a consolidation area of 2 years. Furthermore, the 200WMA plays a support role. Above the 200WMA at 2400p look for 4000p and 4300p in extension.

Source: GAIN Capital, TradingView
Informa, a business intelligence group, was downgraded to "neutral" from "buy" at Goldman Sachs.
#GERMANY#
Volkswagen's, an automobile group, Traton is planning to make a fresh bid for U.S. heavy-truck company Navistar International, which it previously offered 2.9 billion dollars, reported Bloomberg citing people familiar with the matter.
Continental, automotive parts manufacturer, was upgraded to "neutral" from "underweight" at JPMorgan.
Hannover Re, a reinsurance group, was upgraded to "overweight" from "underweight" at JPMorgan.
Hapag-Lloyd, a shipping and container transportation company, was upgraded to "hold" from "reduce" at HSBC.
#FRANCE#
Suez's, an utility company, CEO Bertrand Camus in an interview with French newspaper Le Figaro that "the proposed deal by Veolia is an aberration and destructive for France". He added that the company's share price has been hurt by the coronavirus pandemic, the offer undervalues Suez's assets and is opportunistic.
Sanofi, a pharmaceutical group, will launch an IPO for its drug-ingredients division in the coming months, according to the company's chief in France Olivier Bogillot cited by France Inter radio.
Scor, a reinsurance company, was downgraded to "neutral" from "overweight" at JPMorgan.
#SPAIN#
Mapfre, a Spanish insurance company, was downgraded to "underweight" from "neutral" at JPMorgan.
#BENELUX#
Ageas, a Belgian insurance company, confirmed that it was approached recently by BE Group with "an indicative and highly conditional offer" on the company. The company added that "the Ageas Board of Directors assessed the indicative proposal but considered it not realistic and has decided not to engage".
#SWITZERLAND#
Swiss Life, an insurance group, was upgraded to "neutral" from "underweight" at JPMorgan.
Friday, European stocks were broadly lower. The Stoxx Europe 600 Index slid 1.3%, Germany's DAX 30 sank 1.7%, France's CAC 40 and U.K.'s FTSE 100 were down 0.9%.
EUROPE ADVANCE/DECLINE
70% of STOXX 600 constituents traded lower or unchanged Friday.
29% of the shares trade above their 20D MA vs 41% Thursday (below the 20D moving average).
50% of the shares trade above their 200D MA vs 52% Thursday (below the 20D moving average).
The Euro Stoxx 50 Volatility index added 2.7pts to 31.71, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Chemicals, Autos
3mths relative low: none
Europe Best 3 sectors
banks, basic resources, automobiles & parts
Europe worst 3 sectors
real estate, technology, utilities
INTEREST RATE
The 10yr Bund yield fell 2bps to -0.49% (below its 20D MA). The 2yr-10yr yield spread fell 1bp to -23bps (below its 20D MA).
ECONOMIC DATA
GE 07:00: Jul Industrial Production MoM, exp.: 8.9%
UK 08:30: Aug Halifax House Price Idx YoY, exp.: 3.8%
UK 08:30: Aug Halifax House Price Idx MoM, exp.: 1.6%
FR 14:00: 12-Mth BTF auction, exp.: -0.57%
FR 14:00: 6-Mth BTF auction, exp.: -0.58%
FR 14:00: 3-Mth BTF auction, exp.: -0.57%
MORNING TRADING
In Asian trading hours, EUR/USD was little changed at 1.1835 while GBP/USD slipped to 1.3239. USD/JPY was steady at 106.28.
Spot gold climbed to $1,938 an ounce.
#UK - IRELAND#
Associated British Foods, a food processing and retailing company, posted a 4Q trading update: "Trading in the fourth quarter in both our food businesses and Primark exceeded our expectations. (...) All Primark stores reopened in May, June and July. Since reopening we have traded strongly, attracting customers with our value-for-money offering and a welcoming and safe store environment. Cumulative sales since reopening to the year-end are expected to be £2bn and our adjusted operating profit on an IFRS16 basis for the year, before exceptional items, is now expected to be at least at the top end of the previously advised £300-350m range."
Dechra Pharmaceuticals, a veterinary pharmaceuticals company, released full-year results: "Dechra delivered consolidated revenue of £515.1 million, representing an increase of 6.8% on the prior year. (...) Consolidated underlying operating profit of £128.3 million represents a 0.4% increase on the prior year. (...) Underlying diluted EPS grew by 1.7% to 92.19 pence. (...) The Board is proposing a final dividend of 24.00 pence per share (2019: 22.10 pence per share). Added to the interim dividend of 10.29 pence per share (2019: 9.50 pence per share), this brings the total dividend for the financial year ended 30 June 2020 to 34.29 pence per share (2019: 31.60 pence per share), representing 8.5% growth over the previous year."
From a weekly point of view, the share has broken above a symmetrical triangle following a consolidation area of 2 years. Furthermore, the 200WMA plays a support role. Above the 200WMA at 2400p look for 4000p and 4300p in extension.
Source: GAIN Capital, TradingView
Informa, a business intelligence group, was downgraded to "neutral" from "buy" at Goldman Sachs.
#GERMANY#
Volkswagen's, an automobile group, Traton is planning to make a fresh bid for U.S. heavy-truck company Navistar International, which it previously offered 2.9 billion dollars, reported Bloomberg citing people familiar with the matter.
Continental, automotive parts manufacturer, was upgraded to "neutral" from "underweight" at JPMorgan.
Hannover Re, a reinsurance group, was upgraded to "overweight" from "underweight" at JPMorgan.
Hapag-Lloyd, a shipping and container transportation company, was upgraded to "hold" from "reduce" at HSBC.
#FRANCE#
Suez's, an utility company, CEO Bertrand Camus in an interview with French newspaper Le Figaro that "the proposed deal by Veolia is an aberration and destructive for France". He added that the company's share price has been hurt by the coronavirus pandemic, the offer undervalues Suez's assets and is opportunistic.
Sanofi, a pharmaceutical group, will launch an IPO for its drug-ingredients division in the coming months, according to the company's chief in France Olivier Bogillot cited by France Inter radio.
Scor, a reinsurance company, was downgraded to "neutral" from "overweight" at JPMorgan.
#SPAIN#
Mapfre, a Spanish insurance company, was downgraded to "underweight" from "neutral" at JPMorgan.
#BENELUX#
Ageas, a Belgian insurance company, confirmed that it was approached recently by BE Group with "an indicative and highly conditional offer" on the company. The company added that "the Ageas Board of Directors assessed the indicative proposal but considered it not realistic and has decided not to engage".
#SWITZERLAND#
Swiss Life, an insurance group, was upgraded to "neutral" from "underweight" at JPMorgan.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


USD/JPY Weekly Outlook: Payrolls loom as US rates remain the dominant driver
Strong US growth and hawkish Fed pricing continue to support USD/JPY, while intervention risk appears to be kicking in at lower levels
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.