



11 11 US PRE OPEN
The S&P 500 Futures are on the upside after they closed mixed yesterday
Share this:
The S&P 500 Futures are on the upside after they closed mixed yesterday as the Dow Jones Industrial Average advanced a further 0.90% while the Nasdaq 100 shed another 1.74%.
No major economic data are expected today.
European indices remain on the upside.
Asian indices ended on a positive note except the Chinese CSI. The Reserve Bank of New Zealand kept its benchmark rate unchanged at 0.25% as expected. RBNZ said additional stimulus would be provided through a Funding for Lending Programme (FLP), commencing in December, and "monetary policy will need to remain stimulatory for a long time".
WTI Crude Oil remains strongly bullish. The American Petroleum Institute (API) reported that U.S. crude-oil inventories dropped 5.1M barrels in the week ending November 6. The U.S. Energy Information Administration (EIA) projected that 2021 WTI Crude Oil forecast price would be $44.24/bbl, down from $44.72 in the previous estimation. The global oil demand for 2021 lowered to 98.80M b/d from 99.09M b/d, while global supply is also down to 94.58M b/d from 98.83M b/d. Later today, EIA will release official crude oil inventories data for week ending November 6.
US indices closed mixed on Tuesday with the Dow Jones (+0.90%) closing up, while the Nasdaq (-1.37%) and S&P 500 (-0.14%) closed down. Automobiles & Components (+3.48%), Energy (+2.52%) and Food, Beverage & Tobacco (+2.4%) sectors were the best performers on the day, while Semiconductors & Semiconductor Equipment (-3.43%), Software & Services (-2.36%) and Retailing (-1.62%) sectors were the worst performers.
The dollar index rose 0.26pt to 93.011.
U.S. Equity Snapshot
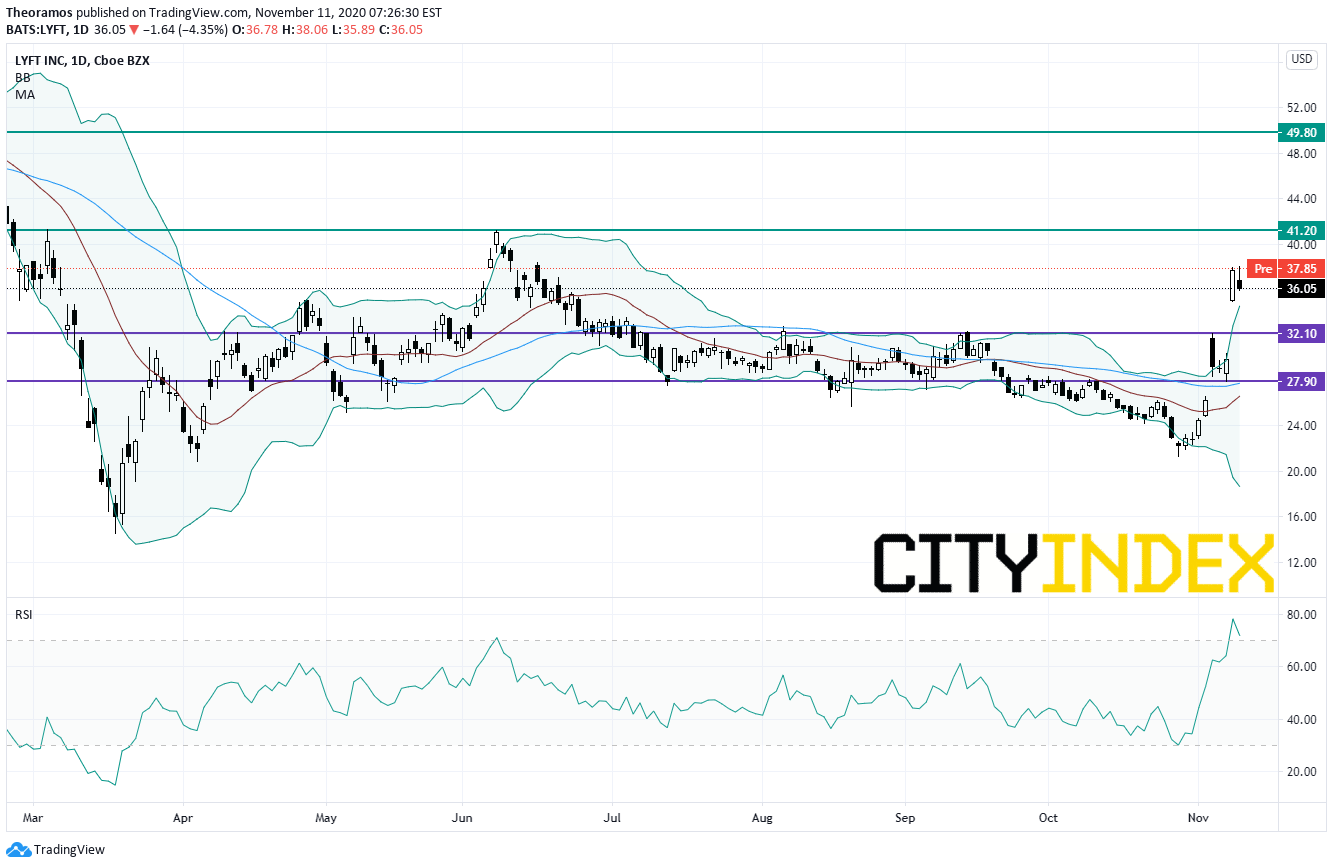
Lyft (LYFT), the ridesharing company, jumped after hours after reporting third quarter sales of 499.7 million dollars, above forecasts, down from 955.6 million dollars last year. LPS was 1.46 dollar, worse than expected, vs a LPS of 0.41 dollar a year ago. The company expects Ebitda to be positive by the fourth quarter of 2021.
Source: TradingView, GAIN Capital
Boeing (BA) won a 9.8 billion dollars contract from the Pentagon regarding F-15 support for Saudi Arabia.
CVS Health's (CVS), the pharmacy and healthcare company, price target was raised to 76 dollars from 72 dollars at Piper Sandler.
No major economic data are expected today.
European indices remain on the upside.
Asian indices ended on a positive note except the Chinese CSI. The Reserve Bank of New Zealand kept its benchmark rate unchanged at 0.25% as expected. RBNZ said additional stimulus would be provided through a Funding for Lending Programme (FLP), commencing in December, and "monetary policy will need to remain stimulatory for a long time".
WTI Crude Oil remains strongly bullish. The American Petroleum Institute (API) reported that U.S. crude-oil inventories dropped 5.1M barrels in the week ending November 6. The U.S. Energy Information Administration (EIA) projected that 2021 WTI Crude Oil forecast price would be $44.24/bbl, down from $44.72 in the previous estimation. The global oil demand for 2021 lowered to 98.80M b/d from 99.09M b/d, while global supply is also down to 94.58M b/d from 98.83M b/d. Later today, EIA will release official crude oil inventories data for week ending November 6.
US indices closed mixed on Tuesday with the Dow Jones (+0.90%) closing up, while the Nasdaq (-1.37%) and S&P 500 (-0.14%) closed down. Automobiles & Components (+3.48%), Energy (+2.52%) and Food, Beverage & Tobacco (+2.4%) sectors were the best performers on the day, while Semiconductors & Semiconductor Equipment (-3.43%), Software & Services (-2.36%) and Retailing (-1.62%) sectors were the worst performers.
Approximately 82% of stocks in the S&P 500 Index were trading above their 200-day moving average and 78% were trading above their 20-day moving average. The VIX Index dropped 1.23pt (-4.78%) to 24.52 and WTI Crude Oil gained $1.09 (+2.71%) to $41.38 at the close.
On the US economic data front, the National Federation of Independent Business's Small Business Optimism Index remained unchanged at 104.0 on month in October (104.1 expected), in line with September. Finally, U.S. Job Openings rose to 6.436 million on month in September (6.500 million expected), compared to a revised 6.352 million in August.Gold loses ground as the U.S dollar remains firm on return for risk appetite.
Gold fell 1.48 dollar (-0.08%) to 1875.85 dollars.The dollar index rose 0.26pt to 93.011.
U.S. Equity Snapshot
Lyft (LYFT), the ridesharing company, jumped after hours after reporting third quarter sales of 499.7 million dollars, above forecasts, down from 955.6 million dollars last year. LPS was 1.46 dollar, worse than expected, vs a LPS of 0.41 dollar a year ago. The company expects Ebitda to be positive by the fourth quarter of 2021.
Source: TradingView, GAIN Capital
Boeing (BA) won a 9.8 billion dollars contract from the Pentagon regarding F-15 support for Saudi Arabia.
CVS Health's (CVS), the pharmacy and healthcare company, price target was raised to 76 dollars from 72 dollars at Piper Sandler.
The S&P 500 Futures are on the upside after they closed mixed yesterday as the Dow Jones Industrial Average advanced a further 0.90% while the Nasdaq 100 shed another 1.74%.
No major economic data are expected today.
European indices remain on the upside.
Asian indices ended on a positive note except the Chinese CSI. The Reserve Bank of New Zealand kept its benchmark rate unchanged at 0.25% as expected. RBNZ said additional stimulus would be provided through a Funding for Lending Programme (FLP), commencing in December, and "monetary policy will need to remain stimulatory for a long time".
WTI Crude Oil remains strongly bullish. The American Petroleum Institute (API) reported that U.S. crude-oil inventories dropped 5.1M barrels in the week ending November 6. The U.S. Energy Information Administration (EIA) projected that 2021 WTI Crude Oil forecast price would be $44.24/bbl, down from $44.72 in the previous estimation. The global oil demand for 2021 lowered to 98.80M b/d from 99.09M b/d, while global supply is also down to 94.58M b/d from 98.83M b/d. Later today, EIA will release official crude oil inventories data for week ending November 6.
US indices closed mixed on Tuesday with the Dow Jones (+0.90%) closing up, while the Nasdaq (-1.37%) and S&P 500 (-0.14%) closed down. Automobiles & Components (+3.48%), Energy (+2.52%) and Food, Beverage & Tobacco (+2.4%) sectors were the best performers on the day, while Semiconductors & Semiconductor Equipment (-3.43%), Software & Services (-2.36%) and Retailing (-1.62%) sectors were the worst performers.
The dollar index rose 0.26pt to 93.011.
U.S. Equity Snapshot
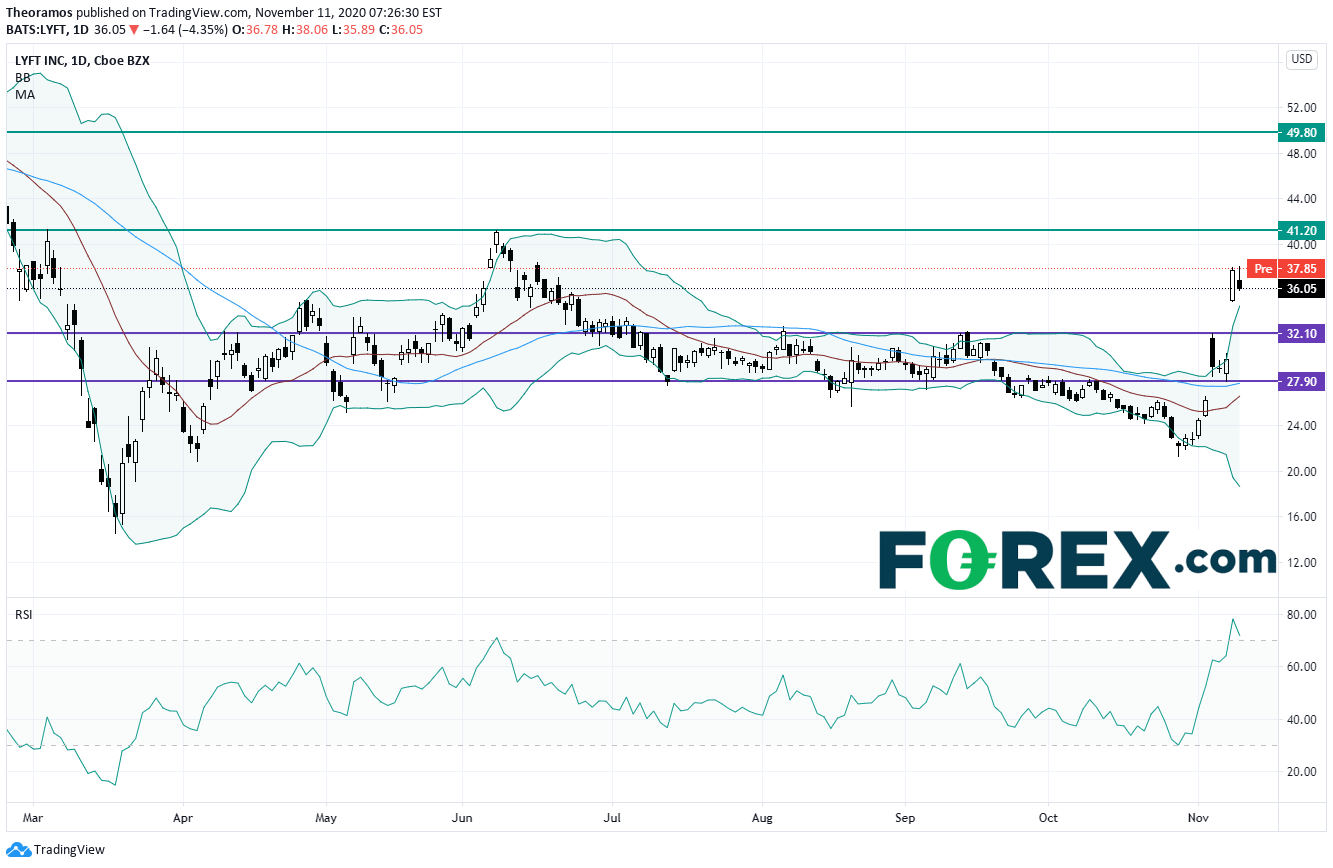
Lyft (LYFT), the ridesharing company, jumped after hours after reporting third quarter sales of 499.7 million dollars, above forecasts, down from 955.6 million dollars last year. LPS was 1.46 dollar, worse than expected, vs a LPS of 0.41 dollar a year ago. The company expects Ebitda to be positive by the fourth quarter of 2021.
Source: TradingView, GAIN Capital
Boeing (BA) won a 9.8 billion dollars contract from the Pentagon regarding F-15 support for Saudi Arabia.
CVS Health's (CVS), the pharmacy and healthcare company, price target was raised to 76 dollars from 72 dollars at Piper Sandler.
No major economic data are expected today.
European indices remain on the upside.
Asian indices ended on a positive note except the Chinese CSI. The Reserve Bank of New Zealand kept its benchmark rate unchanged at 0.25% as expected. RBNZ said additional stimulus would be provided through a Funding for Lending Programme (FLP), commencing in December, and "monetary policy will need to remain stimulatory for a long time".
WTI Crude Oil remains strongly bullish. The American Petroleum Institute (API) reported that U.S. crude-oil inventories dropped 5.1M barrels in the week ending November 6. The U.S. Energy Information Administration (EIA) projected that 2021 WTI Crude Oil forecast price would be $44.24/bbl, down from $44.72 in the previous estimation. The global oil demand for 2021 lowered to 98.80M b/d from 99.09M b/d, while global supply is also down to 94.58M b/d from 98.83M b/d. Later today, EIA will release official crude oil inventories data for week ending November 6.
US indices closed mixed on Tuesday with the Dow Jones (+0.90%) closing up, while the Nasdaq (-1.37%) and S&P 500 (-0.14%) closed down. Automobiles & Components (+3.48%), Energy (+2.52%) and Food, Beverage & Tobacco (+2.4%) sectors were the best performers on the day, while Semiconductors & Semiconductor Equipment (-3.43%), Software & Services (-2.36%) and Retailing (-1.62%) sectors were the worst performers.
Approximately 82% of stocks in the S&P 500 Index were trading above their 200-day moving average and 78% were trading above their 20-day moving average. The VIX Index dropped 1.23pt (-4.78%) to 24.52 and WTI Crude Oil gained $1.09 (+2.71%) to $41.38 at the close.
On the US economic data front, the National Federation of Independent Business's Small Business Optimism Index remained unchanged at 104.0 on month in October (104.1 expected), in line with September. Finally, U.S. Job Openings rose to 6.436 million on month in September (6.500 million expected), compared to a revised 6.352 million in August.Gold loses ground as the U.S dollar remains firm on return for risk appetite.
Gold fell 1.48 dollar (-0.08%) to 1875.85 dollars.The dollar index rose 0.26pt to 93.011.
U.S. Equity Snapshot
Lyft (LYFT), the ridesharing company, jumped after hours after reporting third quarter sales of 499.7 million dollars, above forecasts, down from 955.6 million dollars last year. LPS was 1.46 dollar, worse than expected, vs a LPS of 0.41 dollar a year ago. The company expects Ebitda to be positive by the fourth quarter of 2021.
Source: TradingView, GAIN Capital
Boeing (BA) won a 9.8 billion dollars contract from the Pentagon regarding F-15 support for Saudi Arabia.
CVS Health's (CVS), the pharmacy and healthcare company, price target was raised to 76 dollars from 72 dollars at Piper Sandler.



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.