



15 09 US PRE OPEN
The S&P 500 futures remain on the upside after they closed higher yesterday
Share this:
The S&P 500 futures remain on the upside after they closed higher yesterday.
Later today, the U.S. Labor Department will release August import price index (+0.5% on month expected). The New York Federal Reserve will publish September Empire Manufacturing Index (6.8 expected). The Federal Reserve will report August industrial production (+1.0% on month expected).
European indices are on the upside. ZEW survey results of September were released for Germany at -66.2 for current situation, vs -72.0 expected, and at 77.4 for the expectations, vs 69.5 expected. France's INSEE has posted final readings of August CPI at -0.1% on month, as expected. The U.K. Office for National Statistics has reported jobless rate for the three months to July at 4.1%, as expected.
Asian indices closed in dispersed order. Japanese Nikkei closed in the red when the Chinese CSI closed on the upside. Official data showed that China's industrial production rose 5.6% on year in August (+5.1% expected) and retail sales grew 0.5% (flat expected).
WTI Crude Oil futures are rebounding. OPEC downgraded the outlook for global oil market before an online monitoring meeting on Thursday, amid faltering demand and signs of a recovery of U.S. shale oil supply. Currently, OPEC projected that global oil demand would decrease by 9.46M b/d to 90.23M b/d in 2020. Later today, American Petroleum Institute (API) would release the change of U.S. oil stockpile data for September 11.
Gold rose 7.56$ (+0.39%) to 1964.42 on the way to 2000.
GBP/USD jumped 37pips to 1.2883 as U.K. Prime Minister Boris Johnson's Internal Market Bill, his plan to rewrite part of the Brexit deal, passed its first hurdle in Commons.
U.S. Equity Snapshot
Tiffany (TIF): a judge of the Delaware Court has scheduled a hearing on September 21 to allow the jeweler to plead, under an expedited procedure, its arguments for the French luxury goods giant, LVMH, to complete its merger project.
Nikola (NKLA): the U.S. Securities and Exchange Commission (SEC) announced that it is reviewing the case of the electric truck manufacturer accused by Hindenburg Research of making numerous false statements and assertions about its technology.
Later today, the U.S. Labor Department will release August import price index (+0.5% on month expected). The New York Federal Reserve will publish September Empire Manufacturing Index (6.8 expected). The Federal Reserve will report August industrial production (+1.0% on month expected).
European indices are on the upside. ZEW survey results of September were released for Germany at -66.2 for current situation, vs -72.0 expected, and at 77.4 for the expectations, vs 69.5 expected. France's INSEE has posted final readings of August CPI at -0.1% on month, as expected. The U.K. Office for National Statistics has reported jobless rate for the three months to July at 4.1%, as expected.
Asian indices closed in dispersed order. Japanese Nikkei closed in the red when the Chinese CSI closed on the upside. Official data showed that China's industrial production rose 5.6% on year in August (+5.1% expected) and retail sales grew 0.5% (flat expected).
WTI Crude Oil futures are rebounding. OPEC downgraded the outlook for global oil market before an online monitoring meeting on Thursday, amid faltering demand and signs of a recovery of U.S. shale oil supply. Currently, OPEC projected that global oil demand would decrease by 9.46M b/d to 90.23M b/d in 2020. Later today, American Petroleum Institute (API) would release the change of U.S. oil stockpile data for September 11.
Gold rose 7.56$ (+0.39%) to 1964.42 on the way to 2000.
GBP/USD jumped 37pips to 1.2883 as U.K. Prime Minister Boris Johnson's Internal Market Bill, his plan to rewrite part of the Brexit deal, passed its first hurdle in Commons.
U.S. Equity Snapshot
Tiffany (TIF): a judge of the Delaware Court has scheduled a hearing on September 21 to allow the jeweler to plead, under an expedited procedure, its arguments for the French luxury goods giant, LVMH, to complete its merger project.
Nikola (NKLA): the U.S. Securities and Exchange Commission (SEC) announced that it is reviewing the case of the electric truck manufacturer accused by Hindenburg Research of making numerous false statements and assertions about its technology.
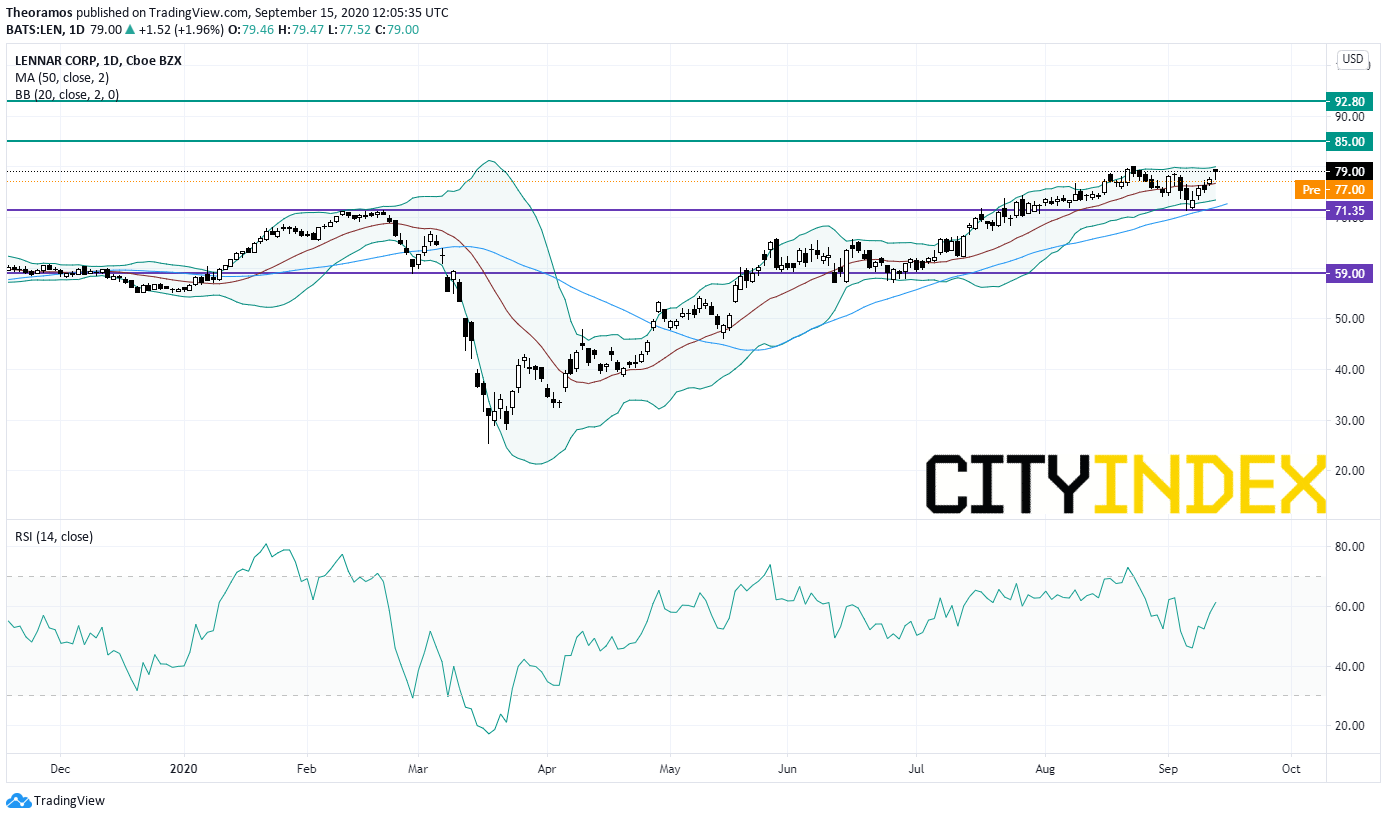
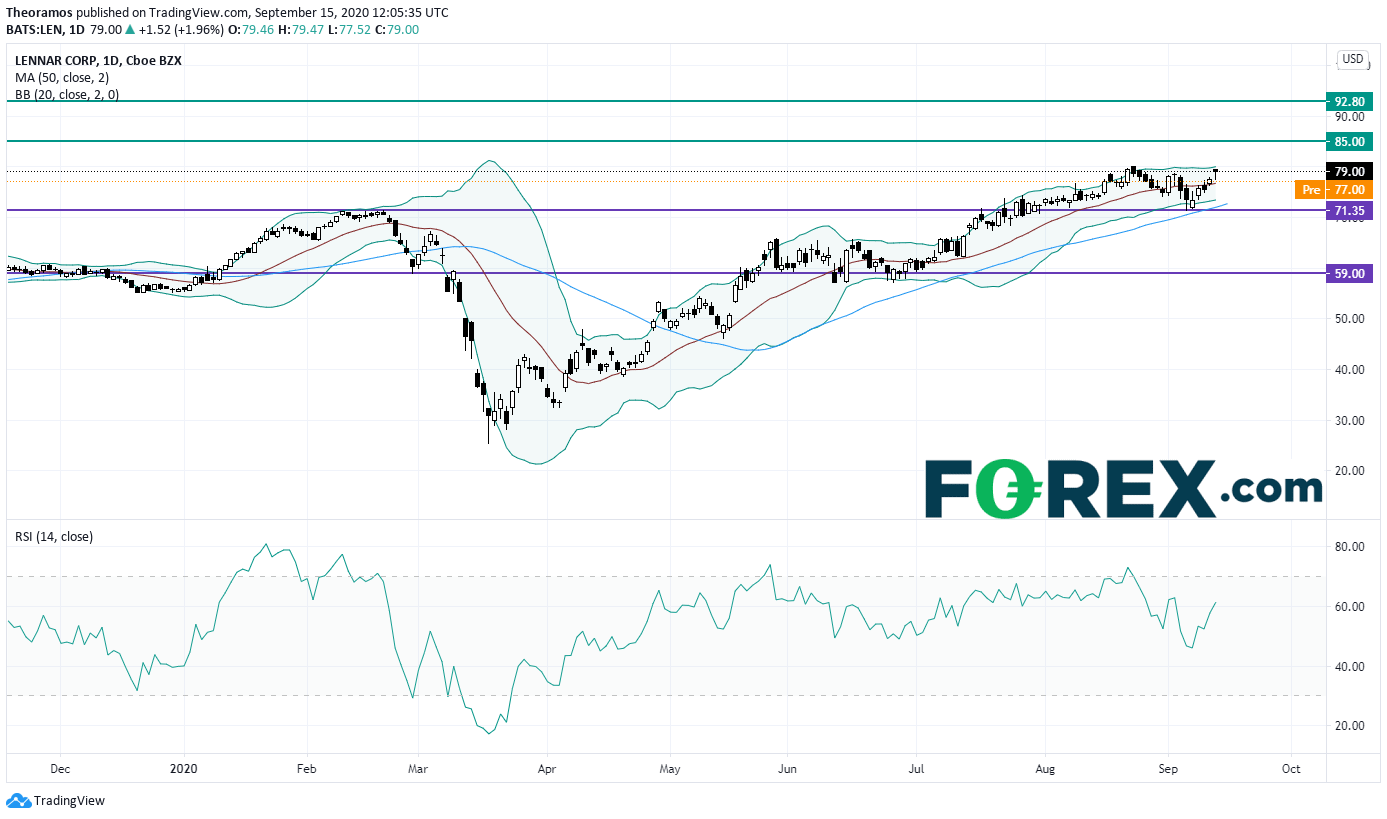
Lennar (LEN), the home construction company, reported third quarter EPS of 2.12 dollars, beating estimates, on revenue of 5.87 billion dollars, in line with expectations. The stock should nevertheless start the trading session in the red.
Source: GAIN Capital, TradingView
The S&P 500 futures remain on the upside after they closed higher yesterday.
Later today, the U.S. Labor Department will release August import price index (+0.5% on month expected). The New York Federal Reserve will publish September Empire Manufacturing Index (6.8 expected). The Federal Reserve will report August industrial production (+1.0% on month expected).
European indices are on the upside. ZEW survey results of September were released for Germany at -66.2 for current situation, vs -72.0 expected, and at 77.4 for the expectations, vs 69.5 expected. France's INSEE has posted final readings of August CPI at -0.1% on month, as expected. The U.K. Office for National Statistics has reported jobless rate for the three months to July at 4.1%, as expected.
Asian indices closed in dispersed order. Japanese Nikkei closed in the red when the Chinese CSI closed on the upside. Official data showed that China's industrial production rose 5.6% on year in August (+5.1% expected) and retail sales grew 0.5% (flat expected).
WTI Crude Oil futures are rebounding. OPEC downgraded the outlook for global oil market before an online monitoring meeting on Thursday, amid faltering demand and signs of a recovery of U.S. shale oil supply. Currently, OPEC projected that global oil demand would decrease by 9.46M b/d to 90.23M b/d in 2020. Later today, American Petroleum Institute (API) would release the change of U.S. oil stockpile data for September 11.
Gold rose 7.56$ (+0.39%) to 1964.42 on the way to 2000.
GBP/USD jumped 37pips to 1.2883 as U.K. Prime Minister Boris Johnson's Internal Market Bill, his plan to rewrite part of the Brexit deal, passed its first hurdle in Commons.
U.S. Equity Snapshot
Tiffany (TIF): a judge of the Delaware Court has scheduled a hearing on September 21 to allow the jeweler to plead, under an expedited procedure, its arguments for the French luxury goods giant, LVMH, to complete its merger project.
Later today, the U.S. Labor Department will release August import price index (+0.5% on month expected). The New York Federal Reserve will publish September Empire Manufacturing Index (6.8 expected). The Federal Reserve will report August industrial production (+1.0% on month expected).
European indices are on the upside. ZEW survey results of September were released for Germany at -66.2 for current situation, vs -72.0 expected, and at 77.4 for the expectations, vs 69.5 expected. France's INSEE has posted final readings of August CPI at -0.1% on month, as expected. The U.K. Office for National Statistics has reported jobless rate for the three months to July at 4.1%, as expected.
Asian indices closed in dispersed order. Japanese Nikkei closed in the red when the Chinese CSI closed on the upside. Official data showed that China's industrial production rose 5.6% on year in August (+5.1% expected) and retail sales grew 0.5% (flat expected).
WTI Crude Oil futures are rebounding. OPEC downgraded the outlook for global oil market before an online monitoring meeting on Thursday, amid faltering demand and signs of a recovery of U.S. shale oil supply. Currently, OPEC projected that global oil demand would decrease by 9.46M b/d to 90.23M b/d in 2020. Later today, American Petroleum Institute (API) would release the change of U.S. oil stockpile data for September 11.
Gold rose 7.56$ (+0.39%) to 1964.42 on the way to 2000.
GBP/USD jumped 37pips to 1.2883 as U.K. Prime Minister Boris Johnson's Internal Market Bill, his plan to rewrite part of the Brexit deal, passed its first hurdle in Commons.
U.S. Equity Snapshot
Tiffany (TIF): a judge of the Delaware Court has scheduled a hearing on September 21 to allow the jeweler to plead, under an expedited procedure, its arguments for the French luxury goods giant, LVMH, to complete its merger project.
Nikola (NKLA): the U.S. Securities and Exchange Commission (SEC) announced that it is reviewing the case of the electric truck manufacturer accused by Hindenburg Research of making numerous false statements and assertions about its technology.
Lennar (LEN), the home construction company, reported third quarter EPS of 2.12 dollars, beating estimates, on revenue of 5.87 billion dollars, in line with expectations. The stock should nevertheless start the trading session in the red.Source: GAIN Capital, TradingView
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?

USD/JPY unwind accelerates as GPIF headlines spark yen buying
Japanese assets are rallying after the government floated the prospect of the GPIF investing more heavily at home. While the proposal could have significant implications for global capital flows, it does not yet change the broader forces driving Japanese bond yields and USD/JPY.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.