



170420 US Pre Open
The S&P 500 futures continue to rise after Donald Trump announced a plan for eventually reopening the country's economy in several phases
Share this:

The S&P 500 futures continue to rise after U.S. President Donald Trump announced a plan for eventually reopening the country's economy in several phases -- "Opening Up America Again" -- which is based on the severity of the coronavirus outbreak in each individual state. At the same time, New York and other East Coast states announced extension of their shutdown of nonessential businesses to May 15.
Later today, the Conference Board will release its Leading Index for March (-7.0% on month expected). In Canada, new motor vehicle sales for February are expected at 120.000.
European indices are bouncing. The European Commission has posted final readings of March CPI at +0.7% on year, as expected.
Asian indices all closed on a strong up move. This morning, official data showed that China's 1Q GDP dropped 6.8% on year (-6.0% expected), while industrial production fell 1.1% in March (-6.2% expected) and retail sales declined 15.8% (-10.0% expected).
US Equity Snapshot
Gilead Sciences (GILD), the biopharmaceutical company, surged on extended trading after STAT News reported that that a clinical trial of the company's coronavirus drug showed promising results.
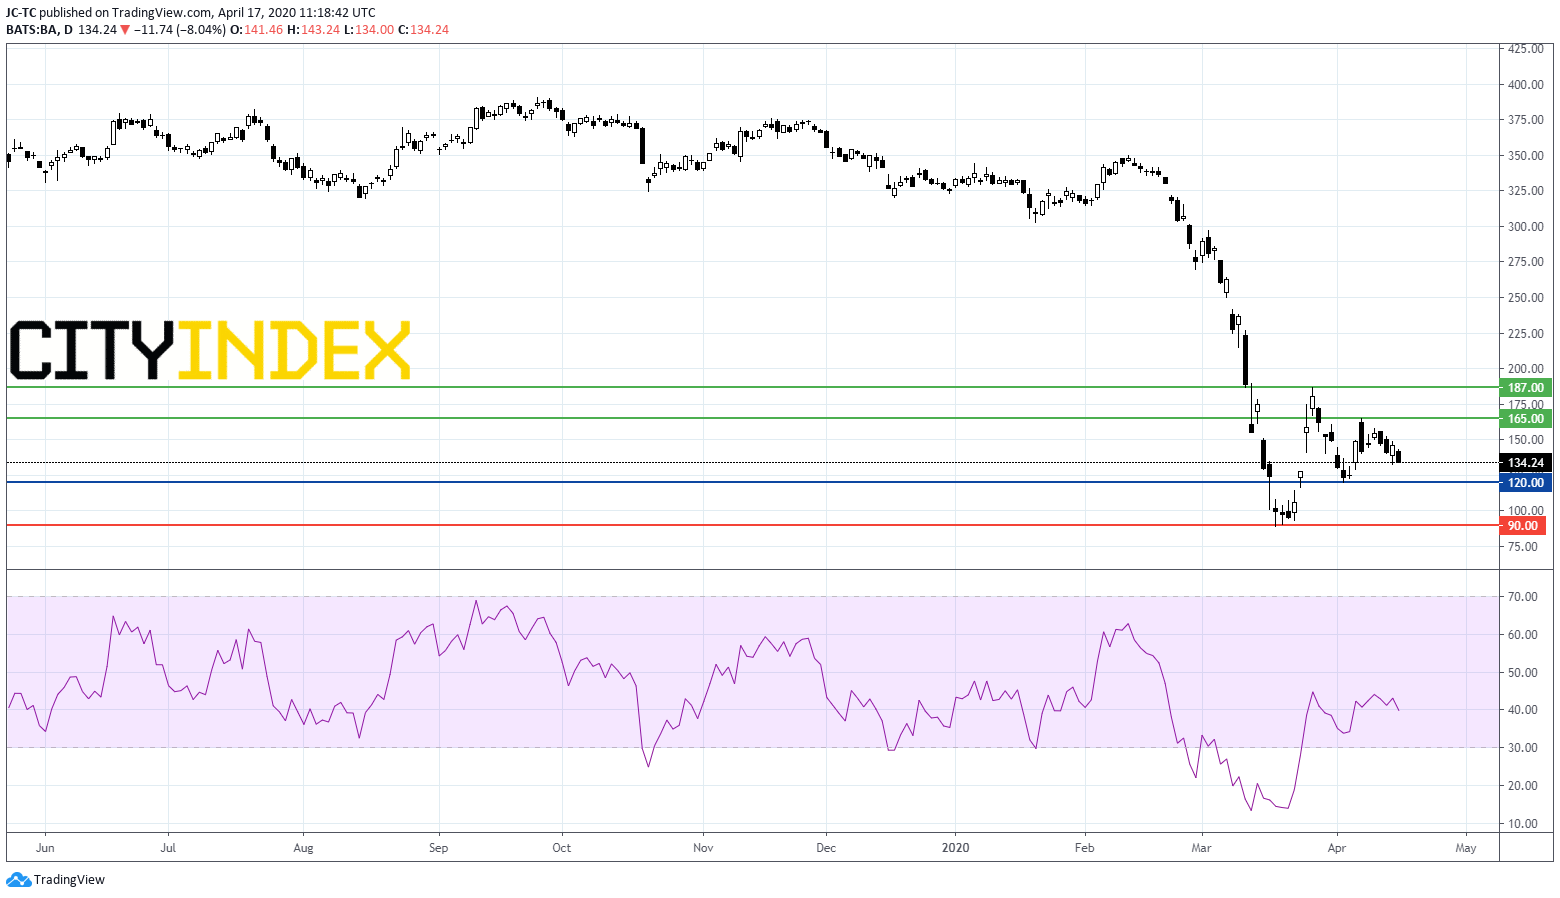
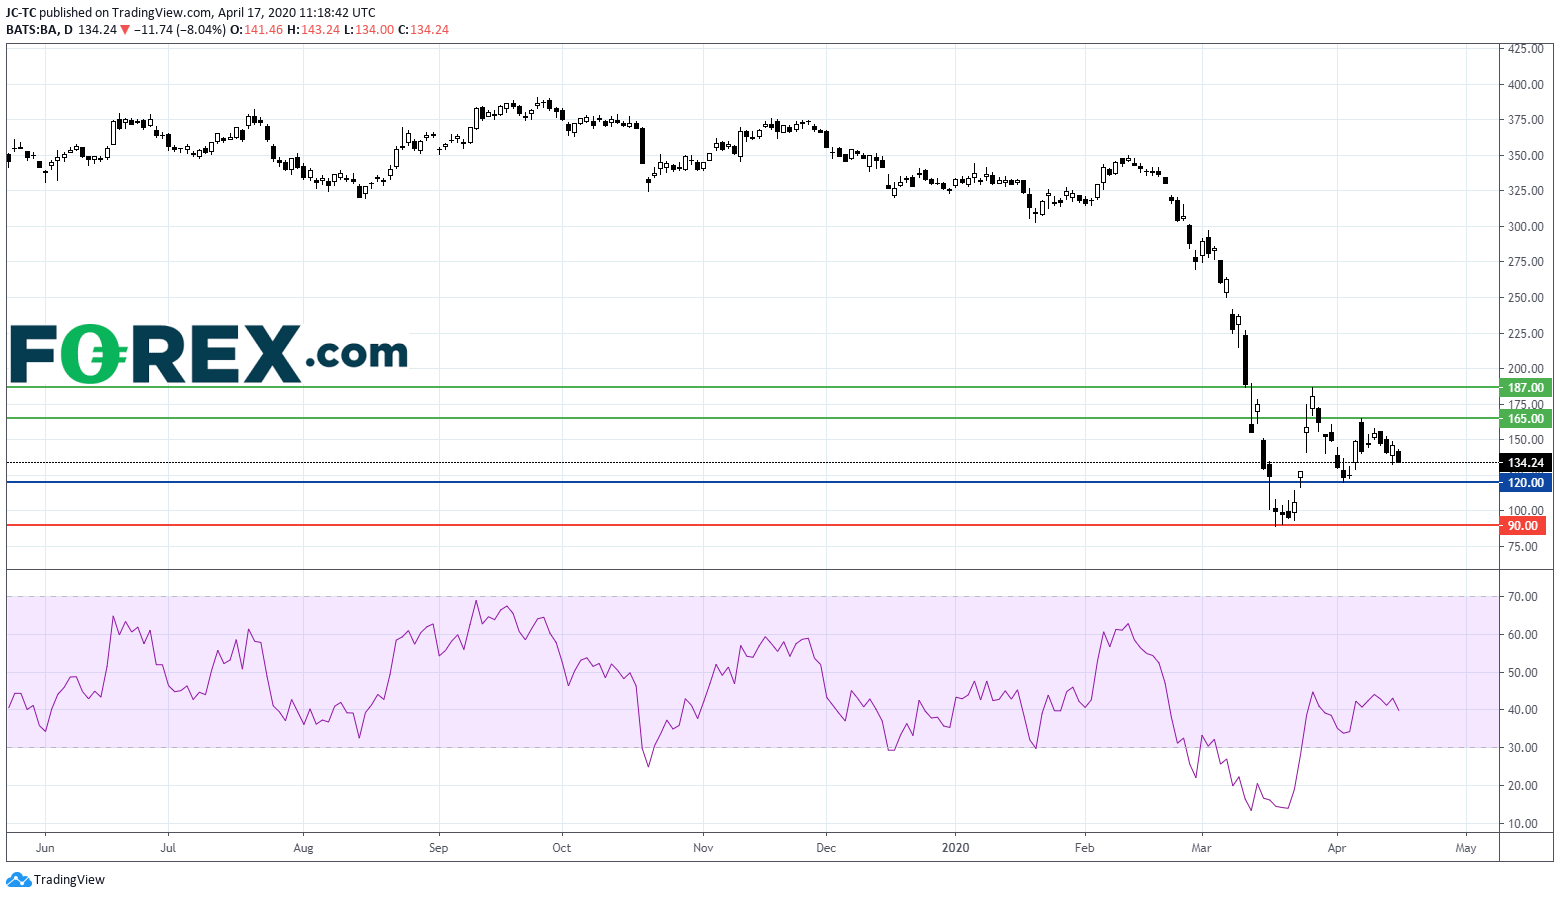
Boeing (BA), the aircraft manufacturer, said it will resume next week all commercial-airplane production in a phased approach at its Washington State plants. Operations there have been halted since last month in response to the COVID-19 pandemic.
Apple (AAPL), the tech giant, was downgraded to "sell" from "neutral" at Goldman Sachs.
Schlumberger (SLB), the supplier of oil and gas products and services, posted first quarter adjusted EPS down to 0.25 dollar from 0.30 dollar a year earlier, just above estimates. The company reduces its quarterly dividend by 75% to 0.125 dollar per share, the first cut since decades.
Intuitive Surgical (ISRG), the developer of robotic systems for the medical industry, reported first quarter adjusted EPS up to 2.69 dollars, above estimates, up from 2.61 dollars a year ago, on revenue up to 1.1 billion dollars, also beating consensus, from 973.7 million dollars last year.
Uber Technologies (UBER), the ride-hailing company, announced the withdrawal of its 2020 earnings guidance provided on February 6, citing the COVID-19 impacts. In addition, the company said it expects to record an impairment charge of 1.9 - 2.2 billion dollars on its minority equity investments.
Later today, the Conference Board will release its Leading Index for March (-7.0% on month expected). In Canada, new motor vehicle sales for February are expected at 120.000.
European indices are bouncing. The European Commission has posted final readings of March CPI at +0.7% on year, as expected.
Asian indices all closed on a strong up move. This morning, official data showed that China's 1Q GDP dropped 6.8% on year (-6.0% expected), while industrial production fell 1.1% in March (-6.2% expected) and retail sales declined 15.8% (-10.0% expected).
Donald Trump announcement was seen as a positive signal for the U.S. economy and pushed the US dollar higher versus its pairs. EUR/USD fell 10 pips to 1.083, GBP/USD declined 8 pips to 1.2449, and USD/JPY dropped 10 pips to 107.82.
WTI Crude Oil Futures are falling back below 20 dollars a barrel. The Organization of the Petroleum Exporting Countries (OPEC) said global oil demand would drop by 20 million barrels per day in April, about one-fifth of previous demand.
US Equity Snapshot
Gilead Sciences (GILD), the biopharmaceutical company, surged on extended trading after STAT News reported that that a clinical trial of the company's coronavirus drug showed promising results.
Boeing (BA), the aircraft manufacturer, said it will resume next week all commercial-airplane production in a phased approach at its Washington State plants. Operations there have been halted since last month in response to the COVID-19 pandemic.
Apple (AAPL), the tech giant, was downgraded to "sell" from "neutral" at Goldman Sachs.
Schlumberger (SLB), the supplier of oil and gas products and services, posted first quarter adjusted EPS down to 0.25 dollar from 0.30 dollar a year earlier, just above estimates. The company reduces its quarterly dividend by 75% to 0.125 dollar per share, the first cut since decades.
Intuitive Surgical (ISRG), the developer of robotic systems for the medical industry, reported first quarter adjusted EPS up to 2.69 dollars, above estimates, up from 2.61 dollars a year ago, on revenue up to 1.1 billion dollars, also beating consensus, from 973.7 million dollars last year.
Uber Technologies (UBER), the ride-hailing company, announced the withdrawal of its 2020 earnings guidance provided on February 6, citing the COVID-19 impacts. In addition, the company said it expects to record an impairment charge of 1.9 - 2.2 billion dollars on its minority equity investments.
Source : TradingView, GAIN Capital
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


USD/JPY Weekly Outlook: Payrolls loom as US rates remain the dominant driver
Strong US growth and hawkish Fed pricing continue to support USD/JPY, while intervention risk appears to be kicking in at lower levels
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.