



Accelerating core inflation spurs AUDUSD higher
This morning's release of Australian inflation data for the September quarter has proved to be the spark the currency market needed after a dull session overnight.
Share this:

Headline inflation rose by 0.8% over the quarter vs. expectations for a rise of 0.8%, while the annual rate of headline inflation fell to 3%, vs. expectations of 3.1% as base effects continued to fade.
However, core inflation as measured by the RBA's preferred measure, the "trimmed mean," surprised to the upside printing at 0.7 q/q vs. market expectations of 0.5%q/q, with the annual rate rising to 2.1% vs. expectations of 1.8%. Thereby seeing the core inflation rate return to the RBA's 2-3% band for the first time in six years.
There has been a tendency to look through lockdown affected economic data of late. Still, due to surging global inflation on supply bottlenecks and higher energy prices, today's inflation data was very much in focus.
Particularly after robust inflation data in New Zealand last week saw front end yields reprice higher in New Zealand and Australia, pointing to an early start to rate hikes in Australia than forecast by the RBA that interest rate hikes are unlikely before 2024.
The Reserve Bank of Australia has previously stated that it wants to see inflation return "sustainably" within its 2 percent to 3 percent target band and wages growth above 3 percent on an annualised basis before it starts to normalise policy. As such, the RBA will likely look through today's data.
However, the interest market is not taking such a sanguine view of the world. Front end yields have moved sharply higher, challenging the RBA to step in again to protect or remove a key part of its monetary policy settings, the 0.1% Yield Curve Control target on the April 2024 bond.
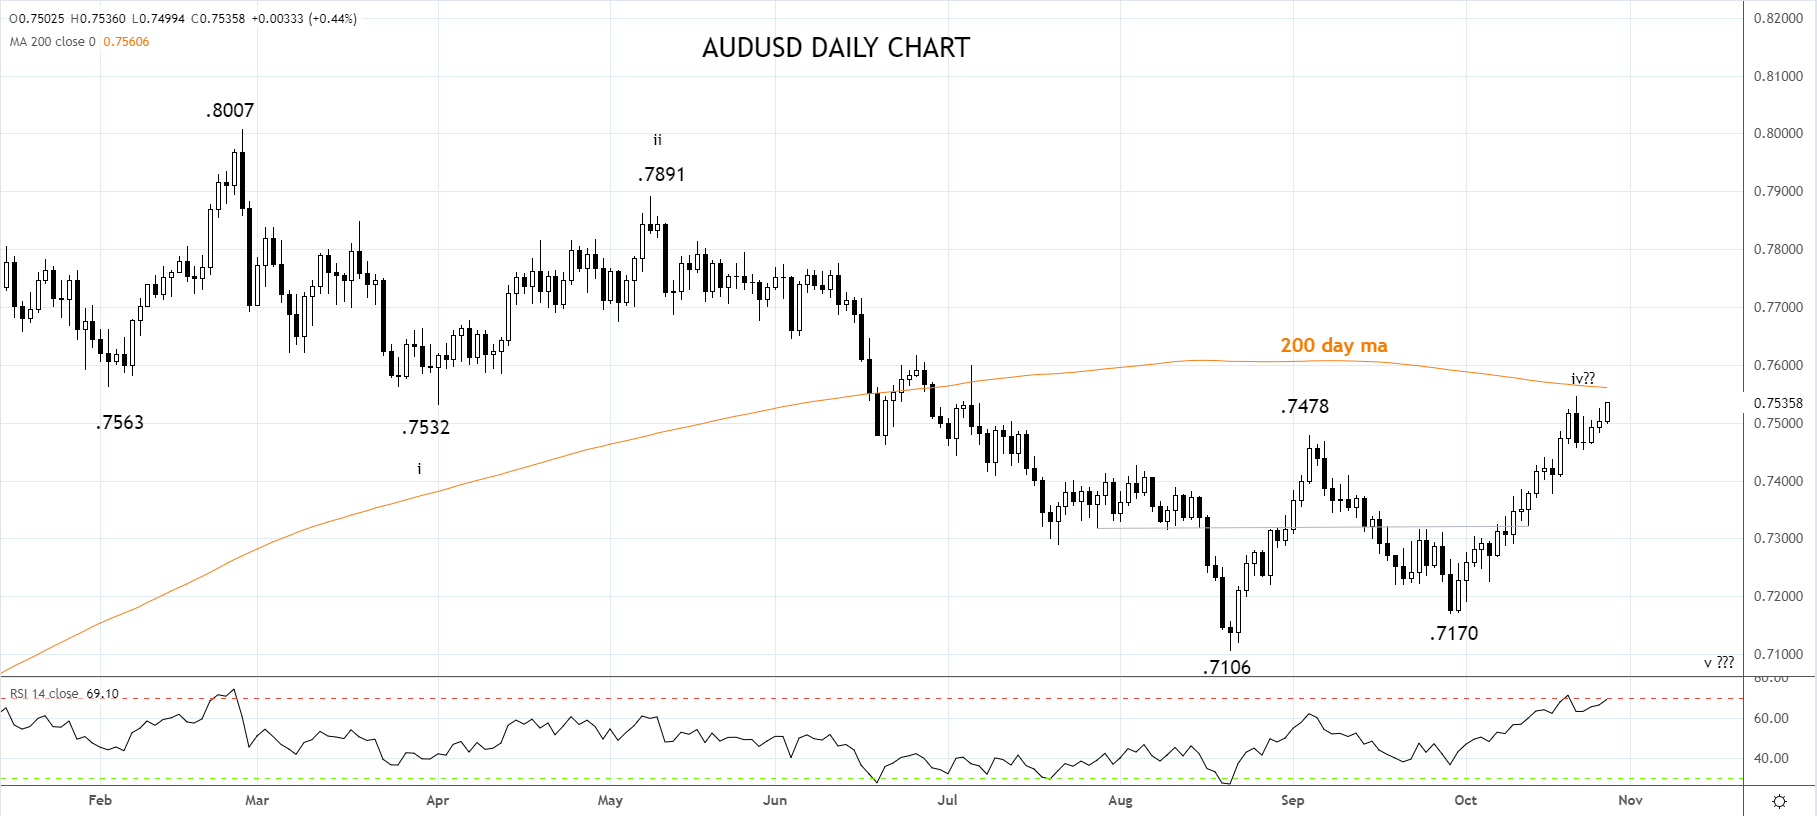
In response to higher yields, the AUDUSD has rallied from .7510 to .7533 at the time of writing, eying significant resistance at .7550/60c coming from wave equality and the 200-day ma.
We aren't necessarily convinced that the AUDUSD will see a sustained break above this resistance; however, with the reflation trade making a return after a five-month hiatus, we aren't looking to pick a fight with the AUDUSD at this point either.
Source Tradingview. The figures stated areas of October 27th, 2021. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
Headline inflation rose by 0.8% over the quarter vs. expectations for a rise of 0.8%, while the annual rate of headline inflation fell to 3%, vs. expectations of 3.1% as base effects continued to fade.
However, core inflation as measured by the RBA's preferred measure, the "trimmed mean," surprised to the upside printing at 0.7 q/q vs. market expectations of 0.5%q/q, with the annual rate rising to 2.1% vs. expectations of 1.8%. Thereby seeing the core inflation rate return to the RBA's 2-3% band for the first time in six years.
There has been a tendency to look through lockdown affected economic data of late. Still, due to surging global inflation on supply bottlenecks and higher energy prices, today's inflation data was very much in focus.
Particularly after robust inflation data in New Zealand last week saw front end yields reprice higher in New Zealand and Australia, pointing to an early start to rate hikes in Australia than forecast by the RBA that interest rate hikes are unlikely before 2024.
The Reserve Bank of Australia has previously stated that it wants to see inflation return "sustainably" within its 2 percent to 3 percent target band and wages growth above 3 percent on an annualised basis before it starts to normalise policy. As such, the RBA will likely look through today's data.
However, the interest market is not taking such a sanguine view of the world. Front end yields have moved sharply higher, challenging the RBA to step in again to protect or remove a key part of its monetary policy settings, the 0.1% Yield Curve Control target on the April 2024 bond.
In response to higher yields, the AUDUSD has rallied from .7510 to .7533 at the time of writing, eying significant resistance at .7550/60c coming from wave equality and the 200-day ma.
We aren't necessarily convinced that the AUDUSD will see a sustained break above this resistance; however, with the reflation trade making a return after a five-month hiatus, we aren't looking to pick a fight with the AUDUSD at this point either.
Source Tradingview. The figures stated areas of October 27th, 2021. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.