








Another Look at the US Yield Curve
A month and a half later, the US yield curve has reached the 61.8% Fibonacci retracement level
Share this:

In early September, we discussed how the yield curve briefly turned negative. The yield curve we referenced was the difference between the US 10-year yield and the US 2-year yield. Why was this such a big deal? Because on the last 7 occasions, it led to a recession (however the recessions were 6-9 months later). At the time, we compared the price action of the inverted yield curve to the price action in WTI Crude oil from Q4 of 2019. We considered the possibility that after selling off and bottoming, the yield curve may form an Inverted Head and Shoulders pattern and a move back to the 61.8% Fibonacci retracement level of the entire move lower, just as WTI Crude oil had done in Q4 of 2019.
Source: Tradingview, City Index
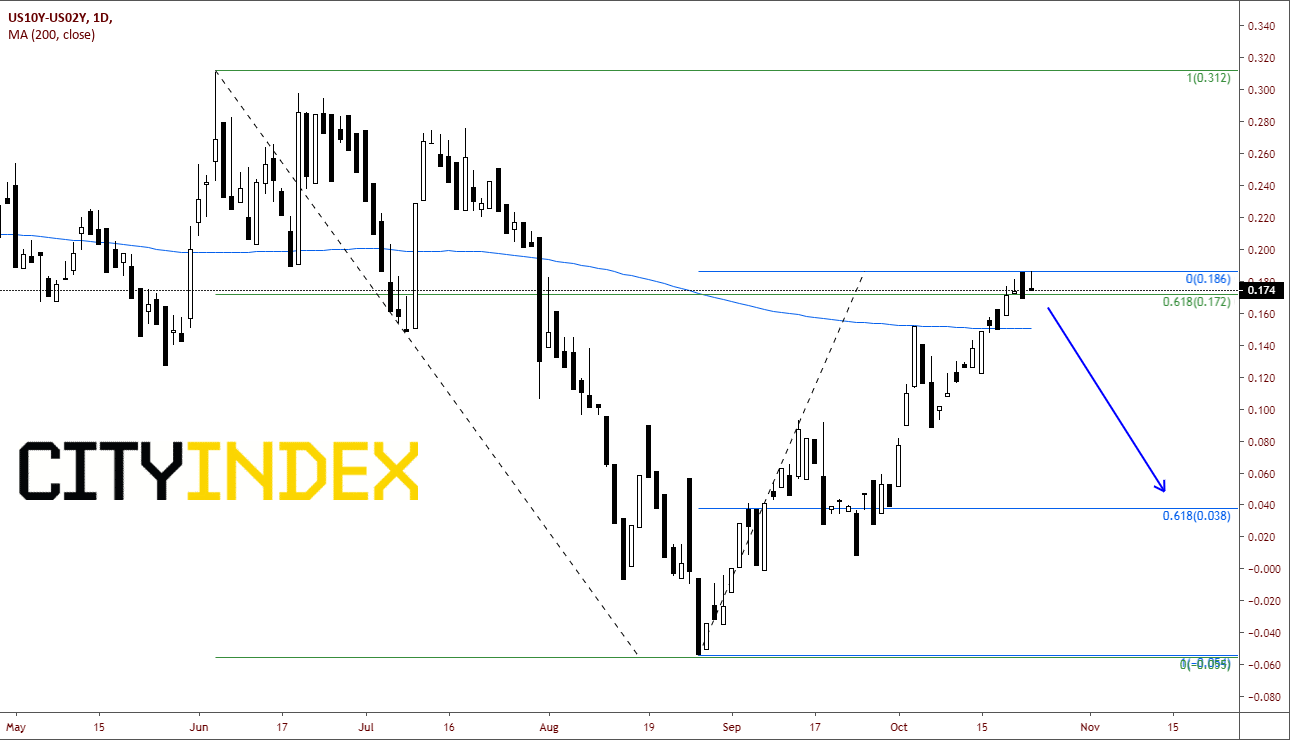
A month and a half later, the US yield curve has reached the 61.8% Fibonacci retracement level, met the target level for the inverted head and shoulders pattern, and put in a bearish engulfing pattern yesterday on the daily chart.
Source: Tradingview, City Index
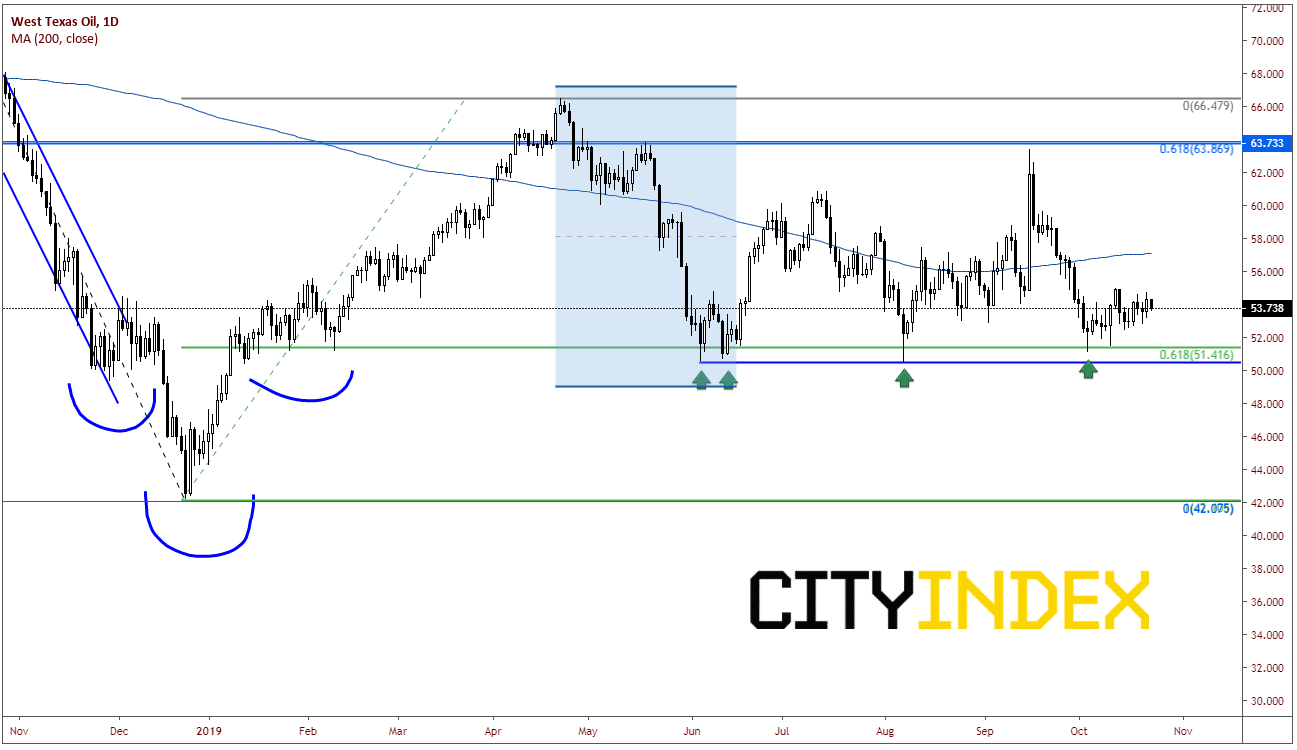
Where does the yield curve go from here? Let’s first look at the daily WTI crude chart, which had a false price breakout above the 61.8% Fibonaccci retracement level and pulled back, forming a wide consolidation channel between 50.50 and 63.80. Today, 6 months after the start of the channel, WTI Crude oil is still trading within that channel, mean reverting around the 200 Day Moving Average. However, price did test the lows 4 times.
Source: Tradingview, City Index
If we focus on the price action in WTI Crude Oil as it pulled back after reaching the highs on April 23rd at 66.48, we see that price pulled back to the 61.8% Fibonacci retracement level from the lows on December 24th to the highs on April 23rd and put in a double bottom. This low defined the bottom of the channel, within which price currently trades.
Source: Tradingview, City Index
Now, if we theorize that the US Yield Curve will act in the same manner as WTI Crude oil, we can look for the US yield curve to pull back to the 61.8% Fibonacci retracement level from the August 27th lows to yesterday’s highs, which is 0.038.
Source: Tradingview, City Index
If the US yield curve does pull back to that level, what happens next? Will it head into negative territory again?
Let’s take one step at a time….but keep an eye on WTI Crude Oil for clues!
In early September, we discussed how the yield curve briefly turned negative. The yield curve we referenced was the difference between the US 10-year yield and the US 2-year yield. Why was this such a big deal? Because on the last 7 occasions, it led to a recession (however the recessions were 6-9 months later). At the time, we compared the price action of the inverted yield curve to the price action in WTI Crude oil from Q4 of 2019. We considered the possibility that after selling off and bottoming, the yield curve may form an Inverted Head and Shoulders pattern and a move back to the 61.8% Fibonacci retracement level of the entire move lower, just as WTI Crude oil had done in Q4 of 2019.
Source: Tradingview, FOREX.com
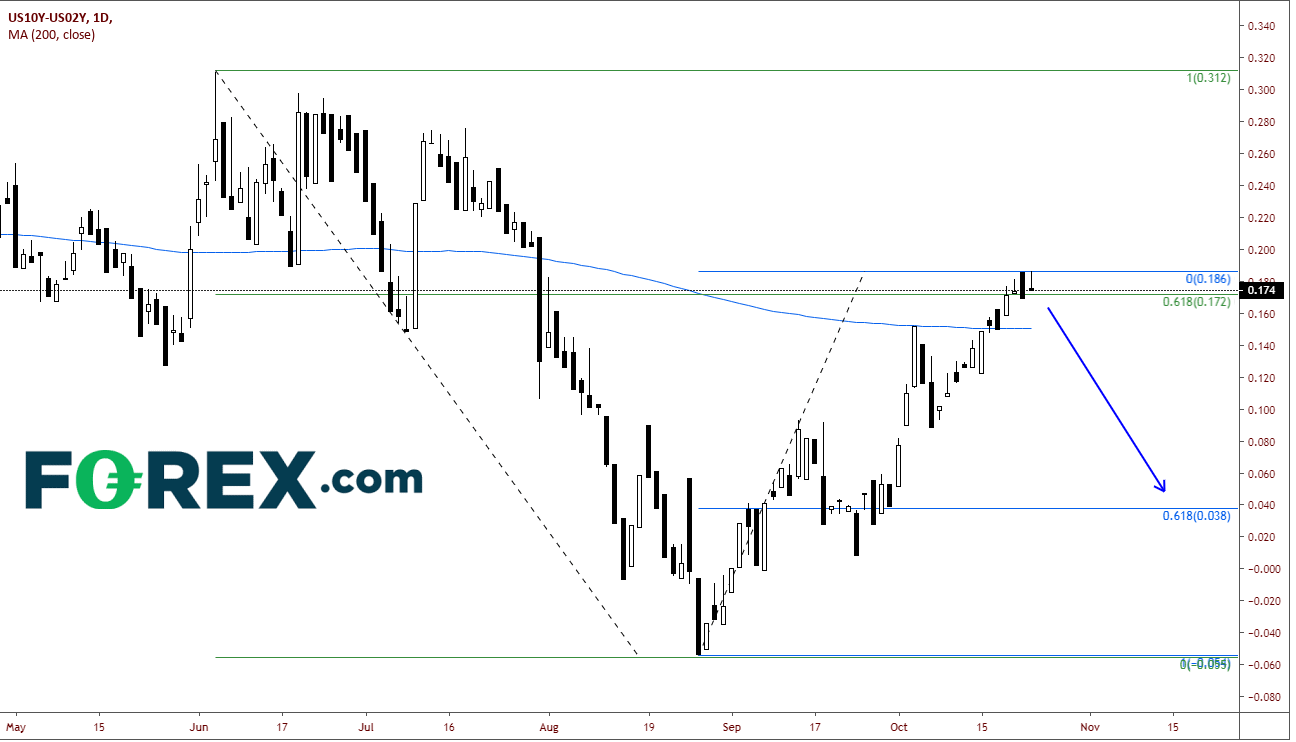
A month and a half later, the US yield curve has reached the 61.8% Fibonacci retracement level, met the target level for the inverted head and shoulders pattern, and put in a bearish engulfing pattern yesterday on the daily chart.
Source: Tradingview, FOREX.com
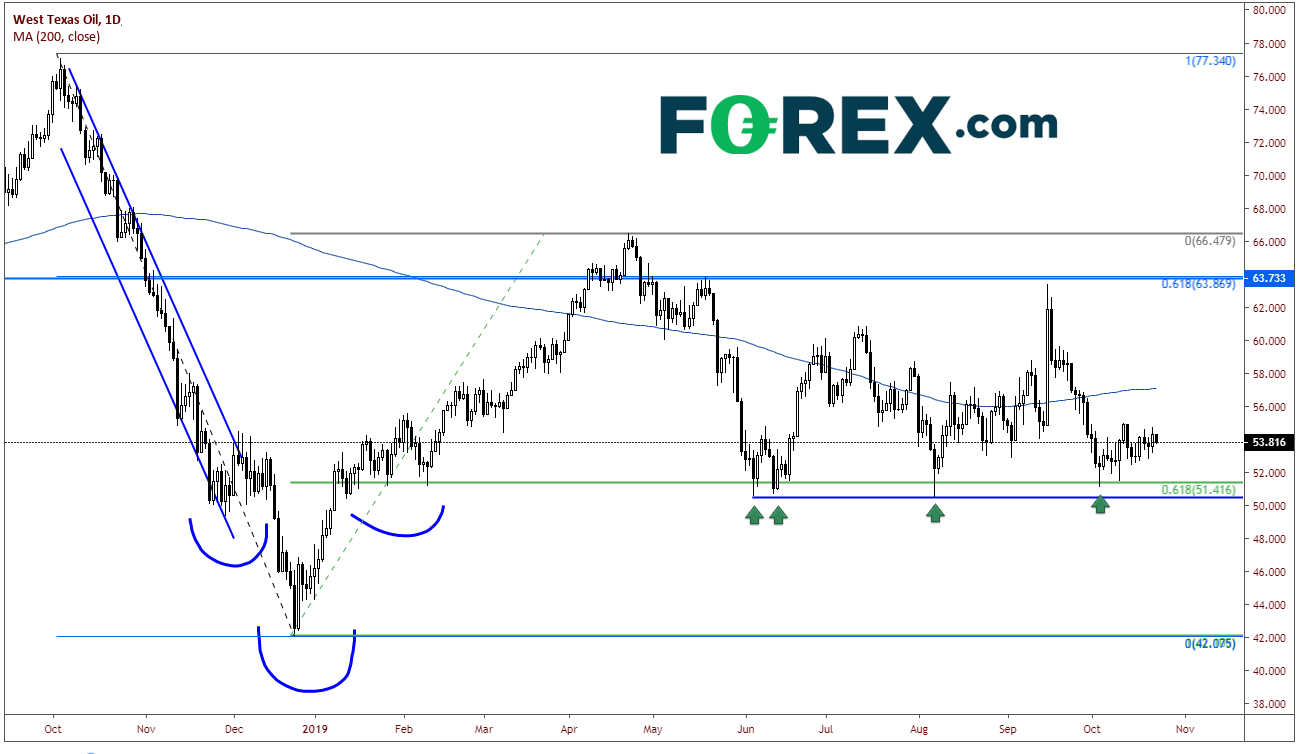
Where does the yield curve go from here? Let’s first look at the daily WTI crude chart, which had a false price breakout above the 61.8% Fibonaccci retracement level and pulled back, forming a wide consolidation channel between 50.50 and 63.80. Today, 6 months after the start of the channel, WTI Crude oil is still trading within that channel, mean reverting around the 200 Day Moving Average. However, price did test the lows 4 times.
Source: Tradingview, FOREX.com
If we focus on the price action in WTI Crude Oil as it pulled back after reaching the highs on April 23rd at 66.48, we see that price pulled back to the 61.8% Fibonacci retracement level from the lows on December 24th to the highs on April 23rd and put in a double bottom. This low defined the bottom of the channel, within which price currently trades.
Source: Tradingview, FOREX.com
Now, if we theorize that the US Yield Curve will act in the same manner as WTI Crude oil, we can look for the US yield curve to pull back to the 61.8% Fibonacci retracement level from the August 27th lows to yesterday’s highs, which is 0.038.
Source: Tradingview, FOREX.com
If the US yield curve does pull back to that level, what happens next? Will it head into negative territory again?
Let’s take one step at a time….but keep an eye on WTI Crude Oil for clues!
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.
Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.