



Asia Morning Oct 12
President Donald Trump says he wants to see a larger stimulus package...
Share this:

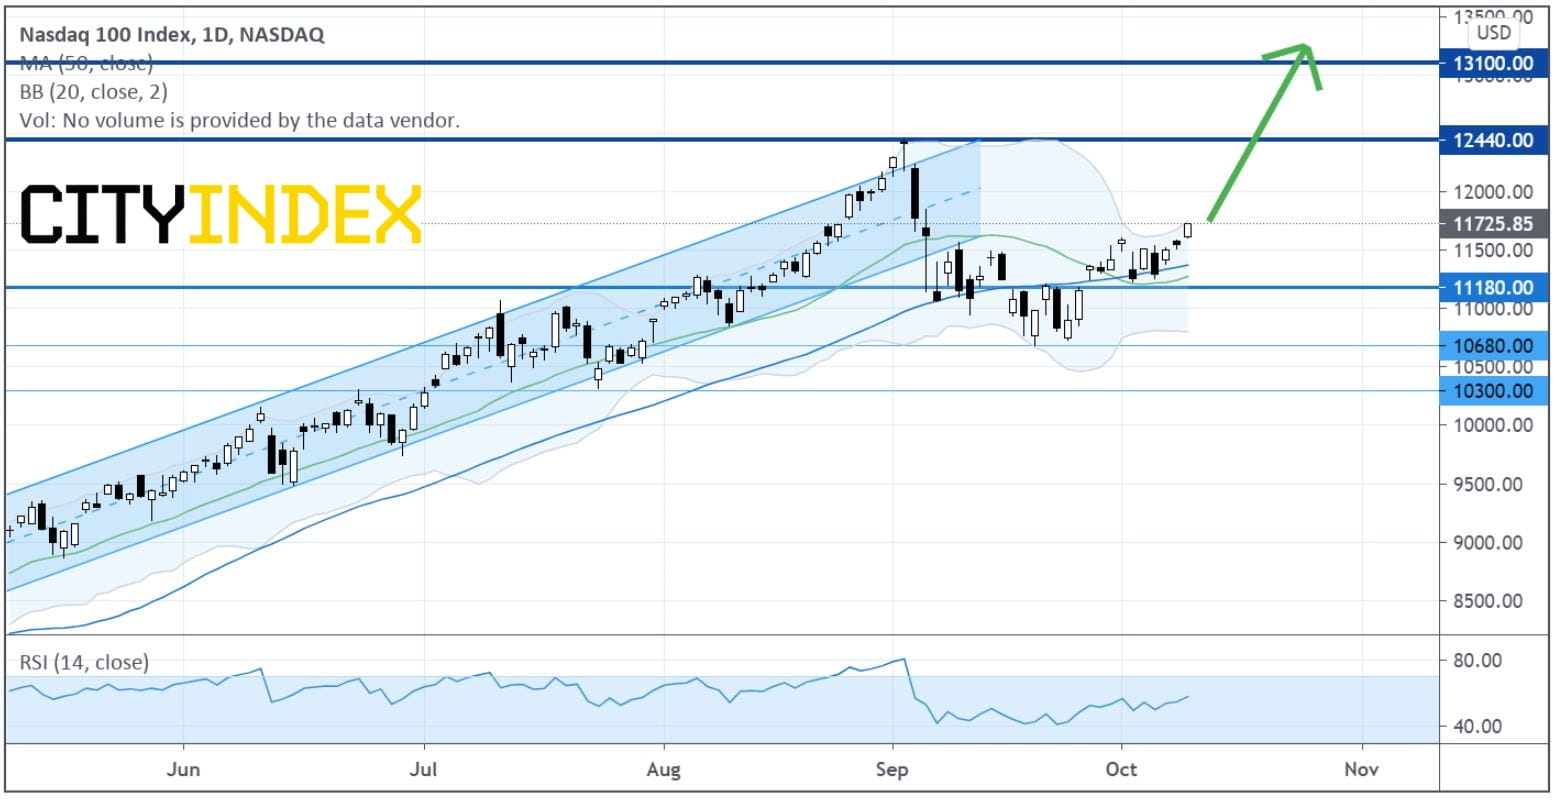
On Friday, U.S. stocks posted further gains. The Dow Jones Industrial Average increased 161 points (+0.57%) to 28586, the S&P 500 rose 30 points (+0.88%) to 3477, and the Nasdaq 100 was up 174 points (+1.51%) to 11725.
Nasdaq 100 Index: Rebound Continues
Sources: GAIN Capital, TradingView
Stocks climbed, gold jumped and the U.S. dollar slid on growing expectations of a forthcoming fiscal stimulus package. U.S. President Donald Trump said in an interview that he wants to see a larger stimulus package than the one offered by either Democrats or Republicans.
Approximately 75% (70% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 89% (79% in the prior session) were trading above their 20-day moving average.
European stocks remained buoyed. The Stoxx Europe 600 Index rose 0.55%, France's CAC 40 rose 0.71% and the U.K.'s FTSE 100 added 0.65%, while Germany's DAX 30 was little changed.
U.S. Treasury prices slipped, as the benchmark 10-year Treasury yield advanced to 0.772% from 0.764% Thursday.
Spot gold price took advantage of a weaker dollar jumping $34 (+1.84%) to $1,928 an ounce.
U.S. WTI crude futures (November) fell $0.66 (-1.60%) to $40.53 a barrel.
On the forex front, the U.S. dollar was broadly lower across the board, pressured by the U.S. government's signal that it could accept a larger stimulus package. The ICE Dollar Index dropped 0.55% to 93.06.
EUR/USD regained the 1.1800 level as it jumped 0.6% to 1.1829. The pair has returned to levels above both its 20-day and 50-day moving averages.
GBP/USD crossed above the key 1.3000 level by rising 0.84% to 1.3046. Official data showed that U.K. industrial production edged up 0.3% on month in August (+2.5% expected).
USD/JPY failed to hold the key 106.00 level and close 0.38% lower at 105.62.
Commodity-related currencies charged higher. AUD/USD surged 1.05% to 0.7240 extending its winning streak to a third session.
USD/CAD was down for a third day sinking 0.57% to 1.3121.
The Chinese yuan (offshore) continued its recent rally against the greenback. USD/CNH slid a further 0.77% to 6.6867, the lowest level since April 2019.
Nasdaq 100 Index: Rebound Continues
Sources: GAIN Capital, TradingView
Stocks climbed, gold jumped and the U.S. dollar slid on growing expectations of a forthcoming fiscal stimulus package. U.S. President Donald Trump said in an interview that he wants to see a larger stimulus package than the one offered by either Democrats or Republicans.
Retailing (+2.08%), Software & Services (+1.94%) and Technology Hardware & Equipment (+1.45%) sectors performed the best. Xilinx (XLNX +14.11%) gained the most after reports that Advanced Micro Devices (AMD -3.94%) may buy the company for $30 billion. eBay (EBAY +6.47%) and Fortinet (FTNT +3.73%) were also top gainers.
Approximately 75% (70% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 89% (79% in the prior session) were trading above their 20-day moving average.
European stocks remained buoyed. The Stoxx Europe 600 Index rose 0.55%, France's CAC 40 rose 0.71% and the U.K.'s FTSE 100 added 0.65%, while Germany's DAX 30 was little changed.
U.S. Treasury prices slipped, as the benchmark 10-year Treasury yield advanced to 0.772% from 0.764% Thursday.
Spot gold price took advantage of a weaker dollar jumping $34 (+1.84%) to $1,928 an ounce.
U.S. WTI crude futures (November) fell $0.66 (-1.60%) to $40.53 a barrel.
On the forex front, the U.S. dollar was broadly lower across the board, pressured by the U.S. government's signal that it could accept a larger stimulus package. The ICE Dollar Index dropped 0.55% to 93.06.
EUR/USD regained the 1.1800 level as it jumped 0.6% to 1.1829. The pair has returned to levels above both its 20-day and 50-day moving averages.
GBP/USD crossed above the key 1.3000 level by rising 0.84% to 1.3046. Official data showed that U.K. industrial production edged up 0.3% on month in August (+2.5% expected).
USD/JPY failed to hold the key 106.00 level and close 0.38% lower at 105.62.
Commodity-related currencies charged higher. AUD/USD surged 1.05% to 0.7240 extending its winning streak to a third session.
USD/CAD was down for a third day sinking 0.57% to 1.3121.
The Chinese yuan (offshore) continued its recent rally against the greenback. USD/CNH slid a further 0.77% to 6.6867, the lowest level since April 2019.
On Friday, U.S. stocks posted further gains. The Dow Jones Industrial Average increased 161 points (+0.57%) to 28586, the S&P 500 rose 30 points (+0.88%) to 3477, and the Nasdaq 100 was up 174 points (+1.51%) to 11725.
Nasdaq 100 Index: Rebound Continues

Sources: GAIN Capital, TradingView
Stocks climbed, gold jumped and the U.S. dollar slid on growing expectations of a forthcoming fiscal stimulus package. U.S. President Donald Trump said in an interview that he wants to see a larger stimulus package than the one offered by either Democrats or Republicans.
Approximately 75% (70% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 89% (79% in the prior session) were trading above their 20-day moving average.
European stocks remained buoyed. The Stoxx Europe 600 Index rose 0.55%, France's CAC 40 rose 0.71% and the U.K.'s FTSE 100 added 0.65%, while Germany's DAX 30 was little changed.
U.S. Treasury prices slipped, as the benchmark 10-year Treasury yield advanced to 0.772% from 0.764% Thursday.
Spot gold price took advantage of a weaker dollar jumping $34 (+1.84%) to $1,928 an ounce.
U.S. WTI crude futures (November) fell $0.66 (-1.60%) to $40.53 a barrel.
On the forex front, the U.S. dollar was broadly lower across the board, pressured by the U.S. government's signal that it could accept a larger stimulus package. The ICE Dollar Index dropped 0.55% to 93.06.
EUR/USD regained the 1.1800 level as it jumped 0.6% to 1.1829. The pair has returned to levels above both its 20-day and 50-day moving averages.
GBP/USD crossed above the key 1.3000 level by rising 0.84% to 1.3046. Official data showed that U.K. industrial production edged up 0.3% on month in August (+2.5% expected).
USD/JPY failed to hold the key 106.00 level and close 0.38% lower at 105.62.
Commodity-related currencies charged higher. AUD/USD surged 1.05% to 0.7240 extending its winning streak to a third session.
USD/CAD was down for a third day sinking 0.57% to 1.3121.
The Chinese yuan (offshore) continued its recent rally against the greenback. USD/CNH slid a further 0.77% to 6.6867, the lowest level since April 2019.
Nasdaq 100 Index: Rebound Continues
Sources: GAIN Capital, TradingView
Stocks climbed, gold jumped and the U.S. dollar slid on growing expectations of a forthcoming fiscal stimulus package. U.S. President Donald Trump said in an interview that he wants to see a larger stimulus package than the one offered by either Democrats or Republicans.
Retailing (+2.08%), Software & Services (+1.94%) and Technology Hardware & Equipment (+1.45%) sectors performed the best. Xilinx (XLNX +14.11%) gained the most after reports that Advanced Micro Devices (AMD -3.94%) may buy the company for $30 billion. eBay (EBAY +6.47%) and Fortinet (FTNT +3.73%) were also top gainers.
Approximately 75% (70% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average and 89% (79% in the prior session) were trading above their 20-day moving average.
European stocks remained buoyed. The Stoxx Europe 600 Index rose 0.55%, France's CAC 40 rose 0.71% and the U.K.'s FTSE 100 added 0.65%, while Germany's DAX 30 was little changed.
U.S. Treasury prices slipped, as the benchmark 10-year Treasury yield advanced to 0.772% from 0.764% Thursday.
Spot gold price took advantage of a weaker dollar jumping $34 (+1.84%) to $1,928 an ounce.
U.S. WTI crude futures (November) fell $0.66 (-1.60%) to $40.53 a barrel.
On the forex front, the U.S. dollar was broadly lower across the board, pressured by the U.S. government's signal that it could accept a larger stimulus package. The ICE Dollar Index dropped 0.55% to 93.06.
EUR/USD regained the 1.1800 level as it jumped 0.6% to 1.1829. The pair has returned to levels above both its 20-day and 50-day moving averages.
GBP/USD crossed above the key 1.3000 level by rising 0.84% to 1.3046. Official data showed that U.K. industrial production edged up 0.3% on month in August (+2.5% expected).
USD/JPY failed to hold the key 106.00 level and close 0.38% lower at 105.62.
Commodity-related currencies charged higher. AUD/USD surged 1.05% to 0.7240 extending its winning streak to a third session.
USD/CAD was down for a third day sinking 0.57% to 1.3121.
The Chinese yuan (offshore) continued its recent rally against the greenback. USD/CNH slid a further 0.77% to 6.6867, the lowest level since April 2019.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD outlook: Aussie slips despite hawkish RBA ahead of key data
The AUD/USD was unable to benefit from the Reserve Bank of Australia’s 25-basis-point rate hike overnight. The RBA lifted the cash rate to 4.60%, in line with expectations. However, the Australian dollar weakened following the decision, with much of the Bank’s hawkish stance seemingly priced in ahead of the announcement. The US dollar has also remained largely supported following the recent turmoil in the bond markets.
Canadian Dollar Technical Outlook: USD/CAD Seven-Day Rally Tests Major Resistance 9 29 2026
USD/CAD is pressing into a major technical barrier after an extended advance, raising the risk for price inflection as momentum stretches.

RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.