



AUD/USD pulls back ahead of RBA minutes: Asian Open - 18th July 2023
AUD/USD pulled back for a second day to test 68c following weak GDP data from China. The focus now shifts to today's RBA minutes, where a slightly hawkish undertone could support the Aussie later in the session.
Share this:
Market Summary:
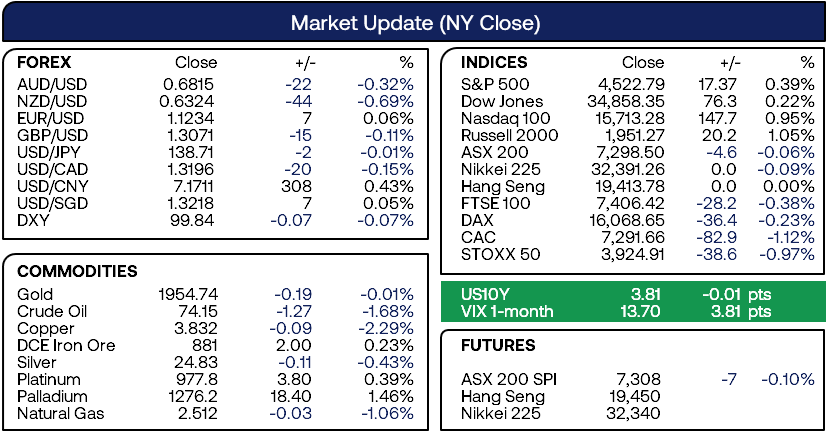
- Wall Street traded cautiously higher on bets that the Fed is near the end of its tightening cycle, backed up by weak economic data from China and US Treasury Secretary Janet Yellen saying the US is on a “good path” to taming inflation without weakening the labour market.
- The S&P 500 closed above 4500 for a second day and sits at a 15-month high, the Nasdaq 100 reached an 18-month high and trades just -6.3% beneath its all-time high
- China’s GDP came in less than expected, but I’m more surprised by some of the ‘surprise’ given data for Q2 was below expectations overall. As always, any signs of weakness from China results in calls for more stimulus.
- NZD and AUD were the weakest FX majors following China’s data, CHF and EUR were the strongest although outside of NZD/USD the daily ranges were relatively small (NZD also felt the pressure of a disappointing business PSI which barely expanded at 50.1)
- Geopolitical tensions are on the rise with Russia backing out of a grain deal which allowed Ukraine to export grain via the black sea, fanning concerns that food prices will be set to rise
- Commodities were broadly lower with Thomson Reuters core commodity index falling to a 4-day low
- President Biden is facing pressure from the US Semiconductor Industry Association to “refrain from further restrictions” on microchip sales to China
- ECB member Nagel said to expect a July rate hike but the September decision remains data dependant
Events in focus (AEDT):
-
11:30 – RBA monetary policy minutes: It is debatable as to how useful the RBA’s minutes will be, given markets took the statement to be a dovish pause and soft US inflation figures takes some pressure off of the RBA to be so aggressive with rate hikes. And if anything is to keep pressure on the RBA to hike it could be Thursday’s employment report. Still, if traders catch a whiff of more hawkishness from the minutes than their statement was deemed to be, AUD/USD could make a decent buy around 68c over the near-term.
- 22:30 – US retail sales: Strong economic data is a double-edged sword for US policy makers, as whilst it provides hopes that the US could avoid a recession it also provides the Fed good reason to keep rates higher for longer. Therefore a strong US retail sales report following Friday’s improved consumer sentiment report simply tells us that consumers are handling higher interest rates, and could help support the US dollar recoup some of last week’s losses.
- 22:30 – Canada’s retail sales: The BOC’s hawkish hike has rekindled bets for another hike in September, and that case could be reinforced if retail sales remains robust and sends the Canadian dollar higher.

Technically Speaking:
-
The US dollar index flirted with a break above 100 on an intraday basis but closed at 99.84 during another low-volatility day near its 15-month lows
- EUR/USD nudged its way to a fresh 17-month high but the conviction behind the ‘breakout’ was low. Still, the intraday trend remains firm and prices are forming a sideways consolidation, and unless we see a USD bullish catalyst then dips may be bought
- It was an indecision day on USD/JPY which formed a Doji, although it was a public holiday in Japan so trading volumes were lower. And whilst Friday’s bullish engulfing candle after its 6-day selloff warns of a correction higher, prices need to break above yesterday’s high to invalidate trend resistance from the March low. For now, intraday timeframes are preferred until momentum tips its hand.
- AUD/JPY retraced lower for a second day and dipped briefly beneath Wednesday’s high before recouping ~50% of yesterday’s losses. If prices can hold above yesterday’s low and appetite for risk improves, we’d look for a move to 96.0
- USD/CNH produced a clear break above Friday’s Doji to confirm the swing low around the 50-day EMA. Bulls now need to break it above 7.20 to clear the 2019 and 2020 highs, failure to do so assumes the next leg lower.
- WTI crude oil retraced lower for a second day on the rise of geopolitical concerns stemming from Russia. Now trading back below the ‘production cut’ high set on June 5th, WTI seems to be respecting round numbers quite well having printed prominent intraday swings at $74, $75 and $76 yesterday. A break of trend support (or rally from it) could be a key focus for traders today.
- Gold is retracing lower and yesterday’s low made the midway point of the 1940 – 1950 liquidity gap we outlined yesterday. A Doji formed on the daily chart, so perhaps we’re getting close to the anticipated swing low and move to the 1985 highs.
ASX 200 at a glance:
- Whilst we were open to the potential that last week’s rally could lose steam, the narrow range of yesterday’s trade came as a bit of a surprise
- A small gravestone Doji formed on the daily chart and closed just below 7300 to show a clear hesitancy to break higher, but also a hesitancy to trade meaningfully lower.
- This reinforced our view that traders may want to focus on intraday timeframes and remain nimble, whilst remaining open to the prospect of a pullback


AUD/USD 1-hour Chart:
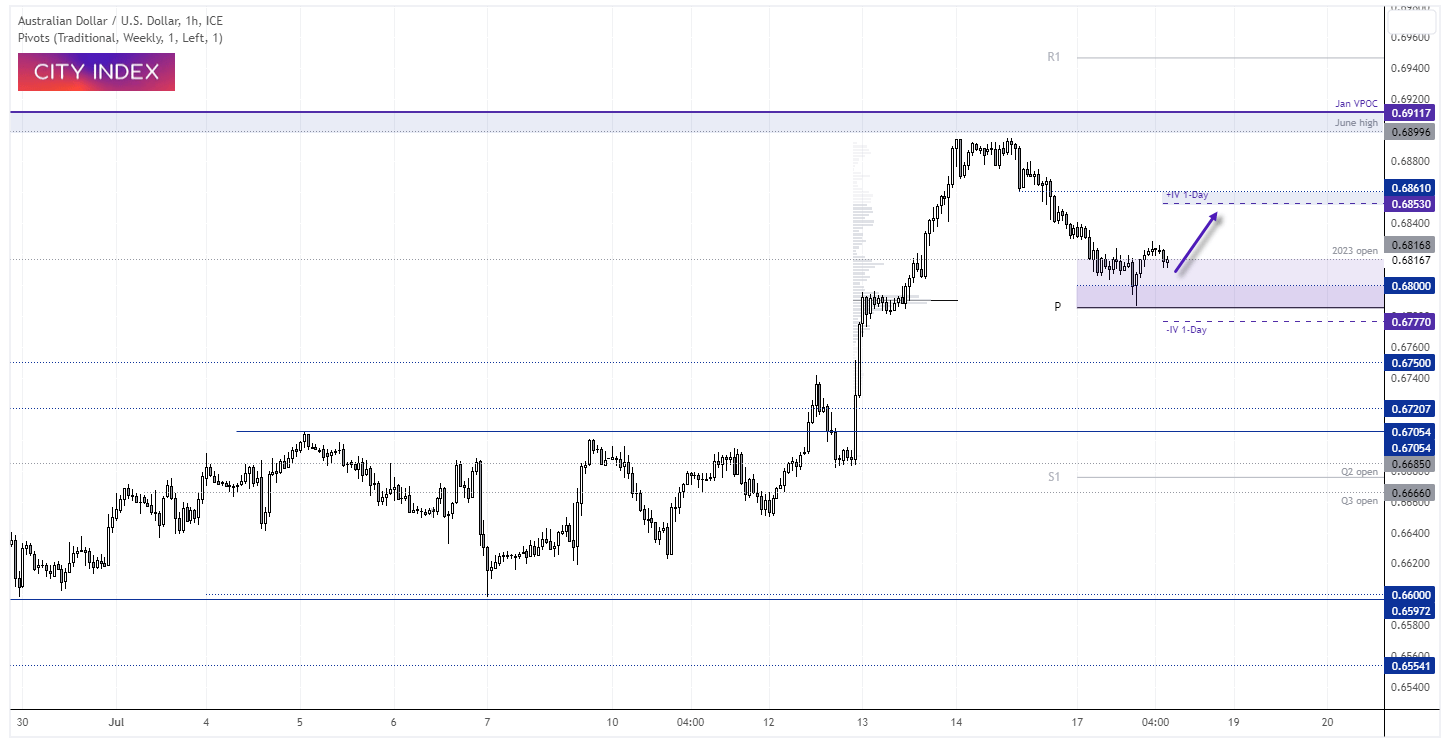
AUD/USD pulled back to 86c in line with yesterday’s bias, which is useful for bulls as it improves the potential reward / risk ratio beneath the 96c handle, near the June high and January VPOC (volume point of control). Yesterday’s low held above the weekly pivot point and now trade back above the 2023 open, so we’d welcome any pullback to 68c for the anticipated move to 0.6850/60 area, near a series of swing low and the upper 1-day implied volatility band. Take note that the RBA minutes are released at 11:30 AEDT, where a hawkish undertone could help support the near-term bullish bias.
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

AUD/USD forecast: Currency Pair of the Week | September 28, 2026
The week has started with stocks, gold, silver and bitcoin all falling, as crude oil rebounded and bond yields pushed further higher. Trump refusing to agree to Tehran’s proposal to re-open the Strait of Hormuz has left the markets disappointed. Still, reports that mediators are expected to hold talks with the two sides on an amended version of the 7-day proposal that Iran presented, keeps hopes alive that we may see some progress.


Gold Outlook: XAU/USD hit hard as US yields, dollar resume ascent
A stronger dollar, surging front-end yields and renewed geopolitical tension have combined to push gold back towards key technical support.


EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.