



USD/JPY hits fresh 7-month high as central banks maintain hawkish mode
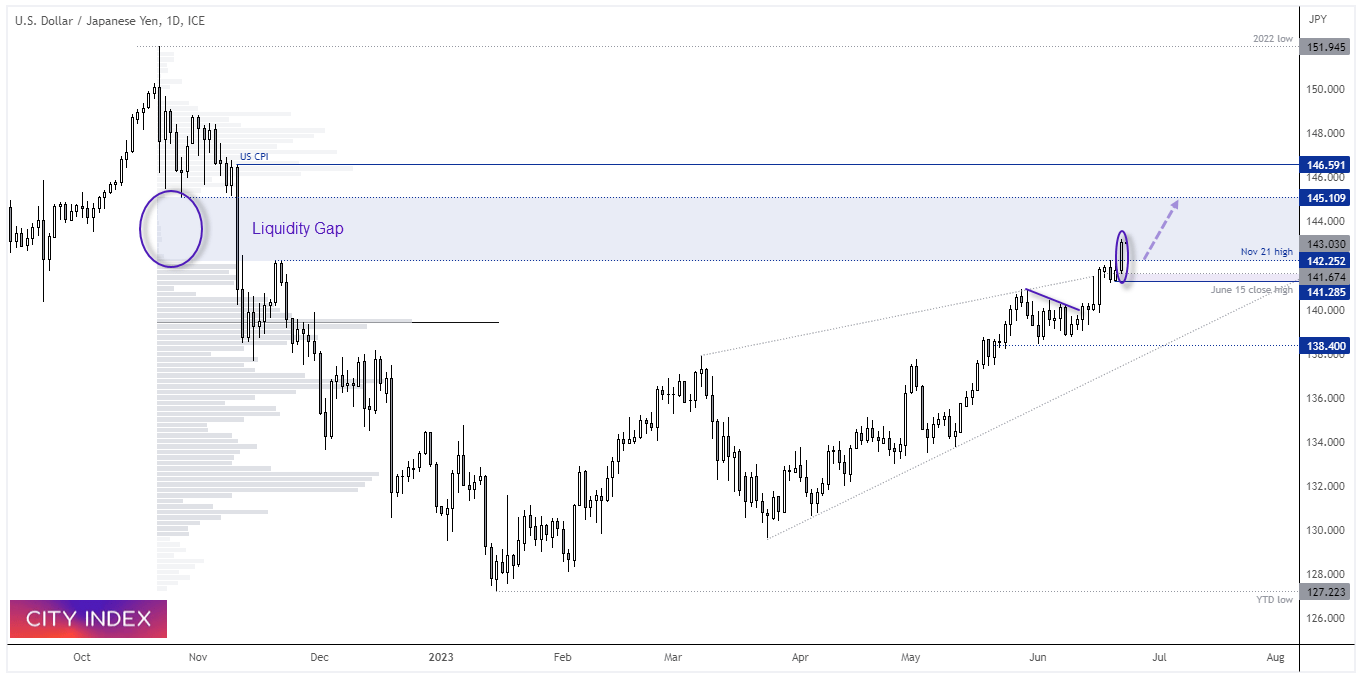
USD/JPY has entered a ~300-pip liquidity gap we highlighted earlier this week, which could see prices rise to the 145 area (unless the BOJ or MOF verbally intervene).
Share this:
Market summary
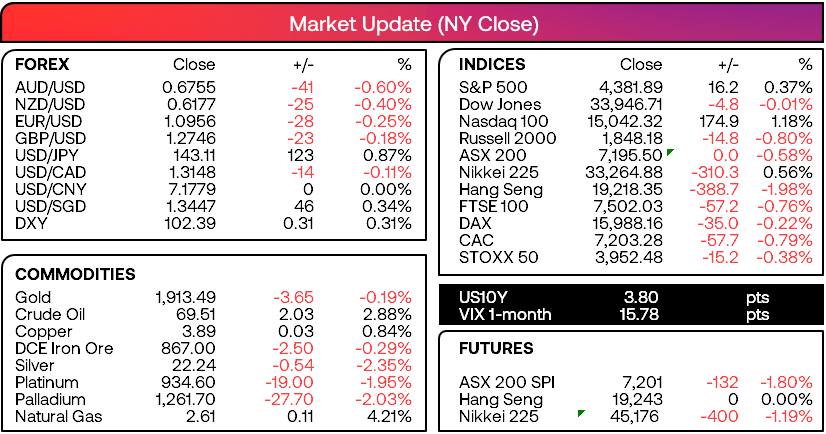
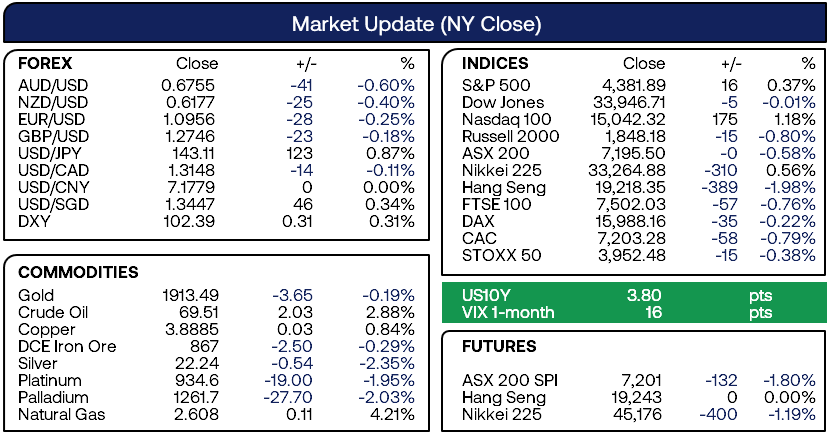
- Short-term bond yields rose overnight as central banks warned that more hikes are coming
- Jerome Powell said hikes will come at a “careful pace” but one or two more may be on the horizon when speaking with the US senate
- Following the surge of UK core inflation to 7.1% y/y on Wednesday, the BOE hiked by 50bp to take rates to 5%
- Whilst no forward guidance was provided, another 25bp hike in August seems very likely with the potential for another two further out (at a minimum)
- The SNB opted for the 25bp consensus to take rates to 1.75%, and expectations are for anther 25bp hike in September
- With central banks maintaining a hawkish stance whilst still fighting inflation, it certainly keeps the pressure on the RBA to hike a further two or three more times
- It also means price action could be scrappy for forex markets as central banks continue their ‘race to the top’ of higher rates / higher currency
- EUR/USD’s break above 1.1000 was short lived, and pulled back to 1.0950 by the close (around the mid point of Wednesday’s range)
- USD/CAD extended its losses to a a fresh 9-month low, although bearish volatility is already subsiding
- AUD/USD held above Wednesday’s hammer low, so we see upside potential within yesterday’s range for today for a purely technical play
- Gold fell to a 3-month low and looks set to head for $1900, with $1919 and $1924 providing potential resistance levels for bears to consider fading into
- Oil prices felt the strain of recessionary fears with WTI falling back within its $67 - $73 range and closing below $70
- European shares bore the brunt of Powell’s speech and the BOE’s 50bp hike, sending the DAX beneath our 16k target before recovering most of the day’s losses by the close
- Despite fears elsewhere, US indices remain the optimists with the S&P 500 and Nasdaq 100 forming bullish engulfing days
Events in focus (AEDT):
- 09:30 – AU manufacturing and services PMI
- 09:50 – JP nationwide CPI
- 10:30 – JP manufacturing and services PMI
- 16:00 – UK retail sales
ASX 200 at a glance:
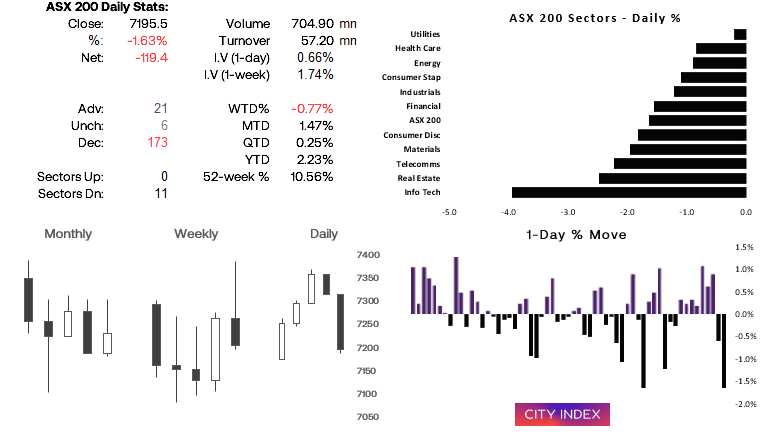
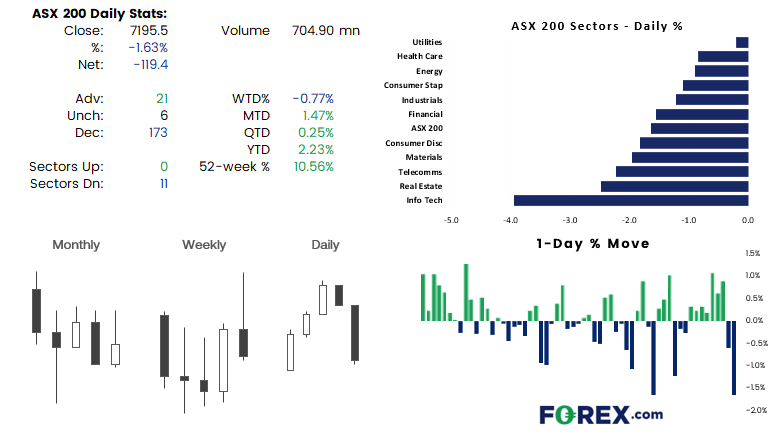
- Most bearish day for the ASX 200 in three weeks
- All 11 sectors were lower, led by IT and real estate
- Volumes were low relative to the bearish candle (lack of fresh sellers)
- Whilst it closed below 7200, a positive lead from Wall Street could soften the blow today
- SPI futures point towards a flat open
- Intraday support level includes 7100, 7147, 7145
- Resistance includes 7200, 2746
USD/JPY daily chart:
Back in November, a soft US inflation report saw markets lower bets for Fed hikes, and the USD/JPY plunged nearly 4% and left a ~300-pip liquidity gap (an area where little or no trading activity took place). These areas can act as a vacuum when prices re-enter them, and USD/JPY did just that on Thursday. Divergent policies and rising yield differentials remain supportive of USD/JPY, so unless the BOJ or MOF verbally intervene and talk of ‘currency volatility’, an initial move to 145 / 145.1 seems plausible. The bias remains bullish above 140.90, although the November high may provide support if prices pull back. And this could increase the potential reward to risk ratio for an anticipated move higher, within the liquidity gap.
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.