



ASX200 Afternoon Report July 28th 2022
The ASX200 trades 64 points higher at 6887 at 3.15 pm Sydney time.
Share this:

The ASX200 trades 64 points higher at 6887 at 3.15 pm Sydney time.
The ASX200 has roared to life today after this morning's FOMC meeting saw the Federal Reserve rates by 75bp as expected and crucially softened its hawkish rhetoric.
The Fed's gentler tone falls just short of a dovish pivot. However, it does remove the tail risks of a debilitating slowdown caused by hiking rates too aggressively into restrictive territory - an outcome that has bolstered risk assets.
The Materials sector has been the day's best performer on the back of stronger commodity prices. Mineral Resources added 7.25% to $52.34, OZ minerals added 6% to $18.26, and Lynas Rate Earths added 2.53% to $8.71. FMG climbed 2.2% to $18.58, BHP added 1.3% to $38.00. Rio Tinto bucked the trend, falling 0.6% to $96.43 as investors digested its earnings report yesterday, which ended its run of record results.
The BNPL sector continued its renaissance following a strong trading update from Sezzle last week, which noted a solid increase in customers and revenues. Building on yesterday's stunning 100% rally, Sezzle has surged another 34% to $0.95c. Tyro Payments added 17.6% to $0.83c, ZIP added 17% to $1.45 while Afterpay owner Block gained 4% to $103.61.
The Financial Sector remains a pillar of strength, building on last week's 4.39% gain. Macquarie Bank added 3% to $178.93, CBA added 1.1% to $99.98, NAB gained 0.6% to $30.32. Westpac added 0.4% to $21.15. ANZ traded flat at $22.73.
After falling off the radar in recent months, gold bugs have begun to stir as the price of bullion extended to $1740 post the FOMC meeting. Newcrest Mining added 2.3% to $7.52, Silver Lake resources added 2.1% to $1.44, Evolution Mining added 1.85% to $2.50, and Newcrest Mining added 0.3% to $18.57.
The only downer on an otherwise solid day was the release of softer than expected retail sales data for June, with growth slowing to 0.2% from 0.7% in May. Against the backdrop of rising rates, high inflation, falling house prices and consumer confidence, belt-tightening has commenced. JB Hi-Fi fell 2.53% to $41.98; Myer fell 2% to $0.49c, and Harvey Norman traded flat at $4.11.
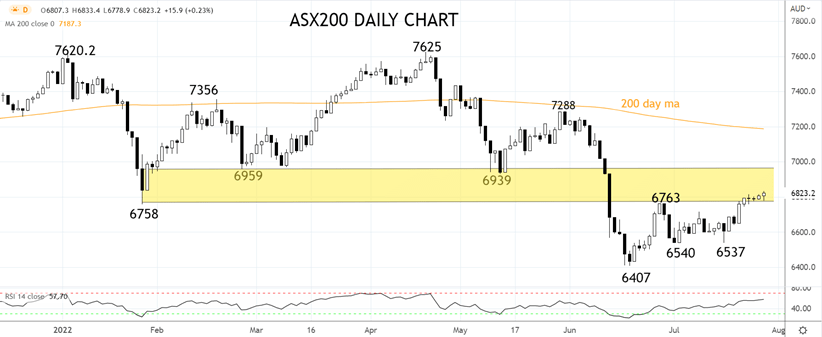
The ASX200 has taken another good chunk out of the 6750/6950 resistance band that it needs to reclaim to negate the technical damage caused by the breakdown in June Until this occurs, the rally from the 6407 low is viewed as a bear market countertrend rally.
Source Tradingview. The figures stated are as of July 28th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
The ASX200 trades 64 points higher at 6887 at 3.15 pm Sydney time.
The ASX200 has roared to life today after this morning's FOMC meeting saw the Federal Reserve rates by 75bp as expected and crucially softened its hawkish rhetoric.
The Fed's gentler tone falls just short of a dovish pivot. However, it does remove the tail risks of a debilitating slowdown caused by hiking rates too aggressively into restrictive territory - an outcome that has bolstered risk assets.
The Materials sector has been the day's best performer on the back of stronger commodity prices. Mineral Resources added 7.25% to $52.34, OZ minerals added 6% to $18.26, and Lynas Rate Earths added 2.53% to $8.71. FMG climbed 2.2% to $18.58, BHP added 1.3% to $38.00. Rio Tinto bucked the trend, falling 0.6% to $96.43 as investors digested its earnings report yesterday, which ended its run of record results.
The BNPL sector continued its renaissance following a strong trading update from Sezzle last week, which noted a solid increase in customers and revenues. Building on yesterday's stunning 100% rally, Sezzle has surged another 34% to $0.95c. Tyro Payments added 17.6% to $0.83c, ZIP added 17% to $1.45 while Afterpay owner Block gained 4% to $103.61.
The Financial Sector remains a pillar of strength, building on last week's 4.39% gain. Macquarie Bank added 3% to $178.93, CBA added 1.1% to $99.98, NAB gained 0.6% to $30.32. Westpac added 0.4% to $21.15. ANZ traded flat at $22.73.
After falling off the radar in recent months, gold bugs have begun to stir as the price of bullion extended to $1740 post the FOMC meeting. Newcrest Mining added 2.3% to $7.52, Silver Lake resources added 2.1% to $1.44, Evolution Mining added 1.85% to $2.50, and Newcrest Mining added 0.3% to $18.57.
The only downer on an otherwise solid day was the release of softer than expected retail sales data for June, with growth slowing to 0.2% from 0.7% in May. Against the backdrop of rising rates, high inflation, falling house prices and consumer confidence, belt-tightening has commenced. JB Hi-Fi fell 2.53% to $41.98; Myer fell 2% to $0.49c, and Harvey Norman traded flat at $4.11
The ASX200 has taken another good chunk out of the 6750/6950 resistance band that it needs to reclaim to negate the technical damage caused by the breakdown in June Until this occurs, the rally from the 6407 low is viewed as a bear market countertrend rally.
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?

USD/JPY unwind accelerates as GPIF headlines spark yen buying
Japanese assets are rallying after the government floated the prospect of the GPIF investing more heavily at home. While the proposal could have significant implications for global capital flows, it does not yet change the broader forces driving Japanese bond yields and USD/JPY.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.