



ASX200 Afternoon Report June 21st 2022
The ASX200 is trading 94 points higher at 6527 at 3pm Sydney time and is set to snap a seven-session losing streak that has wiped over $200 billion off the local index.
Share this:
The ASX200 is trading 94 points higher at 6527 at 3pm Sydney time and is set to snap a seven-session losing streak that has wiped over $200 billion off the local index.
The rally on the ASX200 follows a long weekend in the U.S, which has acted as a circuit breaker of sorts, allowing investors to regroup and take stock after U.S equity markets plunged 10% over the past two weeks.
Also supporting, a speech today by RBA Governor Phillip Lowe, who pushed back on the interest rate markets aggressive pricing of RBA rate hikes and noted it would be unlikely that the cash rate gets anywhere near the 4% the market is currently pricing.
Finally, after a horrific run, the market will start to look at potential rebalancing flows for end of month, end of the quarter and end of financial year, which I would expect to be supportive of stock markets at the expense of fixed income.
Reversing a run of heavy falls, the Energy and the Materials Sectors have been the best on the ground today, supported by a rally in iron ore, coal and crude oil futures prices during the Asian time zone.
Beach Energy (BPT) added 3.87% to $1.61. Woodside (WDS) lifted by 3.97% to $31.57, Origin Energy (ORG) added 2.6% to $5.59, and Santos (STO) added 2.53% to $7.51.
Coal miner, Yancoal (YAL) added 6.36% to $5.35, Whitehaven Coal (WHC) added 4.19% to $4.73, New Hope Coal added 3.75% to $3.33 while Coronado Coal (CRN) added 0.91% to $1.66
Iron Ore heavy weight Fortescue Metals (FMG) added 2.53%% to $17.44, Rio Tinto (RIO) added 2.52% to $104.17, BHP Group (BHP) added 2.55% to $41.72. Elsewhere South32 (S32) added 2.46% to $4.16 while Lynas (LYC) added 4.17% to $8.74.
A rebound also for the financial stock’s supported by lower yields as the Aussie front end cratered following the more dovish tones from the RBA Governor this morning.
National Australia Bank (NAB) added 3.18% to $26.88. ANZ added 2.52% to $21.93, Westpac (WBC) added 2.34% to $19.64, Commonwealth Bank (CBA) added 1.84% to $89.16, and Macquarie (MQG) added 1.7% to $164.33.
A mixed session for the IT sector. Novonix (NVX) added 6.6% to $2.50, Life 360 (360) added 5.8% to $2.75, Afterpay owner Block (SQ2) added 2% to $86.01. Elsewhere, Megaport (MP1) fell 4% to $5.08, more pain for BNPL stock ZIP (ZIP) as it fell 0.94% to $0.53 and Wisetech Global (WTC) fell 0.9% to $35.77.
The roller-coaster ride in the Lithium space continues. Lake Resources (LKE) plunged 21% to $1.07; Core Lithium (CXO) fell 5.6% to $1.02. Elsewhere, Pilbara Minerals (PLS) added 3.43% to $2.11, Allkem (AKE) added 3% to $10.09, and Iluka Resources (ILU) added 2.75% to $8.97.
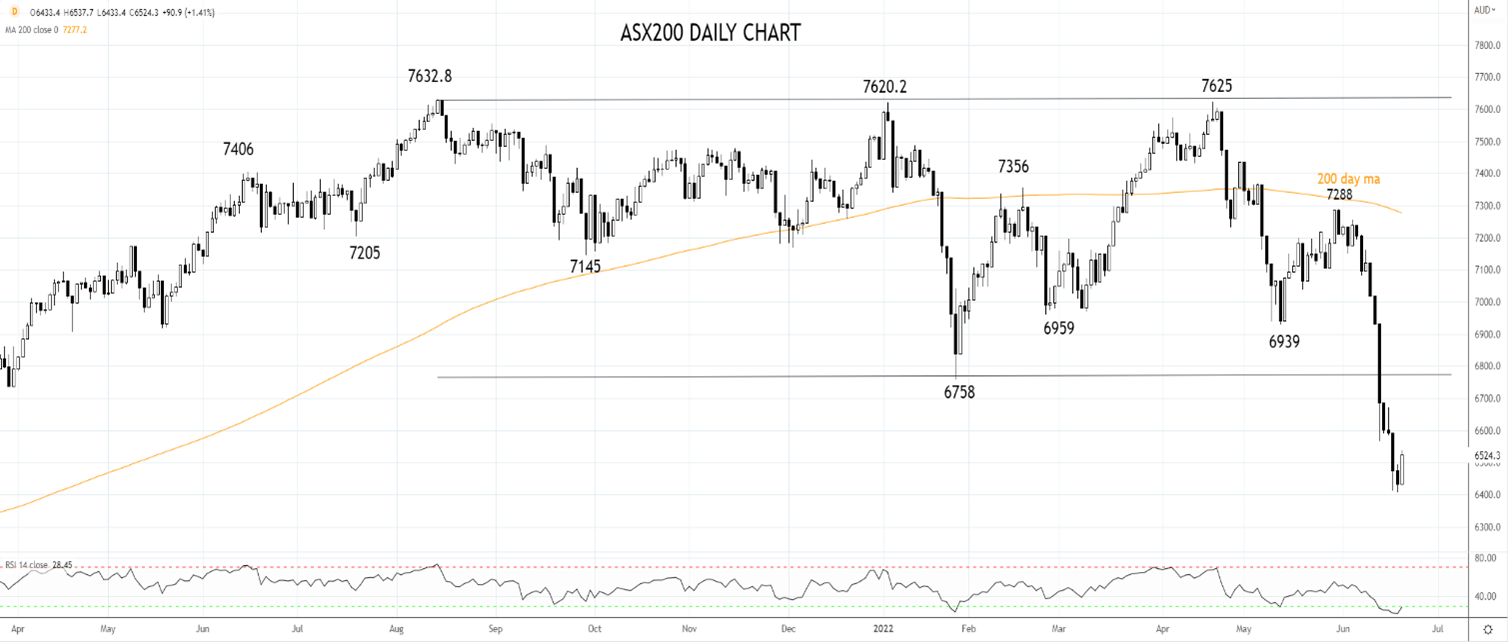
Until last week, the ASX200 appeared to be tracing out an orderly correction - trading just 10% below its all-time highs and within a well-defined nine-month range between 7630 and 6750ish. However, the decisive break from the bottom of the range 6850/6750 early last week created significant technical damage to the index.
The ASX200 must rebound above 6750/6850ish to restore some much-needed confidence in the market. Otherwise, the risks are for the ASX200 to continue lower towards 6000 with scope to 5750 once the expected end of month rally is complete.
Source Tradingview. The figures stated are as of June 21st, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
The ASX200 is trading 94 points higher at 6527 at 3pm Sydney time and is set to snap a seven-session losing streak that has wiped over $200 billion off the local index.
The rally on the ASX200 follows a long weekend in the U.S, which has acted as a circuit breaker of sorts, allowing investors to regroup and take stock after U.S equity markets plunged 10% over the past two weeks.
Also supporting, a speech today by RBA Governor Phillip Lowe, who pushed back on the interest rate markets aggressive pricing of RBA rate hikes and noted it would be unlikely that the cash rate gets anywhere near the 4% the market is currently pricing.
Finally, after a horrific run, the market will start to look at potential rebalancing flows for end of month, end of the quarter and end of financial year, which I would expect to be supportive of stock markets at the expense of fixed income.
Reversing a run of heavy falls, the Energy and the Materials Sectors have been the best on the ground today, supported by a rally in iron ore, coal and crude oil futures prices during the Asian time zone.
Beach Energy (BPT) added 3.87% to $1.61. Woodside (WDS) lifted by 3.97% to $31.57, Origin Energy (ORG) added 2.6% to $5.59, and Santos (STO) added 2.53% to $7.51.
Coal miner, Yancoal (YAL) added 6.36% to $5.35, Whitehaven Coal (WHC) added 4.19% to $4.73, New Hope Coal added 3.75% to $3.33 while Coronado Coal (CRN) added 0.91% to $1.66
Iron Ore heavy weight Fortescue Metals (FMG) added 2.53%% to $17.44, Rio Tinto (RIO) added 2.52% to $104.17, BHP Group (BHP) added 2.55% to $41.72. Elsewhere South32 (S32) added 2.46% to $4.16 while Lynas (LYC) added 4.17% to $8.74.
A rebound also for the financial stock’s supported by lower yields as the Aussie front end cratered following the more dovish tones from the RBA Governor this morning.
National Australia Bank (NAB) added 3.18% to $26.88. ANZ added 2.52% to $21.93, Westpac (WBC) added 2.34% to $19.64, Commonwealth Bank (CBA) added 1.84% to $89.16, and Macquarie (MQG) added 1.7% to $164.33.
A mixed session for the IT sector. Novonix (NVX) added 6.6% to $2.50, Life 360 (360) added 5.8% to $2.75, Afterpay owner Block (SQ2) added 2% to $86.01. Elsewhere, Megaport (MP1) fell 4% to $5.08, more pain for BNPL stock ZIP (ZIP) as it fell 0.94% to $0.53 and Wisetech Global (WTC) fell 0.9% to $35.77.
The roller-coaster ride in the Lithium space continues. Lake Resources (LKE) plunged 21% to $1.07; Core Lithium (CXO) fell 5.6% to $1.02. Elsewhere, Pilbara Minerals (PLS) added 3.43% to $2.11, Allkem (AKE) added 3% to $10.09, and Iluka Resources (ILU) added 2.75% to $8.97.
Until last week, the ASX200 appeared to be tracing out an orderly correction - trading just 10% below its all-time highs and within a well-defined nine-month range between 7630 and 6750ish. However, the decisive break from the bottom of the range 6850/6750 early last week created significant technical damage to the index.
The ASX200 must rebound above 6750/6850ish to restore some much-needed confidence in the market. Otherwise, the risks are for the ASX200 to continue lower towards 6000 with scope to 5750 once the expected end of month rally is complete.
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Cyclical stocks sniff out better times ahead
Different economies, different drivers, similar price action. The German DAX, ASX 200 and Russell 2000 are all hinting at a more optimistic view on the global economy.
Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.