




AUD/USD, ASX 200 Analysis: Morning Brief - 25th May 2023
Share this:

Market summary
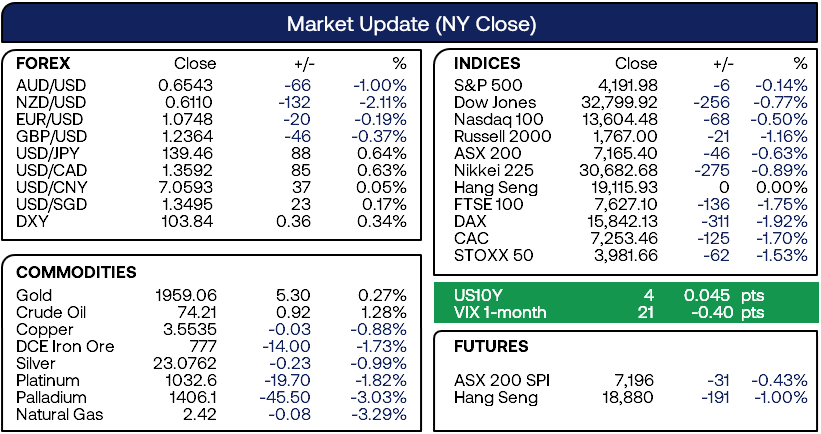
- The USD was the strongest major following slightly hawkish FOMC minutes which suggested further hikes depends on incoming data (AUD/USD hit a YTD low)
- Participants agreed that inflation was unacceptably high and declining slower than expected
- Fed staff continue to forecast a mild recession later this year, followed by a modestly-paced recovery
- Some members stressed it was ‘crucial’ the statement not signal cuts this year or rule out further hikes
- Some members commented that additional policy firming may be warranted at future meetings, others suggested it may not be needed
- The NZD was sharply lower after the RBNZ hiked rates by 25bp yesterday and signalled it could be their last hike of the cycle (their 12th consecutive cycle took rates to 5.5%)
- Citing lower demand and a government budget that was not expected to be as inflationary as quickly as feared saw them retain their OCR forecast for a peak of 5.5%
- NZ retail sales was also softer than expected, contracting -4.1% q/q (-0.6% expected) and -4.1% y/y (-4% expected)
- EUR/USD fell to a 2-month low after German business sentiment continued to deteriorate, with IFO breaking a 6-month rise and finally tracking the ZEW lower
- GBP was initially stronger following another set of hot CPI numbers, although producer prices continue to soften so it is likely a matter of time before this feeds through to consumer prices
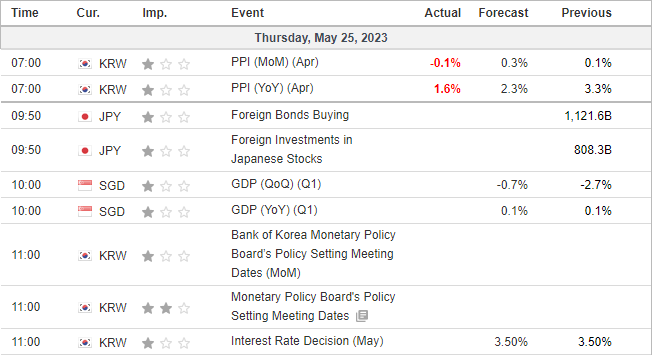
- Deflationary forces continue to appear across Asia with North Korean producer prices (a key export economy) falling to 1.7% y/y and -0.1% m/m
- Wall Street finished lower for a fourth day as debt-ceiling negotiation failed to produce any results
- Fitch placed the US on a 'AAA' ratings watch due to the risk of not raising the debt ceiling, which basically means they will be downgraded if a deal is not achieved
ASX 200 at a glance
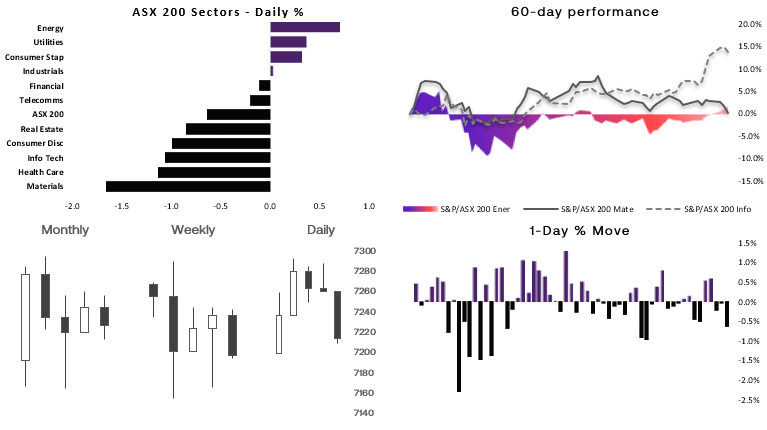
- The ASX closed lower for a third day, in line with yesterday’s bearish bias
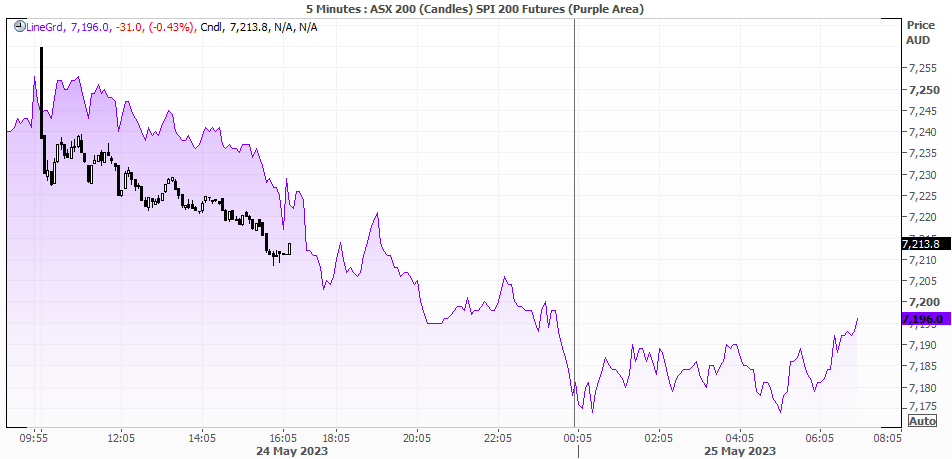
- Wall Street and SPI futures point to a weak open
- 7200 and 7165 are potential support levels today
- Financial stocks could face pressure, whilst energy stocks may be able to outperform (but not be overly strong) due to supported oil prices
AUD/USD daily chart:


A stronger US dollar, weaker commodities and a dovish RBNZ hike weighed on the Australian dollar, breaking it out of its 1-week range to a YTD low. Bears could consider swing trades below the 0.6600 area with 0.6500, 0.6440 (61.8% projection) and 0.6400 handle providing potential target area.
Events in focus (AEDT):
- No major economic events are schedule for today’s Asian session
- 22:30 – US Q1 GDP, jobless claims
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.